Content Type: Article

  • Biting the hand that feeds? California faces new proposed wealth tax

    Biting the hand that feeds? California faces new proposed wealth tax

    ARTICLE

    Biting the hand that feeds? California faces new proposed wealth tax

    Nov 7, 2025

    Read time: 4 min

    Key takeaways
    Overview

    California’s reputation as a hub for innovation and entrepreneurship may soon collide with an ambitious new tax proposal. Initiative 25-0024, known as the 2026 Billionaire Tax Act, would levy a proposed “one-time” 5% excise tax in tax year 2026 on applicable individuals and trusts with a net worth of $1 billion or more. It would tax all “forms of personal property and wealth, whether tangible or intangible.” The initiative broadly defines an “applicable individual” to include California residents and part-year residents as far back as January 1, 2025, reminiscent of the Eagles anthem “Hotel California”: “You can check out anytime you like, but you can never leave.”

    Filed with the California Attorney General’s Office late last month by the Service Employees International Union (SEIU), Initiative 25-0024 is currently undergoing a 30-day public review process. During this time, members of the public can submit comments on the proposed initiative and the SEIU can submit amendments to the initiative that are “reasonably germane to the theme, purpose, or subject of the initiative measure as originally proposed.” Cal. Elections Code § 9002(b). The attorney general also generally has 65 days (here, until December 26, 2025) from the date the proposed initiative was first received to issue a circulating title and summary, which will be the official summary of the proposed initiative measure. Thereafter, proponents have a maximum of 180 days to collect at least 874,641 voter signatures to qualify for the November 2026 ballot. If qualified, Initiative 25-0024 may only require a simple majority vote to pass.

    The SEIU has framed Initiative 25-0024 as a cure to the anticipated $30 billion annual state budget shortfall from federal funding cuts to California’s Medicaid program. The SEIU also argues that the proposed tax is “fair” because “billionaires have used state resources to create their enormous wealth and were the largest beneficiaries of the federal legislation that contributed to the current California budget crisis.” Citing research from the Fiscal Policy Institute, which shows that high earners move out of state at lower rates than individuals in other income brackets, even in response to a personal income tax increase, some proponents claim that threats of a mass exodus are just that – idle threats.

    But opponents remain skeptical, pointing to the graveyard of billionaire wealth tax proposals – Assembly Bill (AB) 259, AB 2289, AB 310, and AB 2088 – that have been introduced and abandoned by the California legislature in the past five years. Moreover, the history of California is replete with so-called “one-time” or otherwise “temporary” levies that ended up being permanent. It is unclear whether this initiative will help or hurt California in the longer term. Given that the top 1% of taxpayers pay more than 40% of California personal income taxes, if even some of those high-net-worth individuals are incented to leave California, the gap in tax collections could grow even larger, increasing the annual tax burden upon those taxpaying residents who remain in California.

    If enacted, Initiative 25-0024 likely will invite constitutional challenges on multiple grounds. For example, imposing a retroactive tax arguably violates California due process protections. Additionally, challenges likely will be filed on behalf of nonresidents who no longer have nexus with the state (i.e., persons who were California residents as of January 1, 2025, but are no longer residents in tax year 2026). Some of these challenges (and others) may be successful, but even if not, high-net-worth individuals and trusts may simply renew their focus on tax planning strategies to mitigate the impact.

    Administrability issues also are certain to arise as the initiative would only reimburse the California Franchise Tax Board (FTB) up to $15 million annually for the “actual and necessary costs” of administering the tax. By comparison, FTB estimated that it would need $200 to $300 million per year to administer the 1.5% billionaire wealth tax proposed in 2023 under AB 259.

    Although Initiative 25-0024 is framed as a “one-time” excise tax, its policy implications could be far-reaching, touching questions of tax fairness, state competitiveness, and the limits of state taxing authority. We will continue tracking updates as Initiative 25-0024 continues through the ballot approval process. Please contact the authors with any questions about this proposed initiative.

    Authors

    Charles Moll III

    Partner

    San Francisco

    Troy M. Van Dongen

    Partner

    San Francisco

    More insights
    Endnotes

  • The UK FCA consults on changes to the UK short selling regime

    The UK FCA consults on changes to the UK short selling regime

    ARTICLE / CLIENT ALERT

    The UK FCA consults on changes to the UK short selling regime

    November 7, 2025

    Read time: 7 min

    Key takeaways
    Overview

    On 28 October 2025, the Financial Conduct Authority (FCA) published a consultation paper setting out proposed changes to the UK short selling regime.

    This comes hot on the heels of the publication of the UK Short Selling Regulations 2025 (UK SSR), which outlines the legislative framework for the New SSR and draws heavily on feedback to the Treasury call for Evidence. The New SSR will be published and maintained by the FCA in a new short selling sourcebook in the FCA Handbook.

    In depth

    Summary of changes

    Whilst the new regime retains the core features of the current UK short selling regime, targeted adjustments have been proposed which are designed to ‘reduce unnecessary and disproportionate costs which may inhibit or discourage short selling activity’ whilst maintaining transparency of short selling activities in the UK market.1

    The proposed reforms of the UK SSR include changes to:

    • Public Disclosure: Whilst position holders will still be required to report net short positions (NSPs) in shares admitted to trading on a UK trading venue to the FCA when they are at, above, or subsequently fall below the reporting threshold (0.2% of issued share capital of the issuer) and each 0.1% increment, the FCA intends to only publish the aggregated anonymised NSPs, without naming individual position holders. This should mitigate the risk of inadvertently revealing trading strategies of position holders, encouraging short squeezes (e.g., because of ‘herding’ activities) and ‘retaliation’ against position holders.
    • Position reporting submission deadline: Position holders are to be given more time to report their NSPs to the FCA as the reporting deadline will be extended from 15.30 (UK time) T+1 to 23.59 (UK time) T+1. This change will be particularly helpful to position holders based outside of the UK.
    • List of reportable shares: The FCA will publish and maintain a reportable list of shares that will be in scope of the UK SSR based on updated criteria and considerations (the RSL). This means that position holders will no longer have to individually work out which shares are within scope of the regime and should reduce the risk of technical breaches. In addition:
      • The RSL will be machine readable, reviewed by the FCA every two years and updated (at least) every month.
      • The RSL will go live two months before the New SSR comes into force.
    • Calculations: The FCA provides the following clarifications in relation to the calculation of the NSPs:
      • The NSP can be calculated at any point before the position report is submitted based on the position (e.g., the issued share capital of the issuer and the long/short position of the position holder) as at midnight at the end of the relevant trading day. This broadly reflects current market practice, but it is a useful clarification.
      • The FCA will provide new guidance on the sources of information that can be used for determining the issuer’s issued share capital. These include Companies House filings, information from commercial data providers and DTR disclosures. Whilst this guidance is helpful, it falls short of proposing a ‘golden source’ for such calculations.
      • The FCA is proposing to continue to require position holders to include positions held through index derivatives and index tracking ETFs in their NSP calculations.
      • The exclusion of convertible bonds from the calculation will be maintained.
    • Group reporting: The FCA is proposing to tweak the group reporting requirements to avoid gaps or double counting. Unhelpfully, positions managed by different asset management entities within the same group will continue to be required to be reported on an individual investment manager basis, rather than being aggregated at the group level.
    • Waivers: Position holders will be permitted to apply for waivers from the requirement to report in exceptional circumstances (e.g., material systems outages which impact the ability of position holders to report), which is a helpful mitigant against the risk of technical breaches.
    • Market maker notifications: The reforms include provision to simplify and streamline the exemptions regime, including:
      • The reduction of the deadline for notifying the FCA of the intended use of the market maker exemption from 30 calendar days to 15 calendar days.
      • The simplification of the process for existing market makers to notify the FCA of their intention to extend the exemption to cover new financial instruments.
      • The removal of the requirement to provide volume estimates in market maker exemption notifications, where such activities have been conducted in a share for less than six months.
      • The introduction of a transition provision to allow legacy market makers’ exemptions to remain in place until 1 June 2027. This means that market makers will need to submit new exemption notifications to the FCA no later than 1 June 2017.
    • New online exemption notification and reporting system: The FCA intends to automate and simplify the notification and position reporting system, which will include a bulk submission functionality to enable position holders to upload and submit multiple positions simultaneously. The new forms will be made available to position holders during the interim period. However, as noted above, the FCA does not intend to ‘port’ legacy exemptions across to the new system, which means that firms will have to reapply for the exemptions.
    • Cover arrangements: As well as the position holders needing to be entitled to receive the shares on or before the settlement of the short sale, the FCA provides clarification that they will also need to ensure that settlement can be effected when due.
    • Record-keeping of cover arrangements: The new rules will clarify that records demonstrating appropriate ‘cover agreements and arrangements’ should be maintained for at least five years rather than for five years.2
    • Exercise of emergency powers: The FCA also confirms that the bar for exercising its emergency intervention powers (e.g., to prohibit, restrict and request further information) in relation to short selling will remain ‘high’.

    Sovereign debt

    The rules applicable to sovereign debt are not specifically covered in the FCA consultation paper, on the basis that this has already been addressed in the UK SSR. However, it is important to note that, in line with the UK SSR, the existing disclosure regime for sovereign debt and the prohibition of uncovered short sales of sovereign debt and UK sovereign credit defaults swaps will be abolished when the New SSR comes into force.

    Timing

    The FCA will publish its policy statement and final rules two months in advance of the commencement date (which is yet to be confirmed).

    The new SSR will be implemented in two phases as follows:

    • Phase 1: The new systems for calculating and publishing NSPs and the RSL will come into effect on the commencement date.
    • Phase 2: Six months after the commencement date, the FCA will update its systems for position reports and market maker exemption notifications.

    Conclusion

    Whilst the proposed changes to the UK SSR represent a departure from the EU short selling regime, some of the proposed UK rules appear to align with the new US short selling rules (e.g., anonymised public disclosure of NSPs).

    Although the targeted reforms will be welcomed by market participants, there is still scope for further change. Therefore, market participants should actively engage with the FCA during the consultation process to ensure a sensible outcome is reached. In this regard, market participants will have until 16 December 2025 to respond to the consultation paper.


    Feel free to reach out to our team if you would like to learn more about the changes to the UK short selling regime.

    Our team include: Karen Butler, Josh Dambacher, and Christopher Hilditch in London, and Marc Elovitz, Kelly Koscuiszka, William Barbera, and Adriana Schwartz in New York.

    Authors

    Karen Butler

    Partner

    London – One Eagle Place

    Josh Dambacher

    Partner

    London – One Eagle Place

    Christopher Hilditch

    Partner

    London – One Eagle Place

    More insights

  • IRS roundup: October 23 – November 6, 2025

    IRS roundup: October 23 – November 6, 2025

    ARTICLE

    IRS roundup: October 23 – November 6, 2025

    Nov 7, 2025

    Read time: 5 min

    Check out our summary of significant Internal Revenue Service (IRS) guidance and relevant tax matters for October 23, 2025 – November 6, 2025.

    October 23, 2025: The IRS issued frequently asked questions, addressing its revisions and updates to Form 1099-K following changes resulting from the One Big Beautiful Bill Act (OBBBA). The OBBBA retroactively reinstated the reporting threshold in effect prior to the passage of the American Rescue Plan Act of 2021 (ARPA). This means that a third-party settlement organization (TPSO), which is a type of payment settlement entity, is generally not required to file a Form 1099-K. However, TPSOs will be required to file a Form 1099-K if the gross amount of reportable payment transactions to a payee exceeds $20,000 and if the number of reportable payment transactions exceeds 200. Previously, under the ARPA reporting threshold, TPSOs had to file a Form 1099-K for any payee that received more than $600 in total payments for the sales of goods or services, regardless of the number of reportable payment transactions.

    October 27, 2025: The IRS reminded tax preparers that preparer tax identification numbers (PTINs) must be renewed annually and that the 2026 renewal period is now open. All 2025 PTINs will expire on December 31, 2025.

    November 3, 2025: The IRS released Internal Revenue Bulletin No. 2025-45, which includes Notice 2025-61. Notice 2025-61 provides guidance on the adjusted applicable dollar amount for the Patient-Centered Outcomes Research Trust Fund (PCORTF) fee, which is imposed on issuers of specified health plans and plan sponsors of applicable self-insured health plans to fund PCORTF. Notice 2025-61 specifically provides the increased adjusted applicable dollar amount for determining the PCORTF fee as $3.84 (from the previous set amount of $3.47) for all policies and plans ending on or after October 1, 2025, and before October 1, 2026. The IRS explained that the amount was calculated by US Department of the Treasury economists based on the percentage increase in the projected per capita amount of National Health Expenditures, which was published by the US Department of Health and Human Services in June 2025.

    November 5, 2025: The IRS issued Notice 2025-62, providing guidance on penalty relief for taxable year 2025 in connection with the implementation of new information reporting requirements related to the deductions for qualified tips and qualified overtime compensation to reflect amendments resulting from the OBBBA. Notice 2025-62 specifically provides relief for taxable year 2025 from the penalty under Section 6721 for failure to file correct information returns and the penalty under Section 6722 for failure to furnish correct payee statements. The IRS also announced that guidance on how taxpayers can claim these deductions on their tax return for the 2025 tax year is forthcoming.

    The IRS also released its weekly list of written determinations (e.g., Private Letter Rulings, Technical Advice Memorandums, and Chief Counsel Advice).

    In depth
    Authors

    Evan Walters

    Partner

    Chicago

    Samuel F. Hamer

    Associate

    Washington, DC

    Edward L. Froelich

    Counsel

    Washington, DC

    Michael J. Scarduzio

    Partner

    New York – One Vanderbilt Avenue

    Suzanne Golshanara

    Associate

    Washington, DC

    More insights
    Endnotes

  • HHS GPS v2.0 + HRSA “strategic priority areas”: Impact on federal grant recipients engaged in pediatric gender-affirming care

    HHS GPS v2.0 + HRSA “strategic priority areas”: Impact on federal grant recipients engaged in pediatric gender-affirming care

    ARTICLE

    HHS GPS v2.0 + HRSA “strategic priority areas”: Impact on federal grant recipients engaged in pediatric gender-affirming care

    November 5, 2025

    Read time: 2 min

    Key takeaways
    Overview

    Effective October 1, 2025, the US Department of Health and Human Services (HHS) implemented grants policy statement (GPS) v2.0, consistent with its prior adoption of 2 CFR part 200 with HHS-specific provisions at 2 CFR part 300. Separately, the Health Resources and Services Administration (HRSA) published a strategic priority areas memorandum stating that, subject to applicable law and court orders, HRSA will deprioritize programs that engage in certain medical interventions for minors with gender dysphoria, and HRSA funds will not support the costs of those practices.

    In practice, “deprioritize” has two dimensions: lower competitiveness in discretionary selections and a likelihood that such costs will be treated as unallowable under the terms of award. A nationwide preliminary injunction (PFLAG v. Trump) and a four-state preliminary injunction (Washington v. Trump) currently prohibit HHS/HRSA from punishing recipients because they provide gender-affirming care (GAC) to people under age 19, but the injunctions do not convert costs that are identified as not supported in the award into allowable charges.

    The following frequently asked questions (FAQs) explain GPS v2.0, HRSA’s “deprioritization” efforts and provide practical strategies for recipients engaged in pediatric GAC.

    In depth
    Authors

    Travis Jackson

    Partner

    Los Angeles

    More insights

  • NYDFS clarifies expectations for third-party cybersecurity risk management

    NYDFS clarifies expectations for third-party cybersecurity risk management

    ARTICLE / CLIENT ALERT

    NYDFS clarifies expectations for third-party cybersecurity risk management

    November 5, 2025

    Read time: 6 min

    Key takeaways
    Overview

    On October 21, 2025, the New York State Department of Financial Services (NYDFS) issued an industry letter highlighting risks associated with third-party service providers – such as providers of cloud computing, file transfer systems, artificial intelligence (AI), and FinTech solutions – and strategies for managing these risks as part of an effective cybersecurity program under its cybersecurity regulation, 23 NYCRR Part 500 (Part 500).

    The letter reflects NYDFS’s continued focus on third-party risk as a leading source of cybersecurity exposure. The letter is not a formal rule or amendment under Part 500, and the letter even expressly states that it does not impose new requirements or obligations on covered entities. However, this prescriptive guidance signals supervisory priorities and establishes practical benchmarks for the cybersecurity protections NYDFS examiners may expect to see with respect to covered entities’ third-party risk management programs. Covered entities should take this guidance seriously and assess whether their programs meet such expectations.

    In depth

    The industry letter describes steps covered entities should consider taking to assess and address cybersecurity risks throughout the lifecycle of a third-party service provider relationship, including diligence considerations when selecting service providers, contractual protections addressing cybersecurity responsibilities, ongoing monitoring of controls, and the eventual termination of the relationship.

    Some takeaways from the guidance include:

    Active governance

    The letter highlights the accountability of senior governing bodies and officers in effectively overseeing and managing third-party service provider-related risks. Senior governing bodies and senior officers must engage actively in cybersecurity risk management and, unless an exemption applies, sufficiently understand cybersecurity risks and be able to credibly challenge management’s cybersecurity-related decisions. The letter also emphasizes that covered entities may not delegate responsibility for compliance with Part 500 to an affiliate or a third-party service provider.

    Due diligence and selection

    NYDFS expects risk-based vetting of third-party service providers. The letter includes a non-exhaustive list of due diligence considerations, such as:

    • The type and extent of system and data access
    • The service provider’s reputation, including its cybersecurity history and financial stability
    • Whether the service provider’s cybersecurity program addresses the cybersecurity practices and controls required by the covered entity and Part 500
    • The criticality of the services provided and the availability of alternative service providers
    • The service provider’s use of unique, traceable accounts for personnel access and the maintenance of audit trails
    • The location of the service provider and its affiliates and vendors
    • The regular testing of incident response and business continuity plans
    • The service provider’s service provider diligence process
    • Whether the service provider undergoes external audits or independent assessments or can demonstrate compliance with Part 500 or industry cybersecurity frameworks

    Contractual protections

    The letter includes examples of baseline contractual provisions covered entities should consider incorporating into their third-party service provider agreements, such as:

    • Obligations to develop and implement policies and procedures addressing access controls (including multifactor authentication (MFA)) and encryption in transit and at rest
    • Cybersecurity event notifications
    • Compliance representations and warranties

    The letter also recommends incorporating contract terms addressing:

    • Disclosure of where data may be stored, processed, or accessed
    • Restrictions on cross-border transfers
    • Compliance with data residency or localization laws
    • Disclosure of the use of subcontractors, and the ability to reject the use of certain subcontractors
    • Data use and sharing restrictions, data deletion or migration obligations upon termination of the service provider relationship, and appropriate certifications confirming the completion of such steps
    • Restrictions relating to the acceptable use of AI (this reinforces guidance NYDFS issued last year regarding cybersecurity risks arising from AI)
    • Remedies, such as timely remediation or early termination, in the event the service provider breaches material cybersecurity terms

    Ongoing monitoring and oversight

    The letter requires covered entities’ third-party risk management policies to address, to the extent applicable, the periodic and risk-based assessments of service providers. The policies and procedures for ongoing service provider oversight and monitoring should be informed by a variety of factors, such as the evolving threat and regulatory landscape, changes to products and services, and whether the service provider experienced a cybersecurity event. The letter also instructs covered entities to, where relevant, request updates on vulnerability management, access patching practices, and confirm remediation of identified vulnerabilities. Covered entities should also incorporate third-party risk into their incident response and business continuity planning.

    Termination

    The letter outlines certain actions that covered entities should take before and after the end of a third-party service provider relationship, which include disabling the service provider’s access to the covered entity’s information systems and confirming the deletion of data from the service provider’s systems. The letter also instructs covered entities to develop a transition plan for critical services with clearly defined timelines, roles, and responsibilities to ensure a secure and orderly termination.

    Next steps

    NYDFS emphasized that it will continue to consider the absence of adequate third-party risk management practices in its examinations, investigations, and enforcement actions. In light of this guidance, covered entities should:

    • Reassess existing service provider relationships for compliance with Section 500.11 and related obligations under Part 500
    • Benchmark current third-party risk management policies and procedures against NYDFS’s recommended practices
    • Conduct a gap analysis of existing service provider contracts
    • Engage legal, compliance, and IT teams to enhance service provider oversight and incident response planning

    Additionally, the final phase of the 2023 amendments to Part 500 went into effect on November 1, 2025. As of that date, unless an exemption applies, covered entities are required to implement 1) MFA for any individual accessing their information systems, subject to limited exceptions, and 2) written asset inventory policies and procedures. Covered entities should review their cybersecurity programs in preparation for heightened NYDFS scrutiny with respect to MFA and asset inventories in addition to third-party oversight.

    If you have questions or would like to discuss any issues addressed in this client alert, contact your regular McDermott Will & Schulte lawyer or one of the authors.

    Authors
    More insights

  • US Treasury’s Outbound Investment Security Program: Lessons and insights

    US Treasury’s Outbound Investment Security Program: Lessons and insights

    ARTICLE / CLIENT ALERT

    US Treasury’s Outbound Investment Security Program: Lessons and insights

    November 4, 2025

    Read time: 24 min

    Key takeaways
    Overview

    On January 2, 2025, the US Department of the Treasury’s (Treasury) Final Rule implementing the Outbound Investment Security Program (OISP) pursuant to Executive Order 14105 went into effect, under which US Persons are prohibited from engaging in, or are required to provide notification to Treasury of, certain investments involving persons of so-called “Countries of Concern” (currently, the People’s Republic of China, including the Special Administrative Regions of Hong Kong and Macau) that operate in certain technology sectors (Covered Foreign Persons and such transactions involving Covered Foreign Persons, Covered Transactions). The OISP seeks to minimize the transfer of funding and “intangible benefits” from US investors to certain targeted sectors of China’s economy that could “accelerate and increase the success of the development of sensitive technologies” against US interests. Such intangible benefits are described in Executive Order 14105 to include “enhanced standing and prominence, managerial assistance, investment and talent networks, market access, and enhanced access to financing.” The current restrictions and reporting requirements are focused on investments relating to specified technologies currently consisting of: semiconductors and microelectronics; quantum information technologies; and certain artificial intelligence (AI) systems (collectively, Covered Activities).

    The OISP has now been in effect for more than 10 months and applies to any transaction that closed or closes after January 2, 2025. Treasury has been releasing guidance in the form of frequently-asked-questions (FAQs) clarifying certain aspects of these new regulations. The Trump administration has also signaled that it is considering expanding restrictions on US investment in China, including by modifying the scope of the OISP, in the America First Investment Policy Memorandum, on February 21, 2025.

    This client alert summarizes the scope of the obligations that the OISP imposes on US Persons and market trends from the first 10 months of the OISP’s implementation that asset managers should consider, as well as future developments we are watching for.

    In depth

    Takeaways

    The OISP imposes obligations on US Persons, including asset managers, relating to direct or indirect investments in China. Notably, unlike sanctions programs that restrict US Persons from dealing with persons and entities designated on a sanctions lists, Treasury is not establishing a list of Covered Foreign Persons subject to the requirements of the OISP. US Persons are expected to conduct their own due diligence on investment targets to ensure compliance with the OISP. Additionally, while the OISP has sometimes been referred to as a “reverse CFIUS,” it differs in many aspects, including that compliance is solely the responsibility of US Persons and not their foreign counterparties, and, unlike CFIUS, the OISP preemptively prohibits certain transactions.

    In assessing the implications of the OISP, some key compliance measures for asset managers to consider include:

    • Conducting a risk assessment on investment strategies and portfolios to determine existing or future exposure to potentially Covered Transactions.
    • Educating/training investment teams and compliance personnel on the OISP, and in the case of non-US entities, instituting recusal policies for US Person personnel.
    • Monitoring any new guidance from Treasury (such as FAQs) that may impact the OISP, as well as keeping apprised of executive branch and legislative efforts to modify or expand the OISP.
    • Adopting a standalone OISP policy or amending existing regulatory policy documents, as well as adding trading restrictions in order management systems to monitor for OISP issues.
    • Updating due diligence procedures to include assessments (such as through questionnaires) consistent with Treasury’s “reasonable and diligent inquiry” standard to determine whether investment targets are within the OISP’s scope, and ensuring that such diligence is documented, retained, and shared across investment teams.
    • Seeking contractual commitments from unaffiliated general partners or managers/sub-advisors regarding OISP compliance.
    • Determining whether any US-managed foreign funds have US investors and whether engaging in potential Covered Transactions may trigger reporting requirements for those investors.
    • Anticipating requests for representations from counterparties regarding Covered Transactions and evaluating how those representations align with compliance obligations under the OISP (which may differ for US and non-US funds) and the fund’s investment strategies, particularly with respect to permissible notifiable transactions.
    • If a target has connections to China, Hong Kong, or Macau (either directly or through controlled affiliates), further investigation is needed by Legal/Compliance. Be particularly aware of investment targets involved in the semiconductors, quantum computing, and AI sectors, even if such sectors are not the primary focus of the investment target.
    • Considering reputational risks of engaging with Covered Foreign Persons, even if a transaction would only be notifiable.

    Below we outline the key provisions of the OISP that asset managers and investors should consider in assessing the impact of the OISP on their investments and any compliance measures they may need to implement.

    Key provisions and definitions of the OISP

    Under the OISP, US Persons (discussed below) are required to determine if they are engaging in a transaction with a potential investment target that is a Covered Foreign Person. Depending on the nature of technology-based activities of a Covered Foreign Person, such transactions may either be prohibited (Prohibited Transactions), or may obligate a US Person to notify Treasury of the transactions (Notifiable Transactions). US Persons may also have obligations with respect to non-US entities under their direction or control – either to prevent such non-US entities from engaging in certain transactions or filing notification of a Covered Transaction (discussed below) on their behalf.

    Covered Activities

    The OISP defines Covered Activities to include any of the activities that, if engaged in by a person of a Country of Concern, would make an investment in that person a Prohibited and Notifiable Transaction.

    Prohibited Transactions
    • Semiconductor and microelectronics sector: Prohibited Transactions in the semiconductor and microelectronics sector will include Covered Transactions in which the Covered Foreign Person:
      • Develops or produces design automation software for integrated circuits design or advanced packaging;
      • Develops or produces equipment for semiconductor fabrication, volume fabrication of integrated circuits, volume advanced packaging or extreme ultraviolet lithography;
      • Designs or fabricates integrated circuits that meet or exceed specified performance characteristics; and
      • Packages integrated circuits using advanced packaging techniques.
    • AI systems: Prohibited Transactions in the AI systems sector will include Covered Transactions in which the Covered Foreign Person:
      • Develops AI systems designed exclusively for or intended to be used for a military, government intelligence, or mass surveillance end use; and
      • Develops AI systems that are trained using a quantity of computing power greater than 10^25 computational operations, or 10^24 computational operations using primarily biological sequence data.
    • Quantum information technologies sector: Prohibited Transactions in the quantum information technologies sector will include Covered Transactions in which the Covered Foreign Person:
      • Develops, installs, sells, or produces supercomputers that exceed specified performance and density criteria;
      • Develops or produces a quantum computer or critical components required to produce a quantum computer;
      • Develops or produces a quantum sensing platform intended for military, government intelligence, or mass surveillance end uses; and
      • Develops or produces quantum networks or quantum communications systems intended to be used for scaling quantum computing, secure communications or any other application that has a military, government intelligence, or mass surveillance end use.
    Notifiable Transactions
    • Semiconductor and microelectronics sector: Notifiable Transactions in the semiconductor and microelectronics sector will include Covered Transactions in which the Covered Foreign Person designs, fabricates, and packages certain integrated circuits.
    • AI: Notifiable Transactions in the AI sector will include Covered Transactions in which the Covered Foreign Person develops an AI system that does not meet the criteria to make the transaction a Prohibited Transaction, but nevertheless is:
      • Designed to be used for a military end use, government intelligence, or mass surveillance end use;
      • Intended to be used for cybersecurity applications, digital forensic tools, penetration testing tools, or the control of robotic systems; or
      • Trained using computing power greater than 10^23 computational operations.
    • Quantum information technologies sector: There are no categories of Notifiable Transactions with respect to the quantum information technology sector.

    What we’re watching for: On February, 21, 2025, the Trump administration issued the America First Investment Policy Memorandum (Memorandum) signaling its intention to increase restrictions on US investments in China under “all necessary legal instruments,” including IEEPA, the Chinese Military-Industrial Complex Companies program administered under Executive Orders 13959 and 14032, as well as potentially expanding the scope of the OISP. The Memorandum signals the possibility of restricting investment in additional technology sectors of China’s economy, including biotechnology, hypersonics, aerospace, advanced manufacturing, directed energy, and other technologies critical to China’s national Military-Civil Fusion Strategy. Such investment restrictions on these additional technology sectors could be implemented through the OISP.

    Covered Foreign Persons

    A direct or indirect outbound investment by a US Person is not a Covered Transaction unless it involves (or may establish) a Covered Foreign Person. The OISP defines Covered Foreign Persons to mean:

    • A person of a Country of Concern (defined below) that is engaged in a Covered Activity;
    • A person that is not otherwise a Covered Foreign Person but:
      • Has, directly or indirectly, a voting or equity interest in, a board seat (voting or observer) on, or any contractual power to direct or cause the direction of management or policies of, a Covered Foreign Person; and
      • More than 50% of the person’s annual revenue, net income, capital expenditure, or operating expenses are attributable to Covered Foreign Persons, either individually or aggregated across all such Covered Foreign Persons from which the person derives or incurs (as applicable) at least $50,000 of the relevant metric.
    • With respect to a joint venture transaction that constitutes a Covered Transaction, a person of a Country of Concern that participates in such joint venture.

    A person of a Country of Concern includes nationals and permanent residents of a Country of Concern who are not also US citizens or permanent residents, entities with a principal place of business in, headquartered in, or incorporated in or otherwise organized under the laws of, a Country of Concern, governments of Countries of Concern and their political subdivisions, and entities in which any of the foregoing holds, individually or in the aggregate, directly or indirectly, at least 50% of the outstanding voting interest, voting power of the board, or equity interest.

    Covered Transactions

    The OISP applies to direct or indirect outbound investments by US Persons involving Covered Foreign Persons. Such Covered Transactions include certain direct or indirect acquisitions of equity interests (e.g., mergers and acquisitions, private equity and venture capital) and contingent equity interests, certain debt financing transactions, greenfield and brownfield investments, joint ventures and certain acquisitions of limited partner (LP) or LP-equivalent interests by US Persons in non-US Person investment funds. Covered Transactions may either be prohibited or require submitting notification to Treasury, depending on the nature of the specified technologies in which the investment target is involved (as outlined above). “Indirect” Covered Transactions include transactions where a US Person uses an intermediary, such as a special purpose vehicle, for the purpose of acquiring an equity interest in a Covered Foreign Person.

    Acquisition of LP or LP-Equivalent Interests in Non-US Pooled Funds

    Asset managers, both US and non-US, should take note that the acquisition of an LP interest by a US Person in a non-US venture capital fund, private equity fund, fund of fund, or other pooled investment fund (“Non-US Pooled Fund”) is a Covered Transaction only if (1) the US Person LP investor knows or has reason to know at the time of the acquisition that the Non-US Pooled Fund is likely to invest in a person of a Country of Concern who is engaged in the semiconductors and microelectronics, quantum information technologies, or AI sectors and (2) the Non-US Pooled Fund undertakes a transaction that would be a Covered Transaction if it were undertaken by a US Person.

    Notification Procedures

    Under the OISP, a US Person that engages in a Notifiable Transaction is required to submit an electronic notification to Treasury within 30 calendar days following the completion of the transaction. The notification must include certain specified information and be submitted through the Outbound Notification System (ONS) portal in accordance with the electronic filing instructions posted on Treasury’s Outbound Investment Security Program website.

    • Recordkeeping: The OISP requires US Persons to maintain a copy of the notification filed and supporting documentation for a period of ten years from the date of the filing. If the US Person does not provide Treasury with the required information, the OISP requires that they (1) provide a “sufficient explanation” for why the information is unavailable or otherwise cannot be obtained and (2) explain their efforts to obtain such information. If such information subsequently becomes available, the US Person must provide this information to Treasury promptly and no later than 30 calendar days following the availability of such information.
    • Confidentiality: The OISP generally prohibits Treasury from publicly disclosing information and documentary materials submitted by US Persons in connection with reporting Notifiable Transactions, with certain exceptions for disclosures pursuant to judicial or administrative proceedings and reports made to Congress or a government agency.
    • Parties responsible for submission: Treasury clarified in an FAQ that joint submissions by US persons are not permitted. Each US person participating in a Notifiable Transaction much submit a separate notice and certify to the accuracy of the information submitted.

    Knowledge Standard

    In order for a Covered Transaction to be subject to the OISP, the participating US Person must have knowledge at the time of the transaction that a “fact or circumstance exists or is substantially certain to occur, … [a]n awareness of a high probability of a fact or circumstance’s existence or future occurrence; or … [r]eason to know of a fact or circumstance’s existence,” with respect to the involvement of a Covered Foreign Person in the transaction, or that the transaction will result or is planned to result in the establishment of a Covered Foreign Person.

    Due diligence

    Under the OISP, a US Person is responsible for knowledge they had or could have had through a “reasonable and diligent inquiry” at the time of the transaction. Accordingly, US Persons should conduct, and document, appropriate due diligence on potential investment targets to ascertain whether the investment is a Covered Transaction. Factors that Treasury will consider in determining whether a reasonable and diligent inquiry was made at the time of the transaction, as outlined in the OISP, include:

    • Questions that the US Person asked of the investment target or other relevant transaction counterparty (e.g., a joint venturer) as of the time of the transaction;
    • Contractual representations or warranties that the US Person has obtained or attempted to obtain from the investment target or other relevant transaction counterparty with respect to the determination of the transaction’s status as a Covered Transaction and the status of the investment target or other relevant counterparty as a Covered Foreign Person;
    • Efforts by the US Person as of the time of the transaction to obtain and consider available non-public information relevant to the determination of a transaction’s status as a Covered Transaction and the status of an investment target or other relevant transaction counterparty as a Covered Foreign Person;
    • Available public information, the efforts undertaken by the US Person to obtain and consider such information, and the degree to which other information available to the US Person as of the time of the transaction is consistent or inconsistent with such publicly available information;
    • Whether the US Person purposefully avoided learning or seeking relevant information;
    • The presence or absence of warning signs, which may include evasive responses or non-responses from an investment target or other relevant transaction counterparty to questions or a refusal to provide information, contractual representations, or warranties; and
    • The use of available public and commercial databases to identify and verify relevant information of an investment target or other relevant transaction counterparty.

    Treasury notes that this is not an exhaustive list, and that its assessment of whether a US Person has undertaken a reasonable and diligent inquiry will ultimately depend on its consideration of the totality of the circumstances. In these cases, obtaining representations and warranties from the investment target relevant to the transaction’s status as a Covered Transaction may, in the absence of other warning signs, provide an indication that a US Person lacked the requisite knowledge to make the OISP applicable; however, doing so does not serve as a safe harbor. Accordingly, US Persons should be wary of any warning signs indicating that an investment target’s responses to diligence questions are potentially incomplete, inaccurate, or untruthful.

    What we’re watching for: Treasury declined to create a “list” of Covered Foreign Persons or to prescribe specific due diligence obligations, creating difficulties for firms trying to determine what the appropriate level of diligence is for a given transaction. Further, as Treasury also acknowledges, limited publicly available information regarding some China-related companies may also make this inquiry challenging. To this end, service providers may begin to provide aggregated data on potential Covered Foreign Persons, especially in the absence of a published list of such persons by Treasury. If such services become available, asset managers may consider whether utilizing them will enhance their diligence procedures but should not necessarily disregard taking other appropriate measures.

    Excepted Transactions

    The OISP establishes conditions under which an otherwise Covered Transaction will not be considered a Notifiable or Prohibited Transaction (Excepted Transactions). Subject to certain qualifications, Excepted Transactions include:

    • An investment by a US Person in publicly traded securities (as “security” is defined under Section 3(a)(10) of the Securities Exchange Act), denominated in any currency, that trades on a US or non-US securities exchange or “over-the-counter” in any jurisdiction;
    • An investment by a US Person in a security issued by a registered investment company (e.g., index fund, mutual fund, exchange-traded fund) or issued by any company that has elected to be a business development company;
    • Certain LP or equivalent investments by a US Person in a venture capital fund, private equity fund, fund of funds or other pooled investment fund, provided that either (1) the LP or equivalent’s committed capital is not more than $2,000,000, aggregated across any investment and co-investment vehicles of the fund or (2) the LP or equivalent has secured a binding contractual assurance that its capital in the pooled investment fund will not be used to engage in a transaction that would be a Prohibited or Notifiable Transaction if engaged in by a US Person;
    • Certain investments by US Persons in derivatives, provided that such investment does not confer the right to acquire equity, any rights associated with equity, or any assets in or of a Covered Foreign Person;
    • A US Person’s full buyout of all interests of any person of a country of concern in an entity, such that the entity is not a Covered Foreign Person following the transaction;
    • An intracompany transaction between a US Person Parent and its Controlled Foreign Entity that supports new operations that are not Covered Activities or that maintains ongoing operations, including ongoing Covered Activities;
    • Fulfillment of a US Person’s binding, uncalled capital commitment entered into prior to the effective date of the OISP (Jan. 2, 2025);
    • The acquisition of a voting interest in a Covered Foreign Person upon default or other condition involving a loan, where the loan was made by a lending syndicate and a US Person participated passively in the syndicate;
    • The receipt of employment compensation by an individual in the form of stock or stock options, or the exercise of such options; and
    • Certain transactions with or involving a non-US Person or entity that have been designated by the Secretary of the Treasury in accordance with certain criteria (yet to be developed) that relate to the foreign country or territory’s own measures to address the national security risk related to a particular outbound investment.

    Importantly, even if a transaction falls within the above categories, it is not an Excepted Transaction if the transaction would give a US Person rights with respect to a Covered Foreign Person that are “beyond standard minority shareholder protections.” For example, Treasury describes the ability to nominate and put forward for a vote a slate of directors as a positive right that “goes beyond just protecting the investment of [minority shareholders].” Accordingly, in Treasury’s view, acquiring a sufficient stake in a publicly traded company that would entitle a US investor to nominate directors is likely not an Excepted Transaction. Of note, in certain jurisdictions, ownership of voting securities above very low thresholds confers the investor with rights beyond “standard minority shareholder protections,” such as the right to propose a shareholder vote or nominate directors (e.g., above 1% of the issuer’s shares under the Chinese Companies Act, and above 1% under Taiwan Stock Exchange rules). Asset managers may look to rely on the publicly traded securities exception when considering investments in China, but it is important keep these low thresholds in mind when monitoring trading activity for OISP compliance.

    Asset managers should also keep in mind that Treasury has stated that with respect to initial public offerings (IPOs), pre-IPO transactions involving the acquisition of equity in a Covered Foreign Person “such as a purchase with the intent to create a market for the security or to resell the security on a secondary market” are Covered Transactions, because the equity interest is not yet publicly traded. But the exception might still apply if the pre-IPO exposure is through a swap rather than cash (i.e., no actual ownership of shares).

    What we’re seeing: Many LPs are seeking representations from asset managers that their capital will not be used to engage in prohibited transactions or notifiable transactions, to take advantage of the exception for LP investments. When faced with such requests, asset managers should carefully consider the implications of agreeing to limitations on a fund’s ability to engage in notifiable transactions and measures needed to isolate US LPs from Covered Transactions. Further, should Treasury expand the OISP to additional technology sectors, such representations may become more restrictive than anticipated. Asset managers may also consider less restrictive counterproposals, such as only representing that a fund will not engage in prohibited transactions and will provide notice to an LP if the fund engages in a notifiable transaction.

    What we’re watching for: The America First Investment Policy Memorandum contemplates further review of, and potentially expanded restrictions on, “outbound private equity investments, venture capital investments, greenfield investments, corporate expansions, and investments in publicly traded securities from sources including pension funds, university endowments, and other limited-partner investors.” It is possible, therefore, that the Trump administration may narrow the OISP exceptions, including the publicly traded securities exception.

    Obligations under the OISP

    US Persons

    The OISP applies to all “US Persons,” which means “any United States citizen, lawful permanent resident, entity organized under the laws of the United States or any jurisdiction within the United States, including any foreign branch of any such entity, or any person in the United States. Non-US asset managers should be aware that the OISP can impact foreign entities that employ US Persons, as well as foreign entities with non-US Person employees who engage in Covered Activities while they are physically located in the US (e.g., during international business travel). Accordingly, non-US asset managers should consider implementing policies for any US Person personnel with investment decision-making authority to recuse themselves from Covered Transactions and monitor the geographic location of all personnel engaged in Covered Transactions.

    Controlled Foreign Entities

    The OISP also imposes obligations on US Persons with respect to foreign entities that they control (Controlled Foreign Entities). A Controlled Foreign Entity means “any entity incorporated in or otherwise organized under the laws of a country other than the United States of which a US Person is a parent.” The OISP further defines “parent” to mean a person that directly or indirectly holds more than 50% of the outstanding voting interest in an entity or of the board of the entity; a general partner, managing member or equivalent of an entity; or an investment adviser (as defined in the Investment Advisers Act of 1940) to any entity that is a pooled investment fund (Parent).

    Under the OISP, US Persons must take “all reasonable steps to prohibit and prevent” a Controlled Foreign Entity from engaging in a Prohibited Transaction and file a notification to Treasury for any Notifiable Transaction undertaken by a Controlled Foreign Entity no later than 30 calendar days after the completion date of the Notifiable Transaction. The OISP outlines a non-exhaustive list of factors that Treasury will consider in determining whether a US Person took “all reasonable steps to prohibit and prevent” a Controlled Foreign Entity from engaging in a Prohibited Transaction, such as whether agreements to implement training and internal reporting between the US Person Parent and the Controlled Foreign Entity to ensure compliance with the OISP were executed, the implementation, auditing, and testing of appropriate controls, policies and procedures, as well whether such steps were “intended to be effective and … were adequately resourced,” among other factors.

    Knowingly Directing an Otherwise Prohibited Transaction

    The OISP also prohibits US Persons from “knowingly directing” a transaction by a foreign entity that the US Person knows at the time of the transaction would be prohibited if the transaction were engaged in by a US Person. The OISP clarifies that the “knowingly directing” provision only applies to a US Person that “has authority, individually or as part of a group, to make or substantially participate in decisions on behalf of a non-US Person, and exercises that authority to direct, order, decide upon or approve a transaction” (“Management Personnel”). Treasury also notes that the “knowingly directing” provision applies not just to individuals, but also to US entities with such authority.

    In its FAQs, Treasury explains that a corporate officer who is a member of an investment committee that votes on whether to undertake potential investments has the requisite authority to knowingly direct an otherwise Prohibited Transaction and meets the definition of Management Personnel, while an accountant who conducts financial due diligence on a potential investment at the instruction of corporate management does not. Additionally, a bank that transfers funds on behalf of a third party to effectuate that third party’s Covered Transaction, without more, has not engaged in a Covered Transaction or “knowingly directed” such a transaction.

    Recusal carve-out

    US Persons employed as Management Personnel at foreign entities who fully recuse themselves from the following activities in connection with a Prohibited Transaction will not be determined to have “knowingly directed” that transaction:

    • Participating in formal approval and decision-making processes related to the transaction, including making a recommendation;
    • Reviewing, editing, commenting on, approving, and signing relevant transaction documents; and
    • Engaging in negotiations with the investment target or, as applicable, the relevant transaction counterparty.

    In order to successfully invoke the recusal carve-out, the US Person must “immediately cease” involvement in any of the above activities “prior to” the foreign entity approving and engaging in the Prohibited Transaction. Notably, the “knowingly directing” provision of the OISP captures US Person Management Personnel of foreign entities (e.g., non-US asset managers), wherever located. As such, to avoid violating the OISP, US Person Management Personnel must fully recuse themselves from any involvement in the foreign entity’s decisions relating to such a transaction.

    National interest exemption

    The Final Rule does not establish a licensing regime for US Persons to engage in Prohibited or Notifiable Transactions. However, the OISP provides an exemption for an otherwise Covered Transaction if the US Person seeking to engage in the transaction can demonstrate that the Covered Transaction is in the national interest. In determining whether a transaction qualifies under the national interest exemption, Treasury, in consultation with other agencies, will consider, among other factors:

    • The transaction’s effect on critical US supply chain needs;
    • Domestic production needs in the US for projected national defense requirements;
    • US’s technological leadership globally in areas affecting US national security; and
    • The impact on US national security if the US Person is prohibited from undertaking the transaction.
    Enforcement

    The OISP makes it a violation to take any action prohibited by the OISP; fail to take any action that the OISP requires within the time frame and manner specified in the OISP; make any materially false or misleading representation, statement or certification, including falsifying, concealing or omitting any material fact when submitting information required by the OISP; or to conspire to violate the OISP or taking any action that evades or avoids, has the purpose of evading or avoiding, causes a violation of, or attempts to violate, the OISP.

    Violations of the OISP can give rise to civil and criminal penalties under the International Emergency Economic Powers Act (IEEPA), including a maximum civil penalty of up to (a) twice the amount of the transaction that is the basis for the violation or (b) approximately $368,000 (adjusted annually for inflation), whichever is greater; and, for willful violations, a criminal fine of up to $1 million, a prison sentence of up to 20 years, or both.

    Further, the OISP provides that Treasury may take any action authorized by IEEPA to nullify, void, or compel the divestment of a Prohibited Transaction that was entered into after the OISP’s effective date (January 2, 2025).

    What we’re watching for: Treasury has reportedly been contacting various US entities to inquire about transactions that may implicate the OISP. However, Treasury has not publicized any enforcement actions or settlements thus far, so it remains to be seen how Treasury will interpret some of the OISP’s ambiguities in an enforcement context.

    Authors

    Gregoire P. Devaney

    Associate

    New York – 919 Third Avenue

    Melissa G.R. Goldstein

    Partner

    New York – 919 Third Avenue

    Mathew R. Swan

    Associate

    New York – 919 Third Avenue

    More insights

  • Inside HPE Europe 2025 | The future of life sciences investment

    Inside HPE Europe 2025 | The future of life sciences investment

    ARTICLE

    Inside HPE Europe 2025 | The future of life sciences investment

    November 2025

    Read time: 5 min

    Overview

    European life sciences businesses have been closely tracking geopolitics and global policy changes over the past 12 months, particularly as the new administration in the United States heightens its focus on drug pricing.

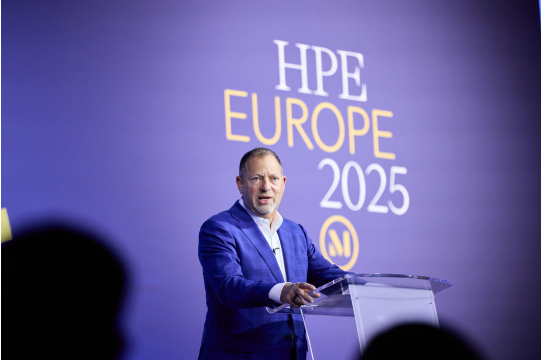
    Against this backdrop, hundreds of healthcare professionals, investors, and industry changemakers gathered in London for McDermott Will & Schulte’s annual HPE Europe conference, held September 25, 2025. Our keynote speakers, hosts of the hit UK podcast The Rest is Money Steph McGovern and Robert Peston, outlined macro trends impacting the markets, kicking off lively discussions about private equity investment in European life sciences and the opportunities on offer today and leading into 2026.

    In depth

    The current policy environment featured heavily in these discussions. The US accounts for more than half of the total global demand for prescription drugs, so the latest US policy developments have ramifications for European manufacturing and research and development (R&D) pipelines. US President Donald Trump has long prioritised efforts to reduce prescription drug prices for Americans. In his first administration, he proposed a most favoured nation (MFN) policy that would effectively link US prices to the lowest prices paid for the same drugs in other developed markets. The US courts ultimately overturned the policy, but a May 2025 executive order revived the issue, stating that US consumers must have access to MFN prices for drugs.

    Since then, the US government has sent warning letters to at least 17 major pharmaceutical companies directing them to decrease prices in the US or face aggressive action. Meanwhile, the Inflation Reduction Act of 2022’s prescription drug pricing provisions also take effect in January 2026, which will further limit prices for drugs in the US.

    “For European life sciences businesses, there are many unknowns in relation to MFN and tariffs on pharmaceuticals. The United Kingdom is a smaller market for global pharmaceuticals, but it has also increased the rebate that pharma companies have to pay on sales to the NHS above a certain threshold, raising further concerns about unpredictability of policy.” – Sharon Lamb, Head of the UK Healthcare Practice Group, McDermott Will & Schulte

    This policy uncertainty impacted dealmaking in the first half of 2025. Some investors pressed pause on proposed transactions, and many companies revisited their global pricing policies and cost dynamics. Looking ahead, certain pharma companies likely will adjust manufacturing supply chains to start building closer to target markets, and deal activity likely will pick up going into 2026 as businesses coalesce around new strategic priorities.

    China prioritises biotech innovation

    The past year has witnessed a boom in Chinese biotech innovation, which often outperforms developments in the US and Europe – and at cheaper prices. As a result, global competition remains intense.

    Chinese government policy combined with substantial R&D investment has yielded a robust pipeline of novel drugs at low prices, particularly in oncology and cell therapy. Many European businesses are looking to China as a source of innovation because its reduced drug development timelines and strong ecosystem of biotechs and contract research organisations provide an ideal environment for prolific molecular development.

    Chinese innovation could ultimately help reduce drug development costs, but it currently places additional competitive pressure on European businesses.

    A burgeoning European opportunity

    Despite these pressures, a strong cohort of life sciences companies is emerging out of Europe. Investors are heavily focused on rare disease treatments and pharma services that support such treatments, given such drugs have a relatively low impact on government budgets, benefit from strong patient populations, and may be less vulnerable to uncertainty over tariffs and pricing.

    Investors are also interested in cardiometabolic diseases, innovations in oncology, and neuroscience, which continues to deliver a rich pipeline. Immunology and inflammation, and particularly autoimmune disorders such as lupus, also are seeing meaningful early-stage investment and present interesting investment theses.

    Given constraints on budgets and the pace of Chinese innovation, European investors are increasingly turning to biosimilars and generics, along with pharma services companies that support generics.

    What’s next?

    As in many markets around the world, European life sciences businesses and their funders are investigating how artificial intelligence (AI) can enhance drug development. While AI’s full potential to transform drug discovery and create new investment opportunities is yet to be realised, industry participants are already deploying AI to enhance end-to-end data flows and make patient recruitment more efficient. The next tranche of use cases looks set to prioritise reducing the costs and increasing the speed of clinical trials.

    At the confluence of business model disruption and technology-driven efficiencies, investors are optimistic about opportunities moving forward. As a means of derisking in today’s climate of uncertainty, many European life sciences companies are prioritising portfolio diversification, which in turn opens up new avenues for growth.

    “Diversification has led to increasing licensing and collaboration deals across the life sciences sector. Innovation in life sciences often originates in biotech labs or academic spin-offs that lack the capacity to bring products to market. As these companies turn to external partners to develop promising assets and scale innovation, strategic alliances are becoming central to healthcare’s future and creating new opportunities for savvy investors.” – Sharon Lamb, Head of the UK Healthcare Practice Group, McDermott Will & Schulte

    This year may have brought challenges from a policy perspective, but as the dust settles, attendees at HPE Europe 2025 were optimistic about the months ahead.

    Authors

    Sharon Lamb

    Partner

    London – 22 Bishopsgate

    More insights

  • AdvaMed modernizes its code of ethics for the digital era

    AdvaMed modernizes its code of ethics for the digital era

    ARTICLE / CLIENT ALERT

    AdvaMed modernizes its code of ethics for the digital era

    October 31, 2025

    Read time: 4 min

    Key takeaways
    Overview

    The Advanced Medical Technology Association (AdvaMed) announced its updated Code of Ethics on Interactions with US Health Care Professionals on October 6, 2025. The medical technology industry has relied on the AdvaMed code for decades to assist in navigating complex rules concerning compliance. This version builds upon the June 2023 version and extends guidance for data-driven technologies and issues such as cybersecurity and ethical data management. AdvaMed recognized in its announcement that, as medical technology companies increasingly rely on data to improve patient outcomes, regulators and stakeholders are demanding stronger safeguards. AdvaMed stated that its 2025 revisions aim to ensure companies manage data transparently and in line with global best practices. The 2025 code will take effect on November 1, 2025.

    In depth

    Relationships between medical technology companies and healthcare professionals can help advance development of medical technologies, promote their safe and effective use, and foster medical research and education. These relationships can also create risk under state and federal laws, such as the federal Anti-Kickback Statute. AdvaMed, a medical technology trade association, originally developed a set of voluntary guidelines for its members to use in structuring their interactions with healthcare professionals. The code was created in 1993 and is revised periodically, with updates increasing in frequency in the past five years.

    While the code remains labeled a voluntary set of guidelines, AdvaMed requires its member companies to abide by the code. Certain states, including California, Connecticut, and Nevada, have made the code’s provisions mandatory. Disclosure databases and reporting requirements also have been created under the federal Sunshine Act and in California, Massachusetts, and Vermont. As the industry is well aware, whistleblowers and the government may attempt to argue that code noncompliance is evidence of improper intent in connection with allegations of federal Anti-Kickback Statute violations.

    The most significant change to the code is the addition of a section titled “Data-Driven Technologies.” This new section reflects AdvaMed’s recognition of the growing role of digital health and data analytics in medical technology. It introduces a framework for ethical data use and governance, outlining the following principles entities should follow:

    Principles of trust

    • Use data for the benefit of patients – to improve access and outcomes; to advance research, development, and safety goals; and to benefit the healthcare ecosystem at large.
    • Minimize personal data, as appropriate, to protect individuals’ privacy and prevent inappropriate identification of specific individuals.
    • Use data for the purposes articulated to individuals or authorized by customers.

    Principles of privacy, transparency, consent, and control

    • Protect patient privacy in compliance with industry best practices and international standards where applicable.
    • Personal data and the systems that process it are protected through appropriate organizational security measures designed to preserve confidentiality, integrity, and availability.
    • Collect data transparently with appropriate notice and permission.
    • Individuals have appropriate control over their personal data.

    Principles of responsibility in data management

    • Manage personal data in accordance with appropriate medical technologies standards of ethics and trustworthiness.
    • Healthcare stakeholders, innovator personnel, and external vendors collaborate to deliver a clear understanding of the data that is collected, how it is used, and how it is protected.
    • Manage data in accordance with requirements of healthcare stakeholders where applicable.
    • Deploy appropriate technology to protect data and continuously improve systems and processes, and train teams in relevant aspects of data protection and cybersecurity to maintain a consistently high level of threat awareness.

    Next steps

    Medical technology companies and healthcare professionals should consider whether the 2025 code warrants updates to their compliance policies and procedures. The 2025 code provides helpful guideposts but does not override laws, regulations, or other governing codes that may be in effect. Stakeholders should keep this in mind as they consider their policies and procedures in light of the recent 2025 code revisions.

    We will continue to monitor how the 2025 code updates impact the industry. If you have any questions about the revised 2025 code or how it may impact your compliance policies and procedures, please contact one of the authors of this article or a member of the firm’s Health & Life Sciences Group.

    Authors

    James A. Cannatti III

    Partner

    Washington, DC

    Paul S. Gadiock

    Partner

    San Francisco

    Daniel F. Gottlieb

    Partner

    Chicago

    Tony Maida

    Partner

    New York – One Vanderbilt Avenue

    James R. Ravitz

    Partner

    Washington, DC

    Marissa Hill Daley

    Law Clerk

    Washington, DC

    More insights

  • When patent law meets free speech: Anti-SLAPP appellate jurisdiction

    When patent law meets free speech: Anti-SLAPP appellate jurisdiction

    ARTICLE

    When patent law meets free speech: Anti-SLAPP appellate jurisdiction

    Oct 30, 2025

    Read time: 4 min

    Key takeaways
    Overview

    The US Court of Appeals for the Federal Circuit determined that it had jurisdiction over an interlocutory appeal from a district court’s denial of a California anti-SLAPP (Strategic Lawsuit Against Public Participation) motion in a trade secret and inventorship case, finding such a denial was immediately appealable under the collateral order doctrine. On the merits, the Federal Circuit vacated and remanded the district court’s decision. IQE, plc v. Newport Fab, LLC, DBA Jazz Semiconductor, et al., Case No. 24-1124 (Fed. Cir. Oct. 15, 2025) (Hughes, Stark, Wang, JJ.)

    IQE sued Jazz Semiconductor, Tower Semiconductor, and other entities and individuals (collectively, Tower) for violation of the Defend Trade Secrets Act, correction of inventorship under 35 U.S.C. § 256, and five claims arising under California state law, including trade secret misappropriation and intentional interference with prospective economic advantage. Tower moved to dismiss for failure to state a claim and simultaneously filed an anti-SLAPP motion to strike the claims for misappropriation and intentional interference arising under state law. The district court denied Tower’s motion to strike. Tower appealed to the US Court of Appeals for the Ninth Circuit.

    The Ninth Circuit determined that under 28 U.S.C. § 1295(a) the Federal Circuit would have had jurisdiction at the time the appeal was filed. The Ninth Circuit explained that the Federal Circuit had subject matter jurisdiction over the appeal because the complaint asserted a claim for correction of inventorship, a cause of action arising under federal patent law. The Ninth Circuit further concluded that the Federal Circuit had appellate jurisdiction under Ninth Circuit law since the denial of an anti-SLAPP motion is an immediately appealable order under the collateral order doctrine. The Ninth Circuit therefore transferred the appeal to the Federal Circuit.

    The Federal Circuit noted that the appeal raised a jurisdictional question of first impression: whether the Federal Circuit has jurisdiction over an appeal from a district court’s denial of an anti-SLAPP motion before entry of final judgment. The Federal Circuit agreed with the Ninth Circuit that it has subject matter jurisdiction over claims created by federal patent law. The Federal Circuit noted that appellate jurisdiction typically is limited to a final decision by the district court, but the collateral order doctrine provides a narrow exception that allows an interlocutory appeal when a trial court’s order affects rights that will be irretrievably lost in the absence of an immediate appeal. The Court analyzed the three collateral order factors and determined that an anti-SLAPP motion to strike under California law fits squarely within the collateral order exception to the final judgment rule.

    IQE argued that jurisdiction was improper for two reasons:

    • IQE filed an amended complaint after Tower’s appeal, suggesting the district court must revisit the motion.
    • Some circuits have held that state anti-SLAPP statutes conflict with the Federal Rules of Civil Procedure.

    The Federal Circuit rejected both arguments, finding the amended complaint improper under Ninth Circuit precedent and deferring to the Ninth Circuit’s view that California’s anti-SLAPP law applies in federal court. The Federal Circuit limited its holding to California’s anti-SLAPP statute, explaining that whether denials of anti-SLAPP motions from other states are immediately appealable must be evaluated case-by-case under the collateral order doctrine.

    Having determined that it had jurisdiction over the appeal, the Federal Circuit proceeded to the merits and held that the district court erred in denying Tower’s anti-SLAPP motion to strike at step one of the analysis. Because interpretation of California’s anti-SLAPP statute is not unique to patent law, the Federal Circuit applied Ninth Circuit law, which reviews denials of anti-SLAPP motions de novo and follows the California Supreme Court’s broad construction of the statute. Under California’s anti-SLAPP framework, courts engage in a two-step inquiry:

    • The defendant must show that the challenged claim arises from an act in furtherance of the defendant’s right of petition or free speech.
    • If the defendant successfully does so, the burden shifts to the plaintiff to demonstrate a probability of prevailing on the claim.

    Applying this framework and guided by the California and Ninth Circuit authorities emphasizing the statute’s broad scope, the Federal Circuit concluded that the district court misapplied step one of the anti-SLAPP analysis.

    Authors

    Jodi Benassi

    Partner

    San Francisco

    More insights
    Endnotes

  • IRS roundup: October 7 – October 23, 2025

    IRS roundup: October 7 – October 23, 2025

    ARTICLE

    IRS roundup: October 7 – October 23, 2025

    Oct 28, 2025

    Read time: 3 min

    Check out our summary of significant Internal Revenue Service (IRS) guidance and relevant tax matters for October 7, 2025 – October 23, 2025.

    October 7, 2025: The IRS issued Notice 2025-55, providing guidance on relief from failure to deposit penalties under Internal Revenue Code (Code) Section 6656 as it relates to a new excise tax being imposed on particular remittance transfers under Section 4475 for the first three quarters of 2026. The notice also includes guidance on the deposit safe harbor under Treas. Reg. § 40.6302(c)-1(b)(2), explaining that a remittance transfer provider will not be affected by failure to make deposits of the remittance transfer tax if they satisfy certain requirements.

    October 16, 2025: The IRS issued Revenue Ruling 2025-21, providing various prescribed rates (for federal income tax purposes) for November 2025, including:

    • The short-, mid-, and long-term applicable federal rates (AFRs) for November 2025 as it relates to Section 1274(d).
    • The short-, mid-, and long-term adjusted AFRs for November 2025 as it relates to Section 1288(b).
    • The adjusted federal long-term rate and the long-term tax-exempt rate described in Section 382(f).

    October 17, 2025: The IRS issued Revenue Procedure 2025-32, modifying certain sections of Revenue Procedure 2024-40 to reflect amendments resulting from the One Big Beautiful Bill Act (OBBBA). Revenue Procedure 2024-40, which displays IRS inflation-adjusted items for 2025, was specifically revised by removing the existing sections on standard deductions and the election to expense certain depreciable assets. Revenue Procedure 2025-32 also describes inflation-adjusted items for 2026 for various Code provisions.

    October 21, 2025: The IRS issued Notice 2025-57, providing guidance on returns related to certain interest on specified passenger vehicle loans received in a trade or business from individuals, which are required to be filed under the new Section 6050AA as enacted in the OBBBA. Recognizing the need for efficient administration of Section 6050AA, Section 3 of Notice 2025-57 provides a means for interest recipients to report obligations under Section 6050AA.

    October 22, 2025: The IRS issued frequently asked questions (FAQs) addressing Employee Retention Credits (ERC) under the ERC compliance provisions of the OBBBA. Although not final guidance, “a taxpayer who reasonably and in good faith relies on these FAQs will not be subject to a penalty that provides a reasonable cause standard for relief, including a negligence penalty or other accuracy-related penalty, to the extent that reliance results in an underpayment of tax.”

    October 23, 2025: The IRS issued Notice 2025-63, announcing the US Department of the Treasury and IRS’s intentions to issue proposed regulations providing that certain borrow fees are sourced based on the recipient’s residence. Currently, neither the Code nor Treasury regulations specify how to determine borrow fees as they relate to securities lending transactions and sale-repurchase transactions. Thus, the Treasury and the IRS intend to clarify this in Notice 2025-63.

    The IRS also released its weekly list of written determinations (e.g., Private Letter Rulings, Technical Advice Memorandums, and Chief Counsel Advice).

    In depth
    Authors

    Evan Walters

    Partner

    Chicago

    Edward L. Froelich

    Counsel

    Washington, DC

    Michael J. Scarduzio

    Partner

    New York – One Vanderbilt Avenue

    Samuel F. Hamer

    Associate

    Washington, DC

    More insights
    Endnotes