













ARTICLE
Inside HPE Europe 2025 | Accelerating value creation: Mastering performance optimization for exit success
October 2025
Read time: 4 min
HPE Europe convened more than 300 top-tier investors, executive management teams, investment bankers, and lenders. Our in-depth panels explored the future of the industry and the critical trends shaping deal activity for the year ahead.
During our session on “Accelerating value creation” we discussed how, in a market that’s finally warming up, value creation that actually prices is grounded in facts, not fanfare. Healthcare sellers who show a defendable “new normal,” tie KPIs to cash, and pick the right exit track, from GP-leds to well-timed trade sales, are getting deals done. The playbook now is disciplined underwriting, credible internationalisation (often US traction), and evidence over anecdotes.
Our expert panel was moderated by partners Kristian Werling and Eleanor West who spoke with Christian Fellowes, Managing Director of Inflexion and Matthew Norton, General Partner at Ampersand Capital.
So what did you miss?
1) Exit windows are reopening – but discipline wins.
After a muted few years, deal flow is building as macro conditions stabilise and rate cuts begin to feed through. That said, buyers remain choosy. The cost of capital has reset and underwriting is tighter, so sellers need to evidence resilient, repeatable cash generation rather than rely on multiple expansion alone.
2) Prove the “new normal” with data, not narrative.
Healthcare experienced a longer tail of post-pandemic volatility than many sectors, making it harder to define a defendable base EBITDA. The solution is rigorous exit readiness: a crisp equity story, KPIs that align to that story, and a fact base that ties operational drivers to financial outcomes. If it isn’t measured and tracked, it won’t price.
“You only need one outlier to do the deal… we’re seeing instances of very eye-watering numbers being paid—great for the vendor, good luck to the buyer.” – Christian Fellowes, Manager Director, Inflexion
3) Deployment pressure ≠ valuation floor.
Funds need to return capital, and they also need to deploy. That tension is unclogging processes, and in some cases producing “outlier” bids from teams under deployment pressure. Sellers should welcome that dynamic, but not mistake isolated bids for a new market clearing level. Credible processes still clear only where value is supported by evidence.
4) The fourth exit track is now mainstream.
GP-led secondaries/continuation vehicles have evolved from end-of-life clean-ups into a strategic tool: providing DPI to existing LPs, fresh capital to proven assets, and time to finish multi-year value plans (e.g., completing pipelines, scaling in the United States, or finishing systems/people upgrades). They’re powerful, if used judiciously. Governance, price validation and positioning matter to avoid the perception of “keeping the winners and selling the rest.”
“Higher rates require greater confidence in valuations – more expensive capital at the outset means less room for error to hit LP return targets.” – Kristian Werling, Partner, McDermott Will & Schulte
5) Internationalisation, especially a credible US angle, expands the buyer pool.
For many healthcare platforms, demonstrating traction in the United States or other priority geographies is a value lever in its own right. Local presence, regulatory navigation, and commercial proof points de-risk the story and broaden strategic demand at exit.
6) Strategics require earlier, sharper preparation. IPOs remain the exception.
Selling to private equity is process-driven; selling to trade is calendar-driven. The logical buyer set may be small and on its own timetable, so preparation starts at day one. IPOs can be a good home for the right asset but remain capital-intensive, slower to monetise, and not the default path.
“Fortune-scale corporates buying now means shareholder pressure to divest later — the cycle comes back to carve-outs.”” – Eleanor West, Partner, McDermott Will & Schulte
Bottom line: Value creation that prices today looks like this – measure what matters, lock in operational proof, and choose the exit path (including GP-led options) that best matches the maturity of the plan and the breadth of the buyer universe.





HPE NYC 2025: Inside the healthcare dealmaking outlook
ARTICLE
HPE NYC 2025: Inside the healthcare dealmaking outlook
October 16, 2025
Read time: 5 min
On October 16, global law firm McDermott Will & Schulte showcased its premier series for healthcare dealmakers in the heart of New York City.
Held at The Glasshouse, Healthcare Private Equity (HPE) NYC 2025 brought together hundreds of industry players for a dynamic series of engaging panels and networking opportunities. Sessions offered insights and forward-looking perspectives on various topics, including the current state of the market, the increasing role of AI in healthcare, and healthcare industry opportunities.
McKinsey & Company, the official knowledge partner of HPE NYC, shared an analysis of emerging trends across the industry at the event. Here, McKinsey and McDermott Will & Schulte share some of the takeaways from the event.

Perspectives on the current deal environment
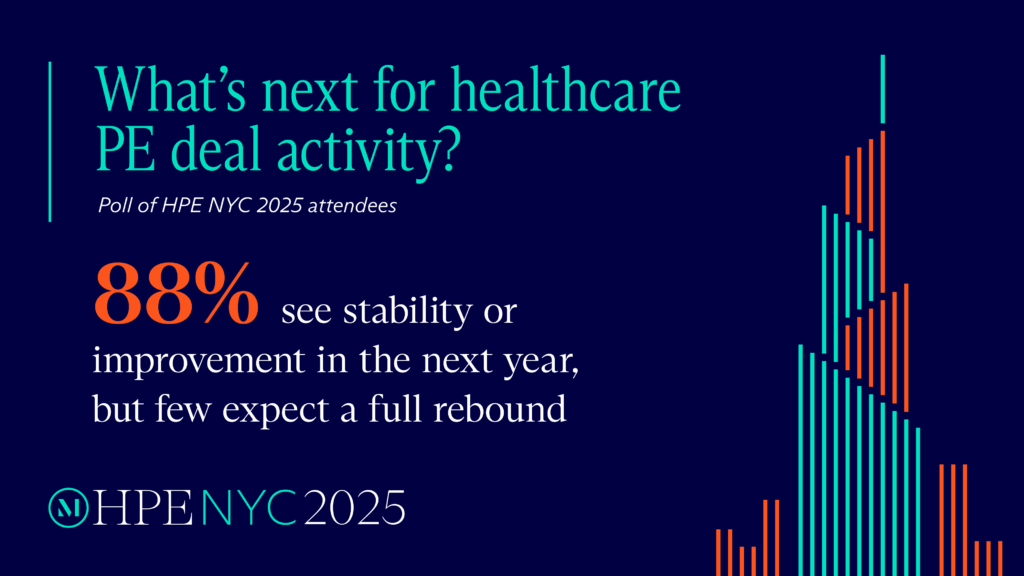
- Market activity. Participants expressed mixed-optimism at HPE NYC. Forty-six percent of attendees polled believed deal activity would be “about the same” over the next 12 months, while 42% believed it will improve. Panelists leaned more optimistic as they pointed to growing market activity over the last year and an increase in the deal pipeline through 2025.
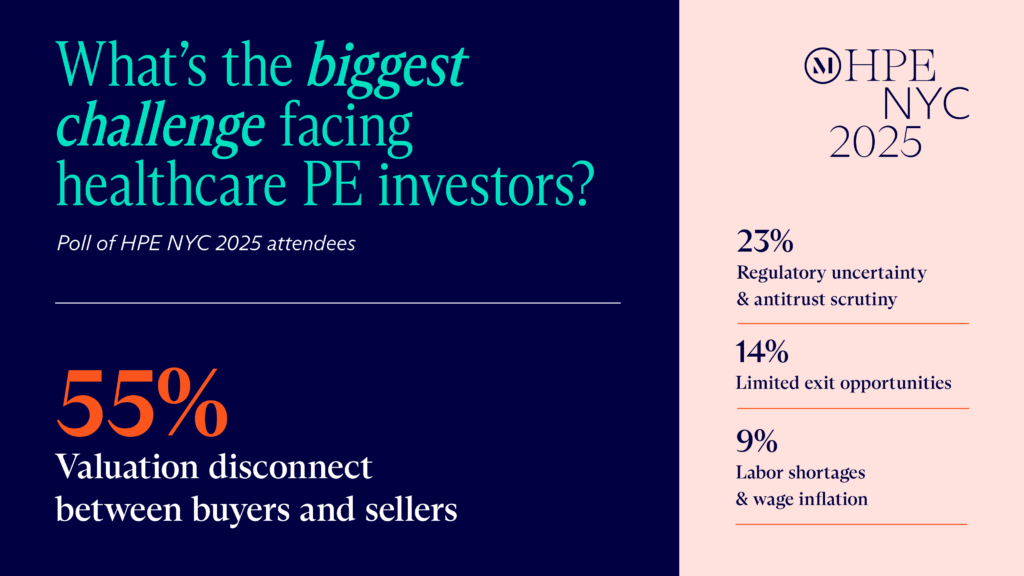
- Obstacles to healthcare PE transactions. Both panelists and attendees identified the lingering buyer-seller valuation gap as a major barrier facing Healthcare PE investors; 55% of attendees pointed to that valuation disconnect as the biggest challenge to successful deal executions. According to panelists, the gap is more pronounced in sectors where the lack of recent trades has made it particularly difficult for buyers and sellers to agree on valuations.
- Pharmaceuticals. Panelists addressed concerns over margin erosion and possible disruptions to pharmaceutical accessibility. The pharmaceutical industry is adjusting to potential changes in patient access to drugs, including a push to direct-to-consumer channels. That movement has begun and continues to trend.
“We are optimistic about healthcare in the current market, where deals are getting done. We are seeing quite a bit of deal flow in the third and fourth quarters of 2025 and look forward to continued market activity into next year.” – Ira Coleman, chairman of McDermott Will & Schulte
Emergence of AI in the healthcare space
- Change management is key. Panelists emphasized the need for a strategic approach to AI. Technology alone is insufficient; leadership buy-in and acumen at portfolio companies is essential for AI to positively impact the healthcare industry. The overall sentiment was that companies must be ready and capable of integrating and adopting AI tools to ensure effective adaptation.
- Seeing efficiency gains. AI is still in the early stages of adoption through most of the industry. Gains are mostly seen today in the back office, but the pressure on healthcare businesses to improve patient outcomes and lower costs will lead to more use of technology and AI in the future.
- Clinical applications. As of now, panelists noted limited applications for AI in clinical settings. At least one panelist, however, noted that we are starting to see early use in some specialties, highlighting how some studies have shown the potential of AI in detecting pre-cancerous legions in digital dermoscopic images, for example.
Ongoing trends in the healthcare private equity market
- Rural healthcare. Industry leaders addressed the potential of rural health as a catalyst for innovation and value creation. As states with rural populations show growing interest in private-sector partnerships, speakers noted that many are exploring tech-enabled care delivery models and financial structures that balance costs across care sites — using stronger-performing services to support those with thinner margins.
- Physician practice management (PPM’s). Panelists highlighted the potential for PPM’s to reenter the market, especially with a focus on de novos rather than roll-ups. The adoption of more tech-enabled services by PPM’s could also drive margin improvements.
- Creative deals. Industry leaders stressed a shift toward more complex structuring of today’s deals, with creative earnouts and innovative arrangements becoming increasingly common. At the same time, speakers noted that private credit is taking on a growing role in financing healthcare deals, bringing higher costs of capital and a focus on alpha creation. There was also discussion about partnering with payers and providers to develop innovative capital deployment strategies that solve key challenges for large strategics and mitigate downside risk.
Conclusion
HPE NYC 2025’s lively and thought-provoking discussions provided a variety of perspectives on the state of healthcare private equity along with insightful approaches to potential investments.
As always, we look forward to continuing the dialogue with our clients and partners. Please reach out to explore any of these themes further.

Domestically controlled REIT ownership update: Proposed regulations would remove domestic corporation look-through rule
ARTICLE / CLIENT ALERT
Domestically controlled REIT ownership update: Proposed regulations would remove domestic corporation look-through rule
October 24, 2025
Read time: 4 min
On October 20, 2025, the US Department of the Treasury (Treasury) and the Internal Revenue Service (IRS) released proposed regulations (Proposed Regulations) under Section 897[1] that would reverse prior regulations that looked through certain domestic C corporations to the shareholders for purposes of determining whether a real estate investment trust (REIT) is domestically controlled.
Background
Under Section 897, foreign corporations and nonresident aliens are generally subject to US federal income tax on any gain arising from the disposition of a US real property interest (USRPI), which may include interests in certain domestic corporations. However, interests in REITs (and certain regulated investment companies) that are “domestically controlled” are not treated as USRPIs. A REIT generally is considered “domestically controlled” if less than 50% of the value of its stock is held “directly or indirectly” by foreign persons at all times during the five-year period ending on the date of the disposition of an interest in the REIT (or during the REIT’s existence if shorter).
On April 24, 2024, the Treasury and the IRS released final regulations (2024 Final Regulations), generally effective for transactions occurring on or after April 25, 2024, expansively interpreting the phrase “directly or indirectly” for purposes of determining whether a REIT is domestically controlled. The 2024 Final Regulations adopted a partial look-through approach, dividing owners into “non-look-through persons” and “look-through persons,” with only non-look-through persons being taken into account for purposes of determining whether a REIT is domestically controlled. While domestic C corporations were generally classified as non-look-through persons, the 2024 Final Regulations included a special look-through rule that required looking through any non-public “foreign-controlled” domestic C corporation in which foreign persons hold directly or indirectly more than 50% of the fair market value of the corporation’s outstanding stock, as well as a 10-year transition rule with respect to existing entities. For a detailed discussion of the 2024 Final Regulations, see our prior alert, “IRS Issues Final Regulations Addressing Ownership of Domestically Controlled REITs.”
The Proposed Regulations
The preamble to the Proposed Regulations states that the Treasury and the IRS have reconsidered their prior interpretation of “indirectly” reflected in the domestic corporation look-through rule and, upon further review, are now of the view that the text of Section 897(h)(4)(B), “as informed by the traditional tools of statutory construction, including evaluation of the provision’s purpose,” militate for treating an entity that is subject to US taxation as a non-look-through person. Accordingly, while the Proposed Regulations generally retain the 2024 Final Regulations, including the framework of “non-look-through persons” and “look-through persons,” they would remove the domestic corporation look-through rule and corresponding transition rule. Instead, all domestic C corporations would be treated as non-look-through persons in determining whether a REIT is domestically controlled.
The Proposed Regulations, upon finalization, would apply to transactions occurring on or after October 20, 2025. However, taxpayers may choose to apply the final regulations to transactions occurring on or after April 25, 2024. Taxpayers may also rely on the Proposed Regulations for transactions occurring before the date the Proposed Regulations are finalized. As a result, the Proposed Regulations would effectively retroactively revoke the domestic corporation look-through rule.


Navigating EKRA compliance: Legal developments in percentage-based marketing arrangements
ARTICLE / CLIENT ALERT
Navigating EKRA compliance: Legal developments in percentage-based marketing arrangements
October 24, 2025
Read time: 11 min
Since its enactment in 2018, the Eliminating Kickbacks in Recovery Act (EKRA) has remained one of the greater compliance mysteries facing the healthcare industry. The statute’s odd language and structure raises more interpretative questions than it answers. Recent cases have addressed one key area of ambiguity: the extent to which EKRA applies to certain sales and marketing practices and related compensation arrangements for laboratories, clinical treatment facilities, and recovery homes.
Despite EKRA’s many interpretive ambiguities, these recent developments have shed light on some of the statute’s contours and clarified the government’s position that percentage-based marketing payments are not expressly prohibited.
Background
In relevant part, EKRA prohibits persons from knowingly and willfully:
(1) solicit[ing] or receiv[ing] any remuneration (including any kickback, bribe, or rebate) directly or indirectly, overtly or covertly, in cash or in kind, in return for referring a patient or patronage to a recovery home, clinical treatment facility, or laboratory; and
(2) pay[ing] or offer[ing] any remuneration (including any kickback, bribe, or rebate) directly or indirectly, overtly or covertly, in cash or in kind-
(A) to induce a referral of an individual to a recovery home, clinical treatment facility, or laboratory; or
(B) in exchange for an individual using the services of that recovery home, clinical treatment facility, or laboratory.
Unlike certain other federal fraud and abuse laws that apply only to services paid for by federal healthcare programs, such as the Anti-Kickback Statute (AKS), EKRA applies to services covered by all payors. Each violation of EKRA could result in criminal fines of up to $200,000, imprisonment for up to 10 years, or a combination of both.
Notably, EKRA’s statutory prohibition omits the AKS’s “arranging for or recommending” language that is often cited as covering marketing activities in federal healthcare programs. To date, courts have differed on the extent to which EKRA covers certain marketing activities. In connection with the underlying cases, the issue of whether percentage-based sales and marketing compensation is per se illegal under EKRA has been an area of focus.
Despite the statute’s broad scope, EKRA includes statutory exceptions (which some courts refer to as “safe harbors”) for certain arrangements. For example, EKRA includes an exception protecting bona fide employment and independent contractor relationships. EKRA’s exception is narrower than the AKS employment exception and safe harbor, which stakeholders have long relied on to protect sales and marketing payments to employees, including those that are based on a percentage of revenue. EKRA’s employment and independent contractor exception, however, does not protect arrangements where compensation is determined or varies by the number of individuals referred, the number of tests or procedures performed, or the amount billed to or received from healthcare benefit programs.
Several federal courts recently addressed the extent to which EKRA applies to certain sales and marketing arrangements, including several district courts that reached different conclusions. A recent US Court of Appeals for the Ninth Circuit decision resolved the district split in that circuit. In the course of the Ninth Circuit case, the regulated industry received some helpful clarity on the US Department of Justice’s position regarding whether EKRA per se prohibits percentage-based sales and marketing compensation. (Spoiler alert: it does not.)
- In S&G Labs Hawaii, LLC v. Graves, the US District Court for the District of Hawaii considered whether percentage-based payments made to an employee overseeing client accounts on behalf of a medical testing company violated EKRA. The employee’s clients were various healthcare providers and organizations whose patients had a need for the testing services offered by S&G Labs. To determine the statute’s scope, the court read EKRA’s language in light of definitions established by the AKS, including those for “remuneration” and “individual.” In holding that the payments did not violate EKRA, the court determined that because the employee’s clients were healthcare providers rather than the actual patients who needed the services offered by S&G, any payments made to the employee could not have been to induce him to refer “individuals” to the lab. The court thus concluded that EKRA did not apply to the underlying employment arrangement.
- Another case in the same judicial circuit, United States v. Schena, concerned the alleged submission of improper claims by the owner of a medical lab testing facility in violation of multiple fraud and abuse statutes, including EKRA. The EKRA allegations related to the percentage of revenue payments to marketers. In its consideration of the EKRA issue, the US District Court for the Northern District of California specifically objected to the S&G Labs court’s reliance on the AKS to interpret the statutory language of EKRA. Relatedly, the Schena court found that EKRA had no “directness” requirement, and that therefore the statute’s prohibition on making payments to induce the referral of an individual extends to situations where a person is marketing only to physicians or other healthcare providers.
The Ninth Circuit heard the S&G Labs and Schena cases on appeal in February 2025 and issued slip opinions for each in July 2025. In Schena, the Ninth Circuit’s analysis centered on the two primary legal issues raised in the district court:
- Whether EKRA reaches payments made to persons who do not have the authority to refer patients and do not otherwise interact directly with patients
- If EKRA does reach such payments, what it means to “induce a referral” in the context of the statute.
On the first question, the Ninth Circuit ultimately affirmed the district court’s conclusion, holding that EKRA’s scope is not limited only to payments made to those who directly interact with or are able to refer patients.
On the second question, the Ninth Circuit held that as with the AKS standard, “to induce a referral” in violation of EKRA requires some degree of “undue influence” over the referrals. This may include, for example, a marketer improperly guiding a doctor’s referrals by making patently false representations about the service being marketed. The court went on to clarify that, as the government itself recognized during oral argument, standard percentage-based compensation structures do not constitute per se violations of EKRA, “even when the marketing personnel are persuasive in driving business,” as long as undue influence is not present. This point proved dispositive to the EKRA claim in the S&G Labs appeal, as the court determined that the contract at issue did not automatically violate EKRA by the mere fact that it included a percentage-based marketing compensation structure. Despite taking a major step by officially adopting the “undue influence” standard in the EKRA context, the Ninth Circuit recognized that “future cases will be needed” to demarcate the relative boundaries of that standard.
When questioned by the Ninth Circuit on whether EKRA implicates standard percentage-based marketing arrangements, the government conceded in oral argument that percentage-based payments are not per se unlawful under EKRA. To support this proposition, the government cited to United States v. Marchetti, a case involving the AKS that found that “the structure of [a] contract alone is not sufficient evidence to produce a conviction” under the AKS. The government went on to note that whether an arrangement implicates EKRA is a fact-specific inquiry, and the government is required to show beyond a reasonable doubt that the “purpose of the kickback was a quid pro quo to induce referrals” and was not simply to compensate marketing, advertising, hours worked, or other legitimate services. The Ninth Circuit expressly noted this government concession in its Schena opinion.
Prior to the publication of the Ninth Circuit’s opinions above, the US District Court for the Eastern District of Pennsylvania evaluated the merits of both the Schena and S&G Labs decisions and ultimately sided with the latter in GF Industries of Missouri, LLC v. Lehigh Valley Genomics LLC. The GF Industries court found that the AKS’s analogous language was in fact relevant to the EKRA analysis, and proceeded to reference AKS caselaw to determine the sorts of arrangements that fall within EKRA’s scope of prohibition. As with the district court decision in S&G Labs, the court held that EKRA may not apply to percentage-based payments where a marketer’s clients are providers rather than patients. Although the GF Industries court reached a different conclusion about the scope of EKRA generally, it reached the same conclusion as the Ninth Circuit in adopting the Marchetti conclusion that “percentage-based compensation structures are not per se unlawful” and that “the structure of [a] contract alone is not sufficient evidence to produce a conviction.”
Next steps
Although there is still judicial disagreement about whether EKRA applies to payments made for sales and marketing services when the target audience is healthcare providers and others who are not patients, the courts are in alignment that percentage of revenue compensation to sales and marketing staff are not per se illegal under EKRA. Laboratories, clinical treatment facilities, and recovery homes should consider these recent cases when devising or revising compensation structures and should implement guardrails to mitigate the risk of sales and marketing staff being perceived as exerting “undue influence” over referrals. As the Ninth Circuit cautioned, where to draw the line is not yet settled. Regulated actors should work closely with experienced counsel to assess the specific facts and circumstances surrounding their sales and marketing compensation structures to mitigate EKRA risks.
For more information about compliance with EKRA and other fraud and abuse laws, contact any of the authors of this client alert or your regular McDermott Will & Schulte lawyer.



Bulletin Concurrence XV
ARTICLE
Bulletin Concurrence XV
October 2025
Read time: 2 min
We are delighted to share the fifteenth Bulletin Concurrence which aims to keep you up to date with the key developments in competition law over the second and third quarters of 2025.
Read the full Bulletin Concurrence XV (in French).

EXPO REAL 2025: A time to get personal
ARTICLE
EXPO REAL 2025: A time to get personal
October 23, 2025
Read time: 5 min
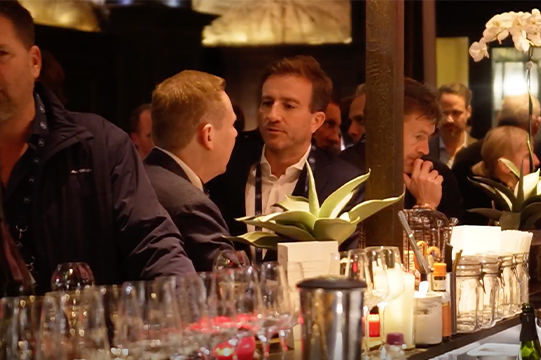
EXPO REAL 2025 marked a major shift in the real estate investment landscape, as industry leaders began to take action despite ongoing geopolitical uncertainty. Key conference themes included the evolution of risk assessment, shifts in capital flows towards European markets, and the enduring appeal of logistics and living sectors. As the market continues to regain confidence, personal connection and trust remain essential for effective risk allocation and investment decisions.
Shifting sentiment: From caution to action
Sentiment at recent conferences has been defined by a restraint on investor confidence due to geo-political and wider macro uncertainty. The outlook was defined by caution and survival until such headwinds eased.
Whilst EXPO 2025 did not confine the themes of caution and survival as issues of the past or mark a return to “optimism” it was the first for a while to see mobilisation towards action in the investment and debt markets.
Whist certain markets and geographies remain dislocated, there is an increasing acknowledgement that within a new world of greater pragmatism and acceptance of geo-political instability and uncertainty, the macro-headwinds can now be risk-allocated and inform rather than deter transactional activity.
Mobilisation enabled from this shift in mindset may take time to translate into pre-Covid transaction volumes, as the management of and appetite for risk is likely to influence the speed and approach to transactions but is nevertheless an important vote of confidence in the fundamentals of the European market.
The debt landscape
Whilst underlying transaction volumes are increasing, the small number of high-quality new-money deals which do come to market are aggressively brokered.
In this competitive landscape, and in the context of non-core deals, lenders with the ability to blend different sources of capital (including cheaper insurance money) are well placed to secure these important mandates.
The comparative scarcity and pricing pressures of deals are increasingly forcing lenders to deploy tickets in the lower mid-market (€30m-€50m) where speed of execution and the ability to underwrite more transitional business plans are highly prized.
As capital raising pressures slowly ease on managers with an allocation to credit, lenders continue to asset classes which benefit from structural undersupply in the market, combined with compelling debt-entry points.
Evolution of risk assessment
In a market regaining its confidence, it was clear that careful and considerate management of risk will be a major influence on transaction activity in the near term.
As institutional capital is attracted by asset classes where operational excellence and expertise is a key driver of value and returns, the need for such capital to partner with sector specific operators fuels a rise in risk-sharing transaction models, joint ventures, co-investments and secondaries.
Whilst the usual fundamentals of site selection, due diligence and realistic transaction timetables will remain important, confidence in investing through long-term partnerships requires cultural and personal alignment and there was a palpable feeling of the need to build deep and informed connections between parties to inform risk management. Whilst AI may allow elements of investment due diligence to be accelerated it cannot replace personal connection and accumulated trust.
A market redrawn to embrace the new normal
So, in a market ready to mobilise how will a return to optimism translate into activity?
Shifts in capital flows
An increased allocation towards European markets from global sources of institutional and sovereign wealth capital will make a meaningful difference. There was a consistent sentiment of the UK and mainland Europe being ahead of the cycle when compared to the US, flexible, tech-enabled, sustainable buildings are likely to attract such capital enabling deployment at scale familiar and stable markets.
Enduring appeal of logistics and living sectors
Whether through a combination supply chain changes driven by the impact of AI and automation, a continued evolution and sophistication of logistics to meet the customer demands for speed and accessibility, and a need to embrace and prepare for the anticipated growth required in data centre capacity, we see logistics at the heart of investment activity.
Demographics and societal change will continue to drive investor appetite for the living sector. As populations continue to live longer and become accustomed to home ownership no longer being a barometer of personal prosperity and status, the need for the living sector to embrace such shifting needs is seeing a market ready to offer options beyond traditional build-to-rent. Single-family Rental and Senior Living are comparatively underdeveloped asset classes and we expect to see increased allocations to these sub-sectors.
Implications of increased defence spending across Europe
This marked shift in government policy across Europe was a significant discussion topic. Outside of the need for increased manufacturing capacity, existing and new supply chains will need to be developed and adapted to facilitate the political shift in priorities. As with other sectors, it will be critical that infrastructure spending from both public and private sources keeps pace and enables rather than frustrates development.
Conclusion
Whilst encouragement can be taken from a gradual increase to levels of confidence and pragmatism in the market, the most important sentiment we took from the Messe was the enduring power of personal connection and trust as the bedrock of investment. We saw a market ready to do business but in a world where effective risk allocation is paramount. Getting closer to and understanding investment partners cannot be outsourced or automated and EXPO 2025 was a welcome restatement of its importance.


California SB 711: Closing the conformity gap with the IRC
ARTICLE
California SB 711: Closing the conformity gap with the IRC
Oct 21, 2025
Read time: 3 min
After nearly a decade of lagging behind federal tax updates, California has finally hit “refresh.” Signed into law on October 1, 2025, Senate Bill (SB) 711 delivers the most sweeping overhaul of California’s tax conformity rules since 2015.
The legislation advances the state’s conformity to the Internal Revenue Code (IRC) from January 1, 2015, to January 1, 2025, for taxable years beginning on or after that date, thereby bringing California into line with hundreds of federal tax changes made over the past decade. This alignment is designed to simplify compliance and reduce costly inconsistencies between federal and state returns. But conformity also comes with caveats, and taxpayers will need to understand where California continues to chart its own course.
The major changes introduced by SB 711
Updating California’s IRC “conformity date” to January 1, 2025, the bill incorporates several federal amendments enacted during the last decade. For example, one major innovation in SB 711 is the overhaul of California’s research credit. Starting in 2025, taxpayers may use the Alternative Simplified Credit method under IRC § 41(c)(4), which was adjusted with lower state percentages for qualified research expenses (3% and 1.3% instead of 14% and 6%). Other notable modifications include conformity to federal limitations on IRC § 1031 exchanges to real property and the elimination of the deferral for exchanges of certain non-real property.
Of course, many instances of nonconformity to recent federal enactments remain, including:
- Corporate alternative minimum tax (CAMT). SB 711 continues to exclude the new federal CAMT, created by the Inflation Reduction Act of 2022 (IRA), from conformity.
- Renewable energy credits. SB 711 does not adopt the clean energy credits added under the IRA.
- Net operating loss rules. California continues to diverge from federal carryback and carryforward limits.
- IRC 163(j). SB 711 continues nonconformity to interest expense limitations under IRC § 163(j).
- One Big Beautiful Bill Act (OBBBA) (P.L. 119-21). Because SB 711 conforms to the IRC as of January 1, 2025, it does not include changes made under the OBBBA, which was signed by US President Donald Trump earlier this year.
Preparing for the transition
SB 711 applies to both the personal income tax and corporation tax regimes for taxable years beginning on or after January 1, 2025. Taxpayers should begin modeling how the new conformity affects their liabilities and planning strategies. Key steps include:
- Reviewing federal provisions now incorporated into state law.
- Identifying exceptions and modified rules applicable to your business or filing type.
- Consulting tax professionals to evaluate the impact on research and development incentives, loss carryovers, and credit eligibility, among others.
- Monitoring California Franchise Tax Board guidance as the agency clarifies implementation details over the coming months.
Bottom line
SB 711 represents California’s latest move to more closely synchronize its tax code with the modern federal landscape. The reform promises greater clarity, fewer compliance headaches, and a more innovation-friendly framework. Yet, with selective decoupling and transitional complexities, taxpayers will need to remain vigilant. In short, California may finally be closer to being in sync – but understanding the fine print remains essential.


California antitrust law changes underscore state’s intent to maximize deterrence
ARTICLE / CLIENT ALERT
California antitrust law changes underscore state’s intent to maximize deterrence
October 21, 2025
Read time: 6 min
What are the changes to California antitrust law?
Governor Gavin Newsom recently signed two new bills into law, and amendments to the Cartwright Act are likely forthcoming.
What are the two new bills and why are they significant?
On October 6, 2025, Governor Gavin Newsom signed into law California Senate Bill No. 763 (SB 763), effective January 1, 2026, which increases the maximum corporate criminal antitrust penalties in California to $6 million and provides for new civil penalties of up to $1 million in cases brought by the California attorney general. The new criminal and civil antitrust penalties represent a $5 million and $1 million increase, respectively, for antitrust violations. The increased fines serve as an increased deterrent for antitrust violations. Furthermore, since 2024, Senior Assistant Attorney General (AAG) for Antitrust Paula Blizzard has mentioned in statements that California intends to bring criminal antitrust enforcement actions in the near future, reviving its criminal program after 25 years. These increased fines may further assist California in seeking higher fines for these intended cases.
The same day, Governor Newsom also signed California Assembly Bill No. 325 (AB 325), effective January 1, 2026. The law adds a section to the Cartwright Act prohibiting use or distribution of common pricing algorithms as part of an agreement with another or to coerce another to set or adopt recommended prices or commercial terms recommended by the algorithm. This law comes on the heels of the Department of Justice Antitrust Division’s case against a real estate pricing aggregator and several property managers, alleging that the property managers used an algorithmic pricing service collectively to fix prices for rental properties. Also signed at the same time were several other laws seeking to protect renter rights, as California seeks to address rising rental prices.
AB 325 was designed to strike at the heart of the conduct at issue in the antitrust division’s litigation against the real estate pricing aggregator, in which the State of California joined as a named plaintiff. In fact, Doha Mekki, who was previously the acting AAG for the antitrust division (and principal deputy AAG during the majority of the Biden administration, which brought the litigation), provided testimony in support of the California bill, specifically mentioning that AI collusive practices can be used to align pricing in housing. A press release announcing passage of AB 325 also disclosed the intent behind the bill to close “loopholes in California’s Cartwright Act that let corporations use pricing algorithms to secretly coordinate prices, which raise costs for essentials like rent, groceries, and housing.”
What else is happening with California’s antitrust laws?
At the direction of the California Legislature in 2022, the California Law Revision Commission (CLRC) began undertaking an antitrust law study meant to address four potential pathways for modernizing California antitrust law. One of the pathways focuses on whether the state’s antitrust law should be revised to “outlaw monopolies by single companies as outlawed by Section 2 of the federal Sherman Act.”
In the almost three years since, the CLRC has signaled that it intends to formally recommend what it calls the Enhanced Single Firm Conduct Provision (Enhanced SFC Provision) for adoption by the California Legislature. On September 18, 2025, the CLRC elected to move forward with the Enhanced SFC Provision and plans to vote on a “draft tentative recommendation” to the California Legislature at its December 4 meeting. The most recent publicly available draft language of the provision provides that it is “unlawful for one or more persons to act, cause, take or direct measures, actions, or events (1) In restraint of trade or (2) To monopolize or monopsonize, to attempt to monopolize or monopsonize, to maintain a monopoly or monopsony, or to combine or conspire with another person to monopolize or monopsonize in any part of trade or commerce.” This provision is the CLRC’s compromise between two other expansive draft options. All three proposals have included some intent to ensure that the provision is more expansive than existing “restrictive” federal jurisprudence.
The Enhanced SFC Provision would codify existing federal Sherman Act Section 2 language in California’s Cartwright Act and add an illegal monopsonization offense – incorporating a new “restraint of trade” element and including interpretive guidance that likely broadens the proposed provision beyond federal principles of antitrust law and existing federal antitrust jurisprudence for Sherman Act Section 2. Specifically, the term restraint of trade encompasses the enumerated list of prohibited restraints of competition in Section 16720 of the California Business and Professions Code but also expands beyond that specific list of illegal practices. Furthermore, the proposal contains language that the statute should be interpreted “reflecting California’s laws, preferences, and priorities,” which is intended to require California courts to liberally construe the Enhanced SFC Provision to serve California’s preference – as stated by the CLRC – for maximizing deterrence of antitrust violations. The proposal also intends to make explicit that the Enhanced SFC Provision is not bound by federal case law. This broad proposal appears to be in line with the CLRC’s stated goal of maximizing deterrence of antitrust violations in the state.
Recent proposed and enacted updates to California antitrust law
The CLRC’s development of its formal proposal continues in the background as California makes other major updates to its antitrust laws, which also appear to address the goal of increased deterrence. Although SB 763 and AB 325 are set to take effect on January 1, 2026, the CLRC is still accepting public comments throughout the duration of its iterative antitrust study process. Several trade associations, think tanks, and even individual commenters have submitted thoughts on the SFC proposal and the antitrust study at large.
If you have a question about the California antitrust law updates or wish to comment on the likely forthcoming changes to California antitrust law, please contact one of the lawyers listed below.


Decoupling from DC: How HB 4961 redefines Michigan’s tax base
ARTICLE
Decoupling from DC: How HB 4961 redefines Michigan’s tax base
Oct 20, 2025
Read time: 5 min
At the tail end of the 2025 – 2026 legislative session, Michigan’s Legislature moved swiftly to enact House Bill (HB) 4961, which decouples from five federal tax benefits enacted earlier this year under the federal One Big Beautiful Bill Act (OBBBA).
Given that many of the OBBBA’s provisions – particularly those expanding tax deductions or credits – will reduce taxable income and state revenue, Michigan is one of many states assessing the impact of the OBBBA’s changes. Earlier this year, the Michigan Department of Treasury estimated that following the OBBBA’s changes to Internal Revenue Code (IRC) Sections 174A, 168(k), 168(n), 179, and 163(j), state revenues would be reduced by approximately $540 million in Fiscal Year (FY) 2025 – 2026 and by more than $2 billion through 2030. While the state’s decision to decouple comes as no surprise for businesses operating in Michigan, this move eliminates – or significantly reduces – the state-level benefit of the following five federal tax changes made in the OBBBA.
Key decoupling provisions
IRC § 174A: Domestic R&D amortization
OBBBA: Under the OBBBA, Section 174A allows full expensing of domestic research or experimental expenditures incurred in taxable years beginning after December 31, 2024. The OBBBA also permits taxpayers to alternatively elect to amortize such expenses over five years.
Michigan: For tax years beginning after December 31, 2024, HB 4961 requires taxpayers to compute their Michigan income as if Section 174A were not in effect. This means that Michigan taxpayers will not receive a state-level benefit from the new research and development (R&D) amortization option. Research intensive businesses will also have higher taxable income.
IRC § 168(k): Federal bonus depreciation
OBBBA: The OBBBA permanently restores 100% bonus depreciation at the federal level for qualified property acquired after January 19, 2025. Prior to the OBBBA, bonus depreciation phasedown rules enacted under the Tax Cuts and Jobs Act of 2017 would have reduced bonus depreciation to 60% for property placed in service in 2024 and eliminated it entirely by 2027.
Michigan: Michigan has historically instructed taxpayers to compute their Michigan income as if Section 168(k) was not in effect, meaning that under Michigan law, any bonus depreciation claimed on a taxpayer’s federal return was not allowed for corporate income tax purposes. Under HB 4961, Michigan continues to decouple from Section 168(k).
IRC § 168(n): Disaster-area bonus depreciation
OBBBA: The OBBBA also introduces a new deduction under Section 168(n) for investments in qualified domestic factory property.
Michigan: HB 4961 does not recognize the new deduction under Section 168(n). Property that qualifies for bonus depreciation federally must be depreciated under regular Modified Accelerated Cost Recovery System rules for Michigan, leading to slower cost recovery and higher near-term taxable income.
IRC § 179: Expensing for small business property
OBBBA: The OBBBA enhances Section 179, which permits immediate expensing of certain equipment and software purchases (subject to federal dollar limits), by significantly increasing the expensing limit and phase-out threshold beginning in tax years starting after December 31, 2024.
Michigan: HB 4961 freezes conformity to the 2024 limits, ignoring future federal increases. Small- and mid-sized businesses will lose the benefit of higher expensing thresholds that Congress may adopt later, narrowing the value of this investment incentive.
IRC § 163(j): Business interest expense limitation
OBBBA: For taxable years beginning after December 31, 2024, the OBBBA reinstates the earnings before interest, taxes, depreciation, and amortization-based calculation for business interest expense limitations by modifying the definition of adjusted taxable income (ATI) to be calculated permanently without regard to the allowance for depreciation, amortization, or depletion. This change increases the amount of ATI to which the limitation applies, leading to a larger deductible interest expense at the federal level.
Michigan: Under HB 4961, Michigan will follow Section 163(j) as it existed on December 31, 2024, and will not automatically adopt any later federal modifications. This means that Michigan taxpayers must compute ATI to include depreciation and amortization deductions. As a result, the amount of ATI to which the limitation applies is reduced, leading to a smaller deductible interest expense. Businesses also won’t benefit from future federal expansions of interest deductibility.
Notably, while Michigan’s decision to decouple from the OBBBA’s tax provisions reduces the benefits of the federal tax cuts for Michigan businesses, HB 4961 does not eliminate the refundable R&D tax credit that was enacted by the Michigan Legislature earlier this year. This credit remains available to qualifying corporations and qualifying flow-through entities for tax years beginning on and after January 1, 2025. The credit may be claimed against the state’s corporate income tax (for corporations) and the withholding tax (for flow-through entities).
Takeaways
While Michigan may be one of the first states to legislatively decouple from the OBBBA’s tax changes, it will not be the last. In Illinois, for example, the Department of Revenue has estimated that General Funds revenue collections will be more than $830 million below the amount estimated at the time the FY 2026 budget was passed because of the OBBBA. Accordingly, the Illinois Governor’s Office of Management and Budget has recommended the general assembly take immediate action to decouple from certain federal tax provisions to avoid some of the changes included in the OBBBA, including the new federal bonus depreciation rules. The Governor’s Office has also recommended updating the Illinois Income Tax Act to reflect the federal change from Global Intangible Low-Taxed Income to Net Controlled Foreign Corporation Tested Income. The Illinois General Assembly is expected to consider the governor’s recommendations during its six-day fall veto session, which runs from October 14 – 16 and October 28 – 30.
EEOC enforcement actions underscore employers’ religious accommodation policies
ARTICLE / CLIENT ALERT
EEOC enforcement actions underscore employers’ religious accommodation policies
October 20, 2025
Read time: 5 min
On August 22, 2025, the US Equal Employment Opportunity Commission (EEOC) published a press release that demonstrates the EEOC’s intensified efforts to protect religious freedom in the workplace. These efforts include investigating more than 10,000 charges challenging COVID-19 vaccine mandates and vigorously pursuing charges and lawsuits involving religious accommodation and antisemitism claims. The EEOC’s recent actions provide guidance on how employers should navigate religious accommodations in the workplace.
Background
Title VII of the Civil Rights Act of 1964 prohibits employment discrimination based on religion and requires employers to reasonably accommodate sincerely held religious beliefs unless doing so causes an undue hardship. In 2023, the Supreme Court of the United States clarified in Groff v. DeJoy (143 S. Ct. 2279, 2023) that “showing ‘more than a de minimis cost’ … does not suffice to establish ‘undue hardship’ under Title VII” (see our previous alert). Instead, employers must demonstrate a “substantial” burden and take into account “all relevant factors in the case at hand, including the particular accommodations at issue and their practical impact in light of the nature, size and operating cost of an employer.”
Lessons from the EEOC’s 2025 enforcement actions
The EEOC’s August 22 press release, “200 Days of EEOC Action to Protect Religious Freedom at Work,” provides valuable insight into how the EEOC will enforce the new Groff standard against employers:
- Rigorously evaluate whether a requested accommodation is an undue hardship. The EEOC recently sued a hotel for allegedly refusing employees’ request for an accommodation to observe the Sabbath, leading to her resignation. The EEOC filed a similar lawsuit against a staffing agency for allegedly not hiring a Muslim applicant because of his request for accommodation to attend Friday prayer. Additionally, the EEOC has filed two lawsuits against employers who denied their employees’ requests to wear skirts instead of pants for religious reasons.
- Carefully consider denying religious accommodation requests where denial will adversely affect the terms or conditions of employment. In a settlement with the EEOC, a healthcare system agreed to pay more than $1 million and offer reinstatement to employees it terminated for refusing COVID-19 vaccination because of religious reasons. The EEOC found that Mercyhealth violated Title VII by denying accommodation requests and requiring unvaccinated employees to either accept termination or sign a form allowing a $60 monthly “vaccine incentive charge” to be deducted from their pay. As part of the settlement, Mercyhealth must revise its policies, train staff on religious accommodations, and report future decisions to the EEOC.
- Exercise caution when acting on conduct outside of work. The EEOC has sued a snow park for allegedly firing a Christian employee over faith-based social media posts that did not mention his workplace or coworkers. However, his supervisor asked the employee to refrain from making such posts. The employee was terminated just days after confirming with his supervisor that he could continue posting Bible verses. According to the EEOC, the termination violated Title VII’s prohibition against religious discrimination.
In addition to the EEOC’s renewed focus on religious discrimination claims, other federal agencies have continued their efforts to protect religious freedoms. Notably, in July 2025, the US Office of Personnel Management issued two memorandums regarding religious accommodations and religious expression in federal workplaces. Although these memorandums apply only to federal agencies for now, they may foreshadow the heightened expectations around religious accommodations for private employers.
The first memo, released July 16, requires agencies to take a “generous approach” to religious accommodations, such as offering flexible schedules, leave options, and telework. Telework is highlighted as a “low-cost solution” that should be denied only with “evidence of significant operational impact.” The memorandum reiterates that only “substantial increased costs in relation to the conduct of [an employer’s] particular business” constitute an undue hardship and not “minor inconveniences.”
The second memo, issued July 28, requires agencies to protect personal religious expression in the workplace. Employees must be allowed to express their faith privately “to the same extent” as nonreligious expression. Agencies may regulate speech based on time and place but not on content or viewpoint. Citing Groff v. DeJoy, the memorandum emphasizes that coworker discomfort with religious practices is not a factor when evaluating undue hardship.
Next steps
- Review and update workplace policies. Employers should conduct a thorough review of their religious accommodation and harassment policies to ensure legal compliance and internal consistency. Employers that do not currently have a religious accommodation policy should consider incorporating one into their employee handbook.
- Establish a formal religious accommodation process. Employers should implement a structured process for evaluating religious accommodation requests, including clear criteria for assessing what constitutes a “substantial increased cost” in the context of their specific operations. All requests and related decisions should be thoroughly documented to ensure transparency and consistency.
- Provide targeted training for human resources personnel and managers. Human resources staff and managers should receive training on how to identify and appropriately respond to religious accommodation requests, including those involving COVID-19 vaccination policies, religious holidays, religious dress, and prayer practices.
If you have any questions about navigating religious accommodations in the workplace, please contact your McDermott Will & Schulte lawyer or one of the authors.