Content Type: Article

  • What will change with the EU Medical Devices Regulation?

    ARTICLE

    What will change with the EU Medical Devices Regulation?

    June 2021

    Read time: 2 min

    Key takeaways
    Overview

    For many years, a planned reform of medical device law has preoccupied the industry – now the new law is becoming reality. Jana Grieb and Dr Deniz Tschammler with explanations of the upcoming changes.

    In depth
    Authors
    More insights

  • Legal Tech for Legal Departments

    ARTICLE

    Legal Tech for Legal Departments

    June 8, 2021

    Read time: 1 min

    Key takeaways
    Overview

    eLearning with McDermott and BRYTER

    Anja Bertrand and Philip Uecker on eLearning at McDermott and BRYTER.

    In depth
    Authors

    Dr. Anja Bertrand

    Associate

    Cologne, Düsseldorf

    Dr. Philip Uecker

    Associate

    Düsseldorf

    More insights

  • Updated Vaccination Guidance and New York Law Developments

    Updated Vaccination Guidance and New York Law Developments

    ARTICLE / CLIENT ALERT

    Updated Vaccination Guidance and New York Law Developments

    June 11, 2021

    Read time: 9 min

    Key takeaways
    Overview

    On May 28, 2021, the U.S. Equal Employment Opportunity Commission (“EEOC”) updated its previously published guidance entitled “What You Should Know About Covid-19 and the ADA, the Rehabilitation Act, and Other EEO Laws,” discussed in previous SRZ Alerts. The updated guidance addresses issues relating to mandatory vaccination programs, exceptions and accommodations under such programs, and the legality of vaccine incentive programs.

    Mandatory Vaccinations

    According to the updated EEOC guidance, under the Americans with Disabilities Act of 1990 (“ADA”), Title VII of the Civil Rights Act of 1964 (“Title VII”) and other federal nondiscrimination laws, employers may mandate that employees who are physically entering the workplace be vaccinated against COVID-19 (Section K.1). Employers that have a vaccine requirement must still provide reasonable accommodations for employees who, due to disability or sincerely held religious beliefs, will not be vaccinated.[1] These accommodations must be provided unless they pose an undue hardship on the operation of the employer’s business. Further, employees who do not receive a COVID-19 vaccine due to pregnancy may be entitled under Title VII to job adjustments to keep working, including seeking an exemption from the mandatory vaccination requirement. For example, as a reasonable accommodation, “an unvaccinated employee entering the workplace might wear a face mask, work at a social distance from coworkers or non-employees, work a modified shift, get periodic tests for COVID-19, be given the opportunity to telework, or finally, accept a reassignment” (Sections K.2, K.5, K.6, and K.12).

    If a mandatory vaccine program is to be implemented, employers should provide notice of the program’s introduction to all employees. The guidance notes that a best practice is to notify employees that the employer will consider requests for accommodation (Sections K.5 and K.12). The EEOC advised that employers with a mandatory vaccine requirement might need to respond to allegations that the requirement has a disparate impact or disproportionately excludes employees based on race, religion or other protected classifications. Further, application of mandatory vaccine requirements in the workplace cannot treat employees differently based on disability, race, color, religion, sex (including pregnancy, sexual orientation, and gender identity), national origin, age, or genetic information, unless there is a legitimate non-discriminatory reason (Section K.1).

    Vaccine Incentives

    The EEOC reiterated that employers may encourage employees to get the COVID-19 vaccine. To do so, employers may educate employees about the benefits of vaccination and may respond to concerns or questions. Further, employers may offer incentives for voluntary COVID-19 vaccinations, which includes both rewards and penalties.

    The EEOC cautioned employers that offer incentives to employees to receive a COVID-19 vaccination administered by the employer (or its agent) against providing an incentive that is so substantial as to be “coercive” (Section K.17). A “very large incentive” may be considered coercive because it could make employees feel pressured to disclose protected medical information in obtaining the vaccination (Section K.17). This incentive limitation, however, does not apply to employers that offer an incentive to employees that voluntarily provide documentation or other confirmation that they received a COVID-19 vaccination on their own from a third-party provider that is not their employer or an agent of their employer (Section K.17).

    Documentation or other confirmation of vaccination, like all medical information, must be kept confidential and stored separately from the employee’s personnel files (Section K.4). Under the ADA, it is also unlawful to disclose that an employee is receiving a reasonable accommodation.

    Emergency Use Authorization of Vaccines

    The new EEOC update gives no further clarification as to the legal implications of the Emergency Use Authorization (“EUA”) granted by the FDA to the COVID-19 vaccines (Section K). The update notes that “it is beyond the EEOC’s jurisdiction to discuss the legal implications of the EUA or the FDA approach.” As a result, employers still assume legal risk in mandating vaccines in the workplace. In fact, there are currently vaccine mandate lawsuits pending against employers in several states, including Texas, California, North Carolina, and New Mexico, based in part on the argument that employees cannot be required to take an EUA vaccine.

    New York’s Paid Sick Leave Law Update

    On May 28, 2021, Governor Andrew M. Cuomo announced that New York’s Paid Sick Leave Law now covers “any necessary recovery period from the COVID-19 vaccine.” As noted in a previous SRZ Alert, New York legislation granted employees paid leave time to receive the COVID-19 vaccine. Now, under New York’s Paid Sick Leave Law, time off to recover from the side effects from the COVID-19 vaccine will be considered a paid sick leave day. The Department of Labor noted that “employers are obligated to honor an employee’s desire to use accrued sick leave for recovery.”

    New York HERO Act Update

    On May 5, 2021, Governor Cuomo signed into law the New York Health and Essential Rights Act (“HERO Act”) with the promise that technical amendments to the law would be forthcoming. (The HERO Act and its impact on employers was described in a previous SRZ Alert.) These promised amendments (“Amendments”) were introduced as a bill in the New York State Legislature and passed both houses. We expect the Amendments to be signed into law in the coming days.

    The Amendments delay until July 5, 2021 the effective date of the first section of the HERO Act (addressing the prevention of occupational exposure to an airborne infectious disease). The Amendments clarify that the requirement that each covered employer adopt an exposure prevention plan will not take effect until after the New York State Department of Labor (“NYSDOL”) publishes its model prevention standards. Following the publication of these model standards, employers will have thirty days to adopt a prevention plan, which can be accomplished by adopting the NYSDOL’s model standards. In addition, employers must provide their prevention plans to all of their employees within sixty days after the NYSDOL publishes its model standards.

    The HERO Act’s airborne infectious disease prevention section will also be amended to provide additional protections to employers. Employees bringing civil actions against their employers for alleged violations of the airborne infectious disease prevention section of the HERO Act will no longer be entitled to liquidated damages and such actions must be brought within six months of the employee’s knowledge of the alleged violation. Employees must also give their employer notice of the alleged violation and generally provide the employer with thirty days to cure the violation. Employers sued under the HERO Act may recover their costs and reasonable attorneys’ fees from the employee (and/or the employee’s attorney) if the court finds that the action is “frivolous.”

    The Amendments exempt from the HERO Act’s workplace safety committee requirement employers that already have “a workplace safety committee that is otherwise consistent with the requirements of this section.” The workplace safety committees’ powers authorized under the HERO Act are also amended, including by limiting the committees’ right to review only those policies that concern “occupational safety and health.”

    New York’s Guidance for Office-Based Work

    On June 8, 2021, the New York State Department of Health updated its Interim Guidance for Office-Based Work (“Office Guidance”). As explained in a previous SRZ Alert, this guidance applies to all “office-based work.” The Office Guidance, while preserving much of its previous guidelines, for the first time reiterates New York’s adoption of the Centers for Disease Control and Prevention’s guidance for fully vaccinated individuals, which lifts certain COVID-19 precautionary protocols for fully vaccinated individuals. More specifically, office-based employers are now permitted, though not required, to rescind COVID-19 safety requirements (i.e., requiring employees to wear a mask and/or adhere to social distancing) for fully vaccinated employees, provided they follow applicable guidelines for masks, distancing and capacity, as outlined in New York State’s guidelines on Implementing CDC Guidance.”

    The Office Guidance eliminates general capacity limits for offices. Instead, employers need only ensure that capacity is limited by the space available for individuals to maintain the required social distancing, based on vaccination status. For fully vaccinated individuals, employers may allow full capacity without six feet distancing within either the entire office or a separate, designated part of the office. Note that in-person gatherings continue to be discouraged.

    The Office Guidance simplifies employers’ screening requirements by allowing such screening to be completed by, among other methods, “signage,” which appears to allow employers to pose the screening questions to all entrants through signs containing the questions, instead of through individual questionnaires. In addition, the required screening questions are modified to focus on whether employees have 1) experienced COVID-19 symptoms, 2) had close contact with someone with COVID-19 and 3) tested positive for COVID-19.

    OSHA COVID-19 Safety Regulation for Healthcare Employers

    On June 10, 2021, the Occupational Safety and Health Administration (“OSHA”) issued its long-awaited emergency temporary standard pertaining to COVID-19. This regulation — OSHA’s first nationwide COVID-19 workplace safety rule — applies only to healthcare employers to protect health care workers against exposure to COVID-19 in the workplace. More specifically, this rule “applies to all settings where any employee provides healthcare services or healthcare support services,” except for settings specifically exempted by the rule.

    Authored by Mark E. Brossman, Ronald E. Richman, Scott A. Gold, Max Garfield, Donna K. Lazarus and Abdulrahman Alwattar.

    If you have any questions concerning this Alert, please contact your attorney at Schulte Roth & Zabel or one of the authors.


    [1] Note that EEOC guidance explains that the definition of religion is broad, and employers should ordinarily assume that an employee’s request for religious accommodation is based on a sincerely held religious belief, practice or observance.


    This is a fast-moving topic and the information contained in this Alert is current as of the date it was published.

    This communication is issued by Schulte Roth & Zabel LLP for informational purposes only and does not constitute legal advice or establish an attorney-client relationship. In some jurisdictions, this publication may be considered attorney advertising. ©2021 Schulte Roth & Zabel LLP.

    All rights reserved. SCHULTE ROTH & ZABEL is the registered trademark of Schulte Roth & Zabel LLP.

    In depth
    Authors

    Mark E. Brossman

    Partner

    New York – 919 Third Avenue

    Ronald E. Richman

    Partner

    New York – 919 Third Avenue

    Max Garfield

    Partner

    New York – 919 Third Avenue

    Donna K. Lazarus

    Partner

    New York – 919 Third Avenue

    Abdulrahman Alwattar

    Associate

    New York – 919 Third Avenue

    More insights

  • Fiduciary Engagement in Artificial Intelligence Innovation: A Governance Imperative

    Fiduciary Engagement in Artificial Intelligence Innovation: A Governance Imperative

    ARTICLE / REPORT

    Fiduciary Engagement in Artificial Intelligence Innovation: A Governance Imperative

    June 2021

    Read time: 2 min

    Overview


    In depth
    Tabs
    More insights
    Endnotes

  • Key Takeaways | How Traditional Energy Funds are Shifting Toward Green Energy: A Conversation with Encap Investments and Quantum Energy Partners

    Key Takeaways | How Traditional Energy Funds are Shifting Toward Green Energy: A Conversation with Encap Investments and Quantum Energy Partners

    ARTICLE

    Key Takeaways | How Traditional Energy Funds are Shifting Toward Green Energy: A Conversation with Encap Investments and Quantum Energy Partners

    June 10, 2021

    Read time: 5 min

    Key takeaways
    Overview

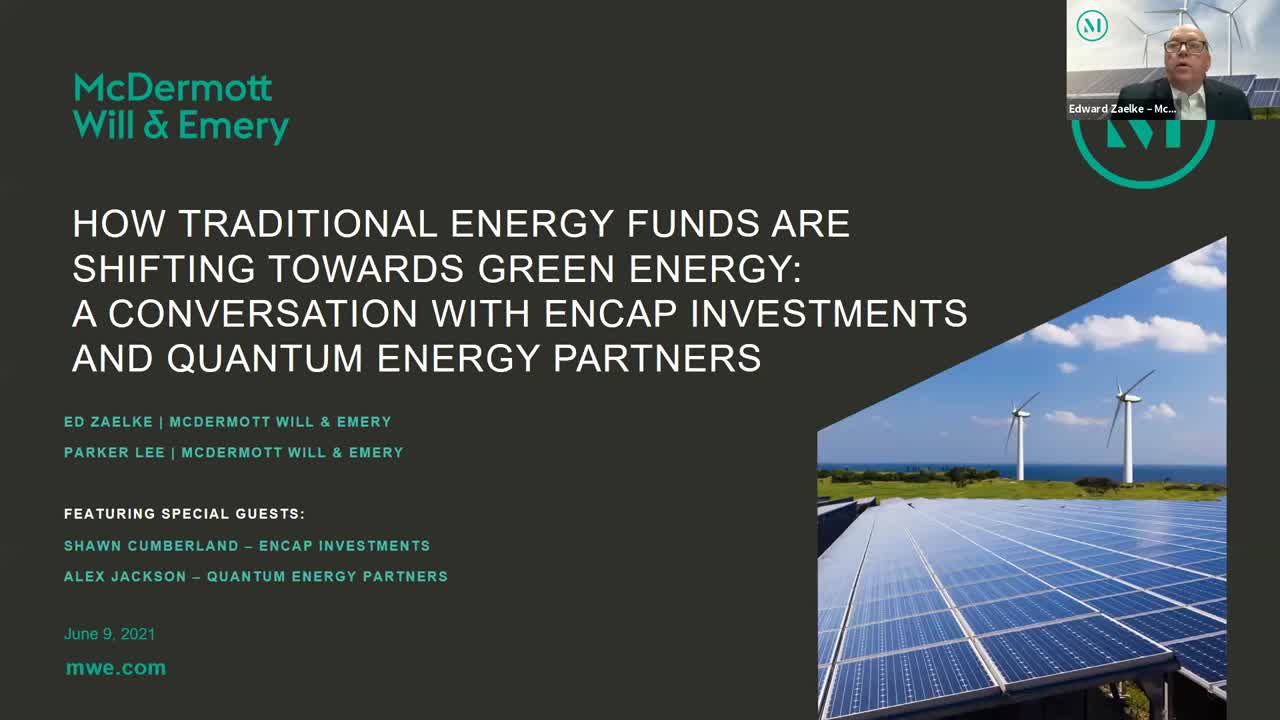
    The energy market has undergone significant change in the past 12 months, with even more on the horizon. Our webinar series explores how these changes have shaped—and will continue to impact—the energy industry, including discussions of what’s to come.

    Our latest webinar featured McDermott partners Edward Zaelke and Parker Lee, as well as Shawn Cumberland, Managing Partner of Energy Transition of EnCap Investments, and Alex Jackson, Director at Quantum Energy Partners.

    Video – How Traditional Energy Funds are Shifting Toward Green Energy: A Conversation with Encap Investments and Quantum Energy Partners webinar, part of McDermott’s 2021 programming (runtime: 30m)

    Below are key takeaways from the webinar:

    1. Although energy transition investment funds may have different focuses, they generally take an all-of-the-above approach, with respect to investing, in the various subsectors of the energy transition and are willing to invest in any technology, in any portion of the energy industry (except for highly capital intensive projects with binary risk profiles).
    2. Similar to the approach for conventional oil and gas investments, investment funds are focused on investing in strong management teams with a successful track record, which is manifested either through a management team that already has an interesting business plan or a management team that can successfully implement the investment fund’s strategy for a new business.
    3. Environmental, social and corporate governance (ESG) policies have become pervasive in all industries—especially within the energy industry—and must permeate all aspects of an investment fund’s strategy. Effective ESG policies and proper environmental stewardship have become licenses to operate within the energy industry and without them, operating companies and investment funds will have extremely limited ability to gain legitimate interest from potential investment partners.
    4. When developing a relationship between an investment fund and a management team for a new investment, it is critical for both parties to ensure there are aligned interests and expectations between the two parties.
    5. Investment funds see abundant opportunities within the energy transitions space and are bullish on those investments’ capability to satisfy energy demand over the next two to three decades but are also looking to achieve diversification to protect their limited partners from the cyclical nature of energy investment.

    To access past webinars in this series and to begin receiving Energy updates, including invitations to the webinar series, please click here.

    In depth

    The energy market has undergone significant change in the past 12 months, with even more on the horizon. Our webinar series explores how these changes have shaped—and will continue to impact—the energy industry, including discussions of what’s to come.

    Our latest webinar featured McDermott partners Edward Zaelke and Parker Lee, as well as Shawn Cumberland, Managing Partner of Energy Transition of EnCap Investments, and Alex Jackson, Director at Quantum Energy Partners.

    Below are key takeaways from the webinar:

    1. Although energy transition investment funds may have different focuses, they generally take an all-of-the-above approach, with respect to investing, in the various subsectors of the energy transition and are willing to invest in any technology, in any portion of the energy industry (except for highly capital intensive projects with binary risk profiles).
    2. Similar to the approach for conventional oil and gas investments, investment funds are focused on investing in strong management teams with a successful track record, which is manifested either through a management team that already has an interesting business plan or a management team that can successfully implement the investment fund’s strategy for a new business.
    3. Environmental, social and corporate governance (ESG) policies have become pervasive in all industries—especially within the energy industry—and must permeate all aspects of an investment fund’s strategy. Effective ESG policies and proper environmental stewardship have become licenses to operate within the energy industry and without them, operating companies and investment funds will have extremely limited ability to gain legitimate interest from potential investment partners.
    4. When developing a relationship between an investment fund and a management team for a new investment, it is critical for both parties to ensure there are aligned interests and expectations between the two parties.
    5. Investment funds see abundant opportunities within the energy transitions space and are bullish on those investments’ capability to satisfy energy demand over the next two to three decades but are also looking to achieve diversification to protect their limited partners from the cyclical nature of energy investment.

    To access past webinars in this series and to begin receiving Energy updates, including invitations to the webinar series, please click here.

    Authors

    Edward Zaelke

    Partner

    Los Angeles

    More insights

  • Federal Banking Regulators Update Guidance on Model Risk Management Practices for AML and Sanctions Compliance

    Federal Banking Regulators Update Guidance on Model Risk Management Practices for AML and Sanctions Compliance

    ARTICLE / CLIENT ALERT

    Federal Banking Regulators Update Guidance on Model Risk Management Practices for AML and Sanctions Compliance

    June 10, 2021

    Read time: 10 min

    Key takeaways
    Overview

    On April 9, 2021, the Federal Reserve, the FDIC and the OCC[1] jointly issued an interagency statement concerning the applicability of model risk management guidance on systems used to support Bank Secrecy Act/Anti-Money Laundering compliance programs (“2021 Interagency MRM Statement”).[2] The 2021 Interagency MRM Statement addresses certain concerns raised by industry members, namely that prior guidance concerning model risk management as applied to anti-money laundering (“AML”) and sanctions programs may inhibit the ability of the industry to adopt and deploy novel solutions to address AML and sanctions-related risks.

    Model Risks

    In 2011, the OCC and the Federal Reserve issued broad and comprehensive guidance for banks detailing what an effective model risk management framework should look like (“2011 MRM Guidance”).[3] The 2011 MRM Guidance defines models broadly to cover quantitative methods, systems or approaches that apply statistical, economic, financial or mathematical theories, techniques and assumptions to process data and model risk as the potential for adverse consequences from decisions based on incorrect or misused models.

    Under the 2011 MRM Guidance, a model typically involves three main components:

    1. An information input component, which delivers assumptions and data to the model;
    2. A processing component, which transforms inputs into estimates; and
    3. A reporting component, which translates the estimates into useful business information.

    While the model was broadly defined under the 2011 MRM Guidance, since its initial publication industry members have questioned how the risk management principles described therein should be applied to the systems and models used for AML and sanctions compliance. Industry members have also raised concerns that the application of novel approaches to data science to address AML and sanctions risk, such as machine learning, could be inhibited by an overly mechanical application of the risk management principles detailed therein.

    The 2021 Interagency MRM Statement

    In response to these concerns, federal banking agencies issued the 2021 Interagency MRM Statement, expressly reminding industry members that the 2011 MRM Guidance was provided as a guide to the benefits of implementing a model risk management framework and that the 2011 MRM Guidance did not, and does not, have the force and effect of law. Specifically, the 2021 Interagency MRM Statement attempts to provide additional certainty to industry members by explaining that:

    • Whether a system used specifically for AML is considered a “model” is an industry member-specific determination;
    • Industry members may use the 2011 MRM Guidance[4] to inform their AML practices, but are not obligated to do so in every case; and
    • Industry members that are currently effectively managing the risks of their AML and sanctions programs without relying on the 2011 MRM Guidance are not required to update existing practices.

    For example, the 2021 Interagency MRM Statement explains that most industry participants utilize automated transaction monitoring or AML surveillance systems to mitigate AML and sanctions risk or identify transactions for Suspicious Activity Reporting purposes. Simple tools that flag transactions on the basis of a single criterion (i.e., reports that identify cash, wire transfer or other transaction activity over certain value thresholds) or report aggregate cash transactions are not typically considered models for purposes of the 2021 Interagency MRM Statement.[5] More advanced, tools, however, should be evaluated on the basis of the three key criteria detailed in the 2011 MRM Guidance and based on the individual features of the AML and sanctions program. Regardless of whether an industry participant defines an automated transaction monitoring or AML surveillance system as a model, the 2021 Interagency MRM Statement reminds industry participants that the 2011 MRM Guidance is non-binding and no specific organizational structure is required for oversight. Specifically, the 2021 Interagency MRM Statement confirms that there is “no requirement or supervisory expectation that banks have duplicative processes for complying with BSA/AML regulatory requirements” and “no requirement that a bank perform duplicative independent testing activities.”

    Depending on the specifics of the models being utilized, banks should consider whether implementing the model risk management guidelines would be beneficial or burdensome to their individual AML program, as the ultimate goal of the model risk management guidance is to provide flexibility for banks in developing and implementing their models.

    Broker-dealers and other industry participants should be mindful of the guidance contained in the 2011 MRM Guidance and the 2021 Interagency Statement, as the SEC and FINRA may use these statements as a guidepost to evaluate the tools firms are relying on to comply with their BSA and AML obligations.

    This is part of a series of SRZ Alerts regarding AML and sanctions compliance. In addition to our robust Bank Regulatory practice, which advises financial institutions on anti-money laundering and OFAC compliance, SRZ has a Broker-Dealer Regulatory & Enforcement and White Collar Defense & Government Investigations practice that assists banks, broker-dealers, investment advisers, funds, insurance companies and other financial institutions with enforcement actions involving AML and sanction program deficiencies.

    Authored by Betty Santangelo, Melissa G.R. Goldstein, Derek N. Lacarrubba and J. Eric Prather.

    If you have any questions concerning this Alert, please contact your attorney at Schulte Roth & Zabel or one of the authors.


    [1] The interagency statement was prepared in consultation with the Financial Crimes Enforcement Network and the National Credit Union Administration.

    [2] Interagency Statement on Model Risk Management for Bank Systems Supporting Bank Secrecy Act/Anti-Money Laundering Compliance (April 9, 2021).

    [3] Supervisory Guidance on Model Risk Management (April 4, 2011).

    [4] The model risk management guidelines do not apply to credit unions, as it was not issued by the National Credit Union Administration.

    [5] 2021 Interagency MRM Statement at 3.


    This communication is issued by Schulte Roth & Zabel LLP for informational purposes only and does not constitute legal advice or establish an attorney-client relationship. In some jurisdictions, this publication may be considered attorney advertising. ©2021 Schulte Roth & Zabel LLP.

    All rights reserved. SCHULTE ROTH & ZABEL is the registered trademark of Schulte Roth & Zabel LLP.

    In depth
    Authors

    Betty Santangelo

    Counsel

    New York – 919 Third Avenue

    Melissa G.R. Goldstein

    Partner

    New York – 919 Third Avenue

    J. Eric Prather

    Associate

    New York – 919 Third Avenue

    More insights

  • SEC Chairman Requests Recommendations on Restricting Rule 10b5-1 Plans

    SEC Chairman Requests Recommendations on Restricting Rule 10b5-1 Plans

    ARTICLE / CLIENT ALERT

    SEC Chairman Requests Recommendations on Restricting Rule 10b5-1 Plans

    June 9, 2021

    Read time: 4 min

    Key takeaways
    Overview

    At a June 7, 2021, conference, Securities and Exchange Commission (SEC) Chairman Gary Gensler shared plans to “freshen up” Exchange Act Rule 10b5-1. He directed SEC staff to consider and recommend certain restrictions on the use of 10b5-1 trading plans.

    Corporate executives and insiders are frequently exposed to insider information, which can make it difficult for them to buy and sell company shares without the risk of insider trading. To address this problem, the SEC enacted the Rule 10b5-1 safe harbor. The rule allows corporate insiders—acting in good faith and while not in possession of material nonpublic information (MNPI)—to create a formal trading plan for future stock transactions. The use of a 10b5-1 plan provides an affirmative defense against allegations of insider trading.

    In depth

    During the conference, Chairman Gensler said he believes tightening restrictions on the use of 10b5-1 trading plans would increase investor confidence and ensure a level playing field in the market.

    Chairman Gensler discussed the following potential adjustments to Rule 10b5-1:

    • Establishing a four- to six-month “cooling-off” period before trading can occur under a new 10b5-1 plan. At present, 39% of plans begin trading within the first 60 days of establishing a 10b5-1 plan, according to figures cited by Chairman Gensler. He expressed concern that the lack of a cooling-off period is viewed by “some bad actors…as a loophole to participate in insider trading.”
    • Restricting the ability to cancel 10b5-1 plans. Currently, insiders may cancel 10b5-1 plans whenever they wish, even if they possess MNPI. SEC staff have been directed “to consider limitations on when and how plans can be canceled.” Chairman Gensler emphasized that even under the current rule, “cancelling or amending any 10b5-1 plans calls into question whether they were entered into in good faith. If insiders don’t act in good faith when using 10b5-1 plans, those plans will not offer them an affirmative defense (to insider trading).”
    • Mandating “more disclosure regarding the adoption, modification, and terms of 10b5-1 plans.” As it stands, there is no mandated public disclosure when a 10b5-1 plan is established.
    • Limiting the number of 10b5-1 plans an insider may adopt. There are currently no limits to the number of 10b5-1 plans that an insider can adopt. Chairman Gensler noted that “insiders might mistakenly think they have a ‘free option’ to pick amongst favorable plans as they please.”

    The forcefulness of Chairman Gensler’s remarks may also portend SEC Division of Enforcement inquiries into “good faith” factors, with the focus on whether plans have been entered into, amended or cancelled while in possession of MNPI. For example, a waiting period (e.g., 14-30 days) during which no trades can occur under the plan can help prevent the appearance that the person designed the plan as a cover for trades based on MNPI. SEC rulemaking often identifies the need for investor protection and enforcement actions that address perceived abuses; these abuses are often cited to support the need for regulatory action.

    As a prophylactic measure, we recommend that chief legal officers “freshen up” the review of their executives’ plan documentation and other compliance mechanisms.

    Authors

    Eric Orsic

    Partner

    Chicago

    Thomas P. Conaghan

    Partner

    Washington, DC, New York – One Vanderbilt Avenue

    More insights

  • Keep Your Friends Close, but Your Enemies Closer: Midstream-Midstream Commercial Deals in a Disciplined Upstream Operator Environment

    Keep Your Friends Close, but Your Enemies Closer: Midstream-Midstream Commercial Deals in a Disciplined Upstream Operator Environment

    ARTICLE / REPORT

    Keep Your Friends Close, but Your Enemies Closer: Midstream-Midstream Commercial Deals in a Disciplined Upstream Operator Environment

    June 9, 2021

    Read time: 2 min

    Overview

    In the US domestic upstream oil and gas market, 2021 has been all about consolidation and exploration and production (E&P) companies focusing on disciplined growth and asset optimization. One upshot of this more disciplined oil and gas environment is that it has created some strange bedfellows. Some midstream companies, who typically compete with one another for E&P customers, are working together.

    In depth
    Tabs
    More insights
    Endnotes

  • The Biden Labor Platform – The First 100 Days and Beyond | Key Takeaways for Union and Non-Union Employers

    The Biden Labor Platform – The First 100 Days and Beyond | Key Takeaways for Union and Non-Union Employers

    ARTICLE

    The Biden Labor Platform – The First 100 Days and Beyond | Key Takeaways for Union and Non-Union Employers

    June 8, 2021

    Read time: 2 min

    Key takeaways
    Overview

    Before the 2020 election, then US Presidential candidate Joe Biden vowed to be the “strongest labor president you have ever had.” And after a little more than 100 days, President Biden shows every sign of living up to his campaign promise.

    During this two-part webinar series, we discussed the potential significant labor policy changes impacting employees and independent contractors under the Biden Administration. 

    In part one, Ron Holland, Kristin Michaels, Abigail Kagan and Philip Shecter covered the Protecting the Right to Organize Act’s (PRO Act) sweeping effect on both the union and non-union employer landscape, as well as the evolving makeup and anticipated activism at the National Labor Relations Board.

    In part two, Ron, Ellen Bronchetti, Christopher Foster and Elvira Kras talked about labor and employment law changes through executive orders, the American Jobs Plan and anticipated labor and employment changes under Marty Walsh at the Department of Labor (DOL).

    In depth

    President Biden has taken a holistic approach to pushing his pro-labor agenda, using the bully pulpit to make pro-union statements, signing executive orders revealing that the creation of union jobs is one of the administration’s top priorities, coming out in support of pro-labor legislations—namely the Protecting the Right to Organize Act (PRO Act), and integrating labor into its policy proposals.

    Authors

    Elvira R. Kras

    Partner

    Los Angeles

    Abigail M. Kagan

    Partner

    New York – One Vanderbilt Avenue

    More insights

  • Government Contractor Pleads Guilty to Bid-Rigging and Procurement Fraud

    Government Contractor Pleads Guilty to Bid-Rigging and Procurement Fraud

    ARTICLE / CLIENT ALERT

    Government Contractor Pleads Guilty to Bid-Rigging and Procurement Fraud

    June 8, 2021

    Read time: 6 min

    Key takeaways
    Overview

    On June 7, 2021, as part of the US Department of Justice’s (DOJ) continuing commitment to prosecuting cases where the government is a victim, a government contractor pleaded guilty to one count of bid-rigging and one count of conspiracy to commit mail and wire fraud in connection with the DOJ’s ongoing investigation into public works contracts for the North Carolina Department of Transportation (NCDOT).

    Ohio-based Contech Engineered Solutions LLC (Contech) entered its plea of guilty before a federal judge in the US District Court for the Eastern District of North Carolina and was sentenced to pay a $7 million criminal fine. Contech was also ordered to pay an additional $1,533,988 in restitution to the NCDOT. Notably, the DOJ did not impose a term of probation on Contech because Contech agreed to improve its compliance program to prevent recurrence of anticompetitive conduct. Contech, however, is required to cooperate with the DOJ, including producing documents and making witnesses available for interviews or testimony.

    In depth

    Contech and its former executive were indicted in October 2020 on six counts of alleged bid-rigging, conspiracy to commit fraud and mail and wire fraud in connection with a decade-long conspiracy involving public works projects in North Carolina.

    This prosecution highlights the DOJ’s ongoing commitment to the Procurement Collusion Strike Force (PCSF) and its efforts to scrutinize public procurements and combat collusion and related fraud in government contracting.

    The PCSF has conducted extensive training of law enforcement officers and procurement officers, among others, to help identify scenarios and situations where collusion is more likely to occur. The PCSF is also utilizing data analytics to advance its investigations, building on technological advancements and more useable data sets to target and prosecute anticompetitive conduct.

    Importantly, the PCSF has recently doubled in size and has gone global just as the United States has approved unprecedented stimulus spending in response to the global COVID-19 pandemic and as the Biden administration is poised to approve a new infrastructure plan. The PCSF has provided tools that allow any individual to report suspected collusion via email or an online tip center. Enforcers’ renewed commitment to procurement collusion—coupled with increased government spending—will likely lead to more investigations and additional prosecutions in 2021.

    Contech, a manufacturer of aluminum and other products, conspired with its supplier in bidding on numerous NCDOT public works projects. According to the indictment, the former Contech executive would obtain (or direct his subordinate to obtain) the supplier’s total bid price in advance. Using that information, Contech then submitted bids to be intentionally higher than its supplier. The indictment also alleged that Contech submitted false certifications that its bids were competitive and free of collusion throughout the conspiracy.

    The indictment alleged bid-rigging between a manufacturer and its supplier, which is typically a vertical relationship and generally subject to the Rule of Reason rather than per se criminal analysis. Under the Rule of Reason, antitrust enforcers balance the anticompetitive effects of the conduct in question against the procompetitive benefits. Certain anticompetitive conduct, however, is so egregious that it is per se unlawful under the antitrust laws—meaning once the conduct is committed a violation is automatically incurred. There is no legal defense or business justification that can overcome per se unlawful conduct.

    The DOJ alleged the manufacturer and its supplier held themselves out as competitors when submitting the bids in question to the NCDOT for nearly a decade. In a motion to dismiss the indictment, Contech argued that this manufacturer-supplier relationship should control how the court should analyze the conduct, i.e., Rule of Reason rather than per se. In its opposition, the DOJ focused on the specific, alleged conduct present in the transactions before NCDOT. In those transactions, the DOJ alleged that the manufacturer and supplier were holding themselves out to the NCDOT as competitors and, as such, this was classic bid-rigging conduct subject to per se analysis. On March 15, 2021, the court denied Contech’s motion to dismiss and agreed with the DOJ that the alleged conduct would be considered under a per se, rather than Rule of Reason, analysis.

    This prosecution demonstrates that the DOJ is willing to aggressively investigate and prosecute competitor relationships that are traditionally examined under a Rule of Reason analysis and focus on the specific, alleged transaction(s) between vertical entities. Such prosecutions may be more common where joint venture or similar teaming agreements are not in place.

    Companies doing business with government agencies should expect increased scrutiny of procurement bids and the bid award process, and they should be attentive in ensuring compliance with antitrust and government procurement laws. This guidance applies whether the procurement represents 100% or 10% of an entity’s business and whether a company is based in the United States or is a US subsidiary of an international entity.

    Companies should also be mindful that the PCSF’s reach extends beyond its partner districts. Collusive conduct in the United States is subject to prosecution no matter where it occurs.

    Based on our recent experience with the PCSF, companies can minimize their risks in the following ways:

    • Carefully review and document any no-bid or high-bid decisions, and provide business justifications for such decisions;
    • Have counsel review any decisions to team and/or joint bid with other companies in advance;
    • Have counsel review any sub-contracting arrangements with other companies that bid (or regularly bid) on the same projects in advance;
    • Ensure bids are legitimate and pricing decisions are determined in good faith and without collusion;
    • Monitor the procurement process;
    • Understand the red flags of collusion (indicators, patterns and/or circumstances where collusion may exist) and other indicators that suggest to the government that additional scrutiny of the bid process is warranted;
    • Ensure your corporate compliance program is consistent with DOJ guidance and appropriately tailored to your company and industry; and
    • Regularly train procurement personnel on appropriate conduct with respect to competitors and the consequences of collusion.
    Authors

    Lisa P. Rumin

    Partner

    Washington, DC

    More insights