













ARTICLE
Fund finance: Why governance may be the next frontier for NAV facilities
July 1, 2026
Read time: 6 min
As part of London Hot Topics 2026, Polly O’Brien and Vlad Maly explored the rapid evolution of fund finance, the growing role of net asset value (NAV) facilities, and the governance considerations that are increasingly shaping the future of the market.
A few years ago, NAV finance was often viewed as a niche product used in specific circumstances by a relatively small group of market participants. Today, that picture looks very different.
As private markets continue to evolve, NAV facilities have become an increasingly important tool for managers seeking to enhance liquidity, support portfolio management, and create additional flexibility within fund structures.
As adoption accelerates, however, attention is increasingly shifting away from whether these facilities should be used and towards how they are governed.
From niche product to core infrastructure
The growth of NAV finance reflects broader structural changes across private markets. Longer holding periods, slower exits, and the continued expansion of evergreen and semi-liquid fund structures have all increased demand for flexible financing solutions.
Market commentary in 2026 has reinforced the same theme: As exit windows remain uneven and private equity portfolios continue to hold a large volume of unrealised assets, NAV loans are increasingly being used to bridge timing mismatches, support follow-on capital needs, and avoid premature sales of quality assets.
At the same time, the availability of institutional lending capital has expanded significantly, with banks, private credit funds, insurers, and other institutional capital providers becoming more comfortable underwriting diversified portfolios, asset-backed structures, and more bespoke collateral packages.
As a result, NAV facilities are increasingly being viewed as part of the core infrastructure supporting private markets rather than a specialist financing solution.
Understanding the evolution of fund-level leverage
Unlike subscription facilities, which rely on investor commitments, NAV facilities are secured against the underlying assets within a portfolio. This distinction is important because it shifts the focus from future capital commitments to the performance, valuation, and governance of the assets themselves.
As structures become more sophisticated, managers are increasingly using NAV facilities as a practical portfolio management tool rather than a narrow liquidity product.
In mature funds, these facilities can support follow-on investments, manage distributions, provide financing for continuation vehicles, facilitate portfolio optimisation, and address short-term liquidity needs without forcing an accelerated exit process.
This wide range of uses means that, for many managers, NAV facilities are becoming an integral part of the ordinary fund finance toolkit – including portfolio management, capital formation, and value preservation – rather than an exceptional response to financial stress.
Investor scrutiny is changing
One of the most notable developments discussed during London Hot Topics 2026 was the evolution of investor expectations.
Historically, investor conversations often focused on whether a manager used leverage. Today, investors are asking different questions, and those questions are more focused on governance, transparency, and alignment than on the mere existence of leverage.
Rather than treating fund-level leverage as a binary issue, investors increasingly want to understand how it is governed, what purpose it serves, how risks are monitored, how the facility interacts with the broader fund structure, and what protections exist for investors.
This reflects a more mature market in which limited partners (LPs) are becoming more familiar with NAV products, but also more demanding about valuation discipline, reporting, and the use of proceeds.
The discussion has become more sophisticated, reflecting the growing maturity of both the market and its participants.
Growth requires trust
Rapid growth inevitably attracts increased scrutiny.
Recent developments across the broader asset-backed lending and private credit markets have reinforced the importance of governance, collateral verification, and transparency.
In a NAV context, that means lenders and investors are paying closer attention to the quality of reported NAV, the reliability of portfolio valuations, the robustness of borrowing-base calculations, the treatment of asset-level debt, and the extent to which cash flows can be captured and applied through appropriate account and collateral arrangements.
As managers, lenders, and investors continue to embrace NAV finance, the long-term success of the market is likely to depend on maintaining confidence in valuation processes, collateral arrangements, and risk management frameworks.
The challenge is no longer simply accessing capital. It is ensuring that governance infrastructure develops alongside market growth.
Innovation continues
The discussion also highlighted several emerging trends likely to shape the future of the market.
Adoption is widening beyond the largest sponsors, while hybrid facilities that combine subscription-line and NAV-style features are becoming more prominent, particularly where funds need a financing solution that can evolve as a portfolio matures.
At the same time, insurance capital and other institutional capital sources are becoming more active, and lenders are developing more sophisticated collateral structures to address concentrated portfolios, continuation vehicles, credit funds, and other asset class-specific requirements.
As the market evolves, managers are likely to have access to an increasingly diverse range of financing options, but the most successful structures are likely to be those that match the financing purpose, collateral package, and governance framework to the maturity and composition of the relevant fund portfolio.
Looking ahead
The NAV finance market has moved far beyond its origins as a specialist financing product.
Today, it plays an increasingly important role within the private markets ecosystem and is likely to continue expanding as managers seek greater flexibility in managing portfolios, financing longer hold periods, and responding to investor expectations around liquidity and transparency.
The next phase of growth, however, may depend less on innovation for its own sake and more on governance.
As adoption increases, managers, lenders and investors will all need confidence that valuation, collateral, and risk management frameworks can evolve alongside the market itself.
In that sense, the central question for 2026 is not whether NAV finance will remain relevant, but whether the market can continue to scale in a way that preserves trust, supports responsible liquidity management, and gives investors a clear understanding of how fund-level leverage is being used.
Continue the conversation
If you would like to discuss any of the issues highlighted above, please reach out to Polly O’Brien, Vlad Maly, or your usual McDermott Will & Schulte contact.


Structuring smart: Why liquidity management starts long before a crisis
ARTICLE
Structuring smart: Why liquidity management starts long before a crisis
July 1, 2026
Read time: 5 min
Watch panel video here, if helpful.
Liquidity is often discussed as a crisis management issue. In reality, effective liquidity management begins long before markets become volatile.
During London Hot Topics 2026, Christopher Hilditch and Amy MacDonagh explored how fund managers can build resilient liquidity frameworks that protect both portfolios and investor relationships. Their discussion highlighted a simple but important principle: The most effective liquidity tools are those that are carefully designed before they are ever needed.
Start with the portfolio, not investor demands
When designing liquidity terms, managers can face competing pressures from investors, peers, and market expectations. However, the discussion emphasised that liquidity terms should always be driven by the underlying portfolio and investment strategy.
A common challenge arises when liquidity terms fail to reflect the reality of the assets being managed. While offering investors frequent redemption rights may appear attractive during fundraising, problems can emerge if those assets cannot realistically be liquidated within the required timeframe.
As the panel noted, funds rarely encounter difficulties because of a single market event. More often, challenges arise when the liquidity profile of the portfolio becomes misaligned with the terms offered to investors.
Managers should therefore ask two key questions:
- How quickly can assets realistically be sold or rebalanced?
- Does the strategy require additional protections such as lock-ups, gates, or other liquidity controls?
Addressing these questions early can help prevent difficult conversations later.
Preserving optionality matters
Periods of market stress test every aspect of a fund’s liquidity framework.
While no manager expects to rely on emergency powers when launching a fund, the panel emphasised the importance of preserving optionality through carefully drafted fund documentation.
Examples discussed included:
- Fund-level gates;
- Suspension rights;
- Redemption-in-kind provisions;
- Slow-pay mechanisms; and
- Alternative distribution structures.
These tools serve different purposes and should not be viewed as interchangeable.
A fund-level gate, for example, can slow redemption activity and support orderly portfolio management. Redemption-in-kind provisions may help preserve value by avoiding forced sales. Suspension rights can provide breathing room in exceptional circumstances.
The key message was clear: Managers should resist the temptation to negotiate away important protections simply to accommodate investor requests during fundraising.
Terms that appear unnecessary during favourable market conditions can become critical when liquidity pressures emerge.
Governance and judgment are just as important as documentation
One of the strongest themes from the discussion was that liquidity management is not solely a legal or operational exercise.
The effectiveness of any liquidity framework ultimately depends on the quality of decision-making and governance surrounding it.
Even well-designed liquidity tools can create challenges if they are used too early, too late or without a clear rationale.
Acting too quickly may signal distress and accelerate redemption activity. Acting too slowly can result in value destruction and a loss of control.
The panel highlighted the importance of:
- Active board engagement;
- Clear escalation processes;
- Independent challenge and oversight;
- Consistent decision-making; and
- Early involvement of advisors, where appropriate.
Strong governance helps ensure that managers can act decisively when required, while maintaining confidence among investors and other stakeholders.
Communication remains critical
Perhaps the most important takeaway from the session was that liquidity events are often communication challenges as much as they are financial or legal ones.
Too much information can create instability. Too little information can undermine trust.
As a result, managers must balance the need for transparency with the need to avoid creating unnecessary concern among investors.
Communication should begin internally, ensuring that boards, advisors, and key stakeholders are aligned before engaging with investors. When communicating externally, messages should be clear, consistent, and proportionate to the circumstances.
The discussion reinforced that maintaining investor confidence during periods of stress often depends on the quality of communication as much as the underlying liquidity tools themselves.
Looking ahead
As markets continue to evolve, liquidity management remains a core component of fund resilience.
Managers who take the time to align liquidity terms with their investment strategy, preserve optionality through appropriate structures and tools, and maintain strong governance frameworks will likely be better positioned to navigate future periods of market uncertainty.
Liquidity management is ultimately about more than protecting portfolios: It is about protecting investor confidence and ensuring that funds can continue to operate effectively through both calm and challenging market conditions.
Continue the conversation
If you would like to discuss any of the themes highlighted above, please reach out to Christopher Hilditch, Amy MacDonagh, or your usual McDermott Will & Schulte contact.
London Hot Topics 2026: Five themes shaping the investment management landscape
ARTICLE
London Hot Topics 2026: Five themes shaping the investment management landscape
July 1, 2026
Read time: 6 min
London Hot Topics 2026 brought together fund managers, investors and advisers to discuss some of the most pressing issues currently shaping the investment management industry.
While discussions ranged from liquidity management and fund finance to tax, regulation and investor relations, several common themes emerged throughout the day. Together, they paint a picture of an industry that continues to evolve rapidly while facing increasing demands for transparency, governance and flexibility.
Below are five themes that stood out.
1. Governance is becoming a competitive advantage
One theme surfaced repeatedly throughout the event: governance.
Whether discussing liquidity management, valuations, fund finance, regulatory compliance or investor relations, speakers consistently highlighted the importance of robust governance frameworks and effective decision-making.
The conversation reflected a broader market shift. Governance is no longer viewed solely as a compliance requirement. Increasingly, it is becoming a key differentiator for managers seeking to build investor confidence, navigate complexity and demonstrate resilience in challenging market conditions.
As regulatory scrutiny continues to evolve and investors ask more sophisticated questions, firms that can demonstrate strong governance and well-documented decision-making processes are likely to be better positioned for long-term success.
2. Liquidity management requires preparation, not reaction
Liquidity remains a critical consideration for fund managers, particularly in an environment where market conditions can change rapidly.
Speakers stressed the importance of ensuring that liquidity terms are aligned with the underlying investment strategy and portfolio characteristics. Rather than designing terms around investor expectations or market convention, managers should ensure that redemption rights, lock-ups and other liquidity provisions reflect the realities of the assets being managed.
The discussion also highlighted the importance of preserving optionality through mechanisms such as gates, suspensions and redemption-in-kind provisions. These tools are often negotiated during periods of calm but become most valuable during periods of stress.
Perhaps most importantly, the panel emphasised that effective liquidity management is not solely about legal documentation. Communication, governance and stakeholder management remain essential to maintaining investor confidence when markets become more challenging.
➜ Read more: Structuring smart: managing liquidity constraints – learn what’s changing and why
Christopher Hilditch and Amy MacDonagh
3. Fund finance is moving into the mainstream
Fund finance continues to evolve, with NAV facilities increasingly becoming part of the core infrastructure of private markets.
What was once considered a niche financing solution is now being used more broadly to support portfolio management, liquidity planning and capital efficiency. Speakers noted that the market has expanded significantly in recent years and continues to attract growing interest from both managers and lenders.
At the same time, the discussion highlighted that rapid growth inevitably brings increased scrutiny. Investors are no longer simply asking whether fund-level leverage is being used; they are increasingly focused on how it is governed, monitored and disclosed.
As the market matures, governance, collateral verification and transparency are likely to become just as important as access to financing itself.
Polly O’Brien and Vlad Maly
4. Opportunity remains, but complexity is increasing
Across both the tax and regulatory discussions, speakers highlighted a common theme: opportunities continue to exist, but navigating them requires careful planning.
The UK continues to signal its support for the investment management sector through a range of tax and regulatory reforms designed to simplify certain aspects of the operating environment. At the same time, managers must continue to navigate evolving requirements relating to carried interest, investment manager exemptions and broader compliance obligations.
Similarly, discussions around sanctions, cryptoassets, tokenisation and retailisation demonstrated that innovation is creating new opportunities for growth. However, these opportunities are accompanied by increasingly complex legal, regulatory and operational considerations.
For managers, the challenge is not simply identifying opportunities but ensuring they have the governance frameworks and expertise necessary to pursue them effectively.
Nick Fagge and Elizabeth Spencer
Christopher Avellaneda and Karen Butler
5. Investor alignment is driving product innovation
In a challenging fundraising environment, investor expectations continue to evolve.
Speakers observed that investors are increasingly seeking customised solutions, greater transparency and structures that more closely align with their specific objectives. As a result, managers are responding with innovative approaches to product design, including dislocation funds, co-investment vehicles, customised share classes and increasingly sophisticated side letter arrangements.
The discussion highlighted that successful fundraising is no longer driven solely by investment performance. Managers are increasingly differentiating themselves through creativity, flexibility and a willingness to tailor solutions to investor needs.
Ultimately, alignment is becoming a strategic advantage, helping managers attract capital, strengthen relationships and build long-term investor confidence.
➜ Read more: Aligning with your investors: managed accounts, expenses and side letters
Josh Dambacher and Lee Smith
Looking ahead
The discussions at London Hot Topics 2026 highlighted an industry that continues to adapt to changing market conditions, evolving regulation and increasingly sophisticated investor expectations.
While each panel focused on different challenges, a common theme emerged: the firms best positioned for success will be those that combine strong governance with flexibility, innovation and a clear understanding of investor needs.
As the investment management landscape continues to evolve, these themes are likely to remain firmly on the agenda in the months ahead.
Continue the conversation
If you would like to discuss any of the themes highlighted above, please reach out to your usual McDermott Will & Schulte contact or a member of our Investment Management team.

Five things to know about the new value equation for outpatient services
ARTICLE
Five things to know about the new value equation for outpatient services
June 30, 2026
Read time: 7 min
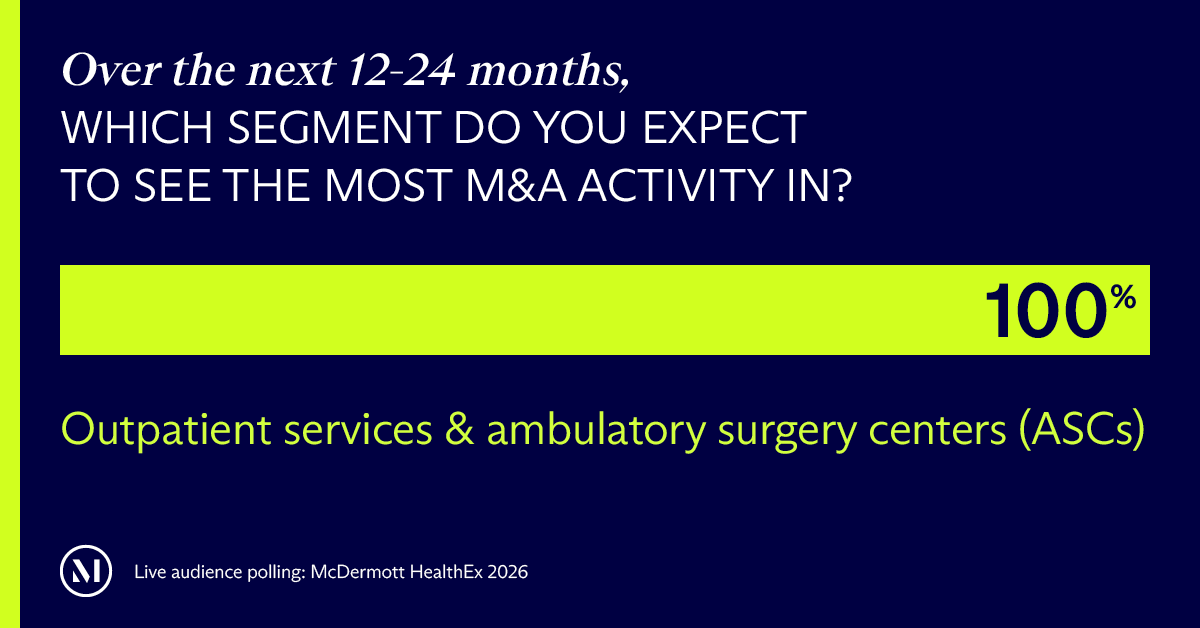
The healthcare services market is entering a new phase of development, according to discussions at McDermott HealthEx 2026. Site-of-care migration continues to drive growth across physician practice management (PPM) platforms, ambulatory surgery centers (ASCs), and outpatient services, creating a host of new transaction opportunities and evaluation priorities.
Successful M&A strategy is no longer about simply building scale. It’s about converting scale into stronger margins, better operational performance, and long-term sustainable value.
Below are the hot trends and takeaways from McDermott HealthEx to guide the next phase of outpatient services growth and dealmaking strategies for ASCs and PPMs.
What buyers want
Buyers are paying closer attention to earnings durability and execution quality in the face of a more selective exit environment, persistent reimbursement pressures, regulatory enforcement at state and federal levels, and rising operating costs. They are spending less time underwriting acquisition opportunities and more time evaluating whether a platform can expand margins, recruit physicians, integrate operations, and sustain performance – without relying on additional M&A.
Fragmentation across many specialties continues to create opportunities for consolidation, but aggregation alone no longer commands the same premium. Investors want to understand what sits beneath the roll-up strategy. The strategy discussion has moved from “Can this platform grow?” to “What happens when growth slows?”
This shift in thinking is influencing valuation, diligence, and value creation plans. Revenue growth remains critical, but the ability to demonstrate margin durability, operational consistency, and scalable infrastructure carries just as much weight.
Outpatient services help health systems stand out
Hospital outpatient revenue growth now outpaces inpatient revenue growth by nearly double, and that has changed the game for health systems. Physician partnerships, ambulatory platforms, and outpatient networks are increasingly tied to a health system’s long-term competitive positioning and financial performance, especially as patients gain access to better tools to find and compare care options.
To expand capabilities and enter new markets, it’s not all about traditional acquisitions. Health systems are leaning on joint ventures, shared governance structures, and other collaborative arrangements. The structure of the partnership often matters less than other fundamentals, including governance design, clinical integration, cultural compatibility, and operational alignment post-close.
Physicians have to be on board
Platform executives are looking beyond acquisition volume to other dealmaking considerations crucial for success. Chief among them is physician alignment, along with workforce strategy, productivity, and leadership development potential. Investors are responding accordingly, knowing that compensation structures, governance frameworks, and clinical autonomy all have an influence on physician recruitment, workforce retention, and long-term organizational performance.
For buyers, physician alignment has become a core diligence issue because it often serves as a leading indicator of future execution. Valuation discussions must extend well beyond market density and growth rates. Buyers want evidence that management teams can convert scale into stronger financial performance, more efficient operations, and sustainable enterprise value – an evolution that’s particularly evident across mature PPM platforms.
The strategic emphasis has shifted from simply building physician networks to optimizing them by:
- Improving physician workflows and productivity
- Strengthening ancillary service utilization
- Enhancing patient access and market presence
- Investing in better digital services and engagement tools
- Creating operating leverage across the enterprise
Regulatory strategy is enterprise strategy – not just compliance
Regulators at the state and federal levels have their eyes on the healthcare services market. State transaction review laws, ownership disclosure requirements, evolving reimbursement policies, and heightened scrutiny of healthcare consolidation are influencing transaction structures, diligence processes, and execution timelines in the space.
Medicare, Medicaid, site-of-care reimbursement policies, and value-based reimbursement models are shaping strategic decisions far beyond the compliance function. Growth initiatives, partnership strategies, market expansion plans, and capital deployment decisions increasingly require an assessment of reimbursement and regulatory risk at the outset rather than later in the process.
Organizations that incorporate those considerations into strategic planning are generally better positioned to preserve value and avoid execution surprises while navigating an increasingly complex transaction environment.
Key considerations for outpatient services transactions
With these trends in mind, outpatient service operators, investors, and strategic buyers should evaluate dealmaking strategies and transaction processes according to a few key considerations.
For PPM and ASC operators:
Revenue cycle performance, labor productivity, physician recruitment and retention, payor strategy, and operational standardization are becoming more important drivers of enterprise value.
For investors, strategic buyers, and lenders:
Leadership depth, physician alignment, revenue cycle performance, and integration readiness increasingly influence valuation and post-close performance.
Looking ahead
The next phase of outpatient services growth and dealmaking activity is unlikely to be defined by consolidation. The organizations that distinguish themselves over the next several years will be those that convert scale into stronger operating performance, pair growth with disciplined execution, and build platforms capable of performing across a more demanding reimbursement and regulatory landscape.
Family Office Symposium 2026 | Key takeaways
ARTICLE
Family Office Symposium 2026 | Key takeaways
May 6 – 7, 2026
Read time: 11 min
McDermott Will & Schulte’s Family Office Symposium 2026 brought together more than 425 single-family office executives and industry leaders for insightful conversations, shared perspectives, and meaningful connections.
Explore the key insights and strategies shared across each session below.
Panelists explored how AI is transforming industries – from legal services to financial services to venture capital – with a focus on practical AI applications already delivering results, evaluating talent and investment opportunities in a crowded market, and building enduring firms in an era of rapid technological change.
Top takeaways included:
- Building a firm or enterprise that can last for more than 100 years means creating layered, competitive moats, a platform culture with autonomy, and a team-based winning mentality – not top-down control. Brand, reputation, and collective decision-making (“delegated conviction, group tackle”) are the lasting differentiators.
- The most interesting AI opportunities are emerging at the crossroads of fields, not within any single discipline. Geographic dispersion is also real: while capital remains concentrated in the United States, AI companies are now being built broadly across the globe – a meaningful shift from prior technology cycles.
- The market opportunity for AI companies is larger than most people appreciate – and growing faster. AI isn’t just competing for IT budgets; it’s going after labor spend. The US nurse labor market is over $600 billion annually. The dedicated software market for nurses is close to zero. That gap – enormous labor cost, almost no software to address it – exists across hundreds of verticals. AI is the first technology capable of closing it.



















Global ABS 2026: five themes shaping the structured finance market
ARTICLE
Global ABS 2026: five themes shaping the structured finance market
June 18, 2026
Read time: 8 min
Members of our structured finance team, including Priya Taneja, Stuart Axford, Martin Sharkey, Giacomo Bertolissi and Amber Chak, attended Global ABS 2026 in Barcelona.
While conversations at the conference spanned multiple asset classes and jurisdictions, five themes consistently emerged.
- Private credit continues to reshape funding markets, with back-leverage structures becoming increasingly central.
- Regulatory reform remains a factor for securitisation market activity.
- The Significant Risk Transfer (SRT) market is entering a new phase of maturity.
- Double-pledging is now a risk that investors are very much alive to, with technology aided transparency being regarded by some as the answer
- Data centres are moving from infrastructure story to structured finance asset class.
What this means for market participants
The discussions at Global ABS 2026 highlighted several trends with practical implications for issuers, investors, and financial institutions:
- Private credit is becoming an increasingly important source of capital across structured finance and specialty finance markets, with back-leverage structures increasingly central to how private capital managers scale, diversify, and optimise their funding.
- Regulatory developments will continue to influence transaction structuring, capital efficiency, and investor demand.
- The SRT market is becoming more sophisticated, creating opportunities for both financial institutions and investors.
- Credit quality, transparency, and structural protections remain central to investment decision-making.
- Innovation is creating new opportunities across asset classes, but risk management remains critical to execution.
- Financing providers will increasingly seek real-time transparency, robust data integrity, and governance around pledged assets, in order to mitigate multi-pledging risk. For market participants, the ability to connect legal, regulatory, financing, and commercial considerations is likely to become increasingly important as markets continue to evolve.
For market participants, the ability to connect legal, regulatory, financing, and commercial considerations is likely to become increasingly important as markets continue to evolve.
Looking ahead
The overall mood at Global ABS 2026 was constructive, and the buzz phrase seems to be “cautious optimism”. While economic and regulatory challenges remain, the market continues to demonstrate resilience, innovation, and a willingness to adapt to changing conditions.
The themes discussed throughout the conference are likely to remain at the forefront of the structured finance market throughout the year and will continue to influence how market participants raise capital, manage risk, and pursue growth opportunities, including through the continued growth of private credit and back-leverage structures.
Continue the conversation
If you would like to discuss any of the themes highlighted above, or explore how these developments may affect your business, please reach out to your usual McDermott Will & Schulte contact, or a member of our structured finance team, including Priya Taneja, Stuart Axford, Martin Sharkey, Vlad Maly, Giacomo Bertolissi and Amber Chak.
We would be delighted to continue the conversation.


IRS roundup: June 10 – June 21, 2026
ARTICLE
IRS roundup: June 10 – June 21, 2026
Jun 23, 2026
Read time: 6 min
Check out our summary of significant Internal Revenue Service (IRS) guidance and relevant tax matters for June 10, 2026 – June 21, 2026.
June 9, 2026: A Treasury Inspector General for Tax Administration (TIGTA) report found that the IRS lost a significant number of experienced employees during the workforce reductions and voluntary departures that occurred in the first year of the second Trump administration. Approximately 40% of departing employees had more than 11 years of experience while another 45% had between one and 11 years of service, raising concerns about the loss of institutional knowledge and expertise within the agency.
The report also noted that the IRS has redirected personnel to maintain taxpayer service operations, including hiring approximately 2,000 customer service representatives and tax examiners and detailing more than 1,100 employees from other divisions to assist with return processing. TIGTA observed that many reassigned employees retained higher-grade salaries while performing lower-grade taxpayer service duties and announced a separate review examining the impact of these resource reallocations on IRS operations and enforcement activities.
June 10, 2026: The IRS issued Notice 2026-39, updating the list of qualifying energy communities for purposes of the bonus credit amounts and rates available under Internal Revenue Code (Code) §§ 45, 45Y, 48, and 48E. The notice provides updated county and census tract information for the Statistical Area and Coal Closure Categories, reflecting 2025 unemployment data, newly identified coal mine closures, and coal-fired electric generating unit retirements.
The updated designations determine whether eligible clean energy projects qualify for enhanced energy community bonus credits. The notice also provides revised appendices identifying qualifying counties, metropolitan and non-metropolitan statistical areas, and census tracts, with the updated energy community status generally effective beginning June 10, 2026.
June 13, 2026: US Department of the Treasury officials announced that forthcoming proposed regulations under Code § 987 will allow certain controlled foreign corporations to make an election to not compute foreign currency gains and losses for their qualified business units and that the election may be made on amended 2025 tax returns. The election was first outlined in Notice 2026-17 and is intended to simplify compliance with the complex § 987 foreign currency rules.
The Treasury indicated that taxpayers will be given additional time to decide whether to make the election, but the election must be made within a reasonable period rather than years later. The proposed regulations are intended to reduce compliance burdens, simplify the operation of the § 987 regime, and limit the application of certain rules to routine business transactions involving US-owned foreign corporations.
June 15, 2026: The IRS issued Revenue Ruling 2026-12, providing the applicable federal rates (AFRs) for July 2026, including short-, mid-, and long-term rates under Code § 1274; adjusted AFRs under § 1288; and rates relevant to §§ 382, 42, 7520, and 7872. The ruling sets the § 7520 rate at 5.20% and the adjusted federal long-term rate under § 382 at 3.77%.
The ruling also provides the low-income housing credit percentages for July 2026, including an 8.09% rate for the 70% present value credit and 3.47% for the 30% present value credit, along with monthly AFR tables used in various federal tax valuation, financing, and transfer pricing calculations.
The IRS also released its weekly list of written determinations (e.g., Private Letter Rulings, Technical Advice Memorandums, and Chief Counsel Advice).
Recent court decisions
June 16, 2026: In Smith v. Commissioner, T.C. Memo. 2026-50, the US Tax Court held that an architectural firm was entitled to partial research credits under Code § 41 for certain large-scale sustainable building projects, rejecting the IRS’s argument that the research was entirely excluded as funded research. The Court concluded that although payments under all six project contracts were not contingent on the success of the research, the firm retained substantial rights in four of the six projects, including rights to use or exploit the resulting designs and intellectual property. As a result, the firm could claim reduced research credits under the funded-research allocation rules of Treasury Regulation § 1.41-4A(d)(3).
The opinion is notable for its consideration of the taxpayer’s argument that the Treasury’s funded-research regulations improperly added the “contingent on success” and “substantial rights” requirements to § 41(d)(4)(H) and that those criteria were therefore invalid under Loper Bright. The Court upheld these criteria, holding that Loper Bright did not undermine prior precedents and emphasizing both statutory stare decisis and the persuasive weight of the Treasury’s long-standing interpretation. The Court further held that the firm’s partners’ compensation was reasonable under § 174(e), applying the US Court of Appeals for the Seventh Circuit’s independent investor test and finding that the extraordinarily high returns generated for the firm supported the compensation amounts claimed.
June 17, 2026: In Novak v. Commissioner, T.C. Memo. 2026-52, the Tax Court granted summary judgment to the IRS, holding that the IRS Independent Office of Appeals (IRS Appeals) did not abuse its discretion in sustaining a federal tax lien and rejecting the taxpayer’s request for an installment agreement. The taxpayer owed more than $1.7 million in additional tax and interest for 2017 – 2019 and had previously reported substantial assets, including tens of millions of dollars in stock and significant real estate equity. IRS Appeals repeatedly requested updated financial information after the taxpayer claimed his circumstances had changed, but the requested documentation was never provided.
The taxpayer argued that the lien was filed before his installment agreement was formally rejected and that the IRS failed to satisfy certain notice requirements. The Court rejected those arguments, finding that the IRS properly verified compliance with applicable procedures, timely issued the lien notice, and followed Internal Revenue Manual guidance permitting the filing of a notice of federal tax lien while an installment agreement request is pending. The Court emphasized that IRS Appeals may reject a collection alternative when a taxpayer fails to provide requested financial information and when the record indicates the taxpayer has sufficient assets to satisfy the liability. Accordingly, the lien filing was sustained, and the proposed installment agreement was properly denied.


IRS roundup: May 29 – June 8, 2026
ARTICLE
IRS roundup: May 29 – June 8, 2026
Jun 15, 2026
Read time: 6 min
Check out our summary of significant Internal Revenue Service (IRS) guidance and relevant tax matters for May 29, 2026 – June 8, 2026.
May 29, 2026: The US Department of the Treasury and the IRS issued additional guidance on the applicability dates of proposed regulations under Internal Revenue Code (IRC) § 892, which governs the tax exemption for certain income earned by foreign governments and sovereign wealth funds from passive US investments. The guidance responds to stakeholder comments by providing both grandfathering protection for existing investments and transitional relief before the proposed rules become final.
Under the guidance, existing foreign government interests generally would not become subject to the final regulations, and affected investors will have at least 90 days after publication of the final regulations or until the beginning of the first taxable year following publication to come into compliance. The Treasury and the IRS stated that the changes are intended to provide certainty for current investments, preserve established market practices, and support continued sovereign investment in the United States.
June 1, 2026: The Treasury and the IRS issued proposed regulations that would increase the user fee for obtaining an estate tax closing letter from $56 to $76. The agencies explained that a recent cost study determined the full cost of processing and issuing these letters exceeds the current fee and that the increase is intended to satisfy federal user-fee requirements that services provided to specific taxpayers be self-sustaining.
The proposed regulations provide that the increased fee would apply to requests received 30 days after publication of the final regulations. The Treasury and the IRS estimate that the higher fee reflects updated labor, quality review, and overhead costs associated with processing approximately 8,000 estate tax closing letter requests annually.
June 3, 2026: Following US President Donald Trump’s executive order creating a new Schedule Policy/Career employment category, the IRS and IRS Office of Chief Counsel identified several career positions that may be reclassified, including senior advisers, program managers, human resources specialists, attorney-advisers, and senior legal counsel positions. Employees placed in the new category will lose certain long-standing civil service protections and could be removed more easily than traditional career employees.
The Trump administration stated that the changes are intended to increase accountability and facilitate the removal of employees for poor performance or misconduct. Critics, including unions and former IRS officials, contend that the reclassification could undermine workforce stability, make recruitment more difficult, and increase concerns about political influence over tax administration and enforcement.
June 4, 2026: The Treasury and the IRS indicated that guidance on clean energy tax credit restrictions enacted by the One Big Beautiful Bill Act is expected in the third quarter of 2026. The guidance is expected to address the new prohibited foreign entity rules, which limit eligibility for certain clean energy credits when projects rely on financing, supplies, components, or contractual relationships involving entities connected to designated foreign countries such as China and Russia.
Treasury officials stated that the guidance will provide additional clarity on the implementation of these restrictions, which have become a significant concern for renewable energy developers and investors. The rules build on interim guidance issued earlier this year regarding the material assistance provisions and are expected to play a key role in determining continued access to clean energy tax incentives.
The IRS also released its weekly list of written determinations (e.g., Private Letter Rulings, Technical Advice Memorandums, and Chief Counsel Advice).
Recent court decisions
May 27, 2026: In Flight Options, LLC v. United States, the US Court of Appeals for the Sixth Circuit held that the federal 7.5% air transportation excise tax under 26 U.S.C. §§ 4261 and 4262 applies only to flight-specific usage fees charged by a fractional aircraft ownership company and not to its fixed management and overhead fees. Reversing a $39 million judgment against Flight Options, the Court concluded that the statutory “ticket tax” applies to amounts paid for specific air transportation rather than broader charges associated with owning and operating an aircraft.
The Court emphasized that neither the statute nor IRS guidance clearly required collection of the excise tax on fixed management fees and relied heavily on the principle that taxpayers and third-party tax collectors must receive “precise and not speculative” notice of tax obligations. The Court also rejected the IRS’s position that all costs “reasonably necessary” for air transportation are taxable, finding that the agency never provided a workable standard for determining which fixed costs qualified as payments “for transportation.”
May 29, 2026: In Leigh v. United States, a federal magistrate judge recommended allowing a taxpayer’s 26 U.S.C. § 7433 wrongful collection claim to proceed. The taxpayer alleged that the IRS improperly certified his tax debt as “seriously delinquent” to the US Department of State after he timely requested a Collection Due Process (CDP) hearing, which should have suspended collection activity. The court concluded that the allegations plausibly stated a claim for damages based on violations of IRC §§ 6330 and 7345, including the taxpayer’s alleged inability to renew his passport and related economic harm.
The court, however, recommended dismissal of separate claims challenging the IRS’s handling of a 2017 tax liability, finding that those allegations concerned the assessment of tax liability rather than collection activity and therefore fell outside the limited waiver of sovereign immunity under IRC § 7433. The decision emphasizes the distinction between actionable procedural violations in tax collection and nonactionable disputes over the correctness of tax assessments.
June 4, 2026: In Paschall v. Commissioner, T.C., the US Tax Court held that cryptocurrency staking rewards are taxable upon receipt when the taxpayer obtains dominion and control over the tokens. The Court sustained the IRS’s determination that the taxpayers failed to report $33,354 of Cardano staking rewards received via the eToro platform in 2021, concluding that the rewards constituted an accession to wealth includible in gross income under 26 U.S.C. § 61.
Rejecting the taxpayers’ arguments that staking rewards should be taxed only upon sale, the Court found that the taxpayers had unrestricted ability to sell the rewarded tokens and therefore exercised sufficient dominion and control over them when credited to their account. The Court also declined to analogize staking rewards to nontaxable stock dividends or self-created property, emphasizing that the rewards increased the taxpayers’ ownership interest and value in the cryptocurrency and were received in exchange for validating blockchain transactions.
Trending in Telehealth: May 2026
ARTICLE
Trending in Telehealth: May 2026
Jun 12, 2026
Read time: 9 min
Trending in Telehealth highlights monthly state legislative and regulatory developments that impact the healthcare providers, telehealth and digital health companies, pharmacists, and technology companies that deliver and facilitate the delivery of virtual care.
Trending in May:
- Teledentistry practice standards
- Establishment of provider-patient relationships through telehealth
- Veterinary telemedicine
A CLOSER LOOK
Proposed legislation and rulemaking:
- The Delaware Board of Veterinary Medicine proposed new requirements for the use of telemedicine in the practice of veterinary medicine. The regulation would require a veterinarian seeking to provide telemedicine services to hold a current and active Delaware license and to have an established veterinarian-client-patient relationship (VCPR). It would allow licensed Delaware or out-of-state veterinarians to provide telemedicine services for general advice, triage and emergency animal care in urgent instances, and provider-to-provider counseling. The regulation would require records of telemedicine care to be kept in accordance with the Delaware Veterinary Practice Act and would clarify that a person providing veterinary services by telemedicine is subject to the professional standard of care that would apply to the provision of the same services in an in-person setting.
- The West Virginia Board of Dentistry proposed to amend an existing rule on teledentistry to remove the definition of “established patient” and details regarding the establishment of such relationship that conflict with the statutory requirements set forth at W. Va. Code §§ 30-4-8b. The regulation would also permit store-and-forward technologies to be used in the performance of teledentistry and would require dentists who deliver teledentistry services to provide health records to the patient or a dentist on record upon patient request within 10 days.
- The Arkansas Psychology Board proposed amendments to its rules, including rules governing the practice of telepsychology, by adding “psychological practitioners” to the types of professionals to whom the standards apply.
- In Louisiana, SB 30 passed both houses and was sent to the governor. If enacted, it would prohibit the Louisiana State Board of Medical Examiners and the Louisiana State Board of Nursing from adopting or enforcing any rule or policy that would prohibit or restrict a licensed healthcare provider from using telehealth to evaluate, diagnose, or treat obesity or provide weight management services as long as the provider conducts a synchronous interaction with the patient and acts within the scope of his or her license and applicable standard of care.
- Also in Louisiana, SB 222 passed both houses and was sent to the governor. The legislation is part of a broader revision of Medicaid behavioral services in the state and would require the Louisiana Department of Health to submit to the Centers for Medicare & Medicaid Services (CMS) no later than October 1, 2026, any necessary state plan amendment, waiver, or other request to authorize reimbursement for psychosocial rehabilitation services delivered via telehealth and to notify the committees on health and welfare within 30 days of the submission to CMS. Notice to the committees would also be required within 30 days if CMS requests additional information or denies the submission.
- SB 3506 passed both houses in Illinois. If enacted, it would amend the Sexual Assault Survivors Emergency Treatment Act. Beginning on January 1, 2028, a treatment hospital, treatment hospital with approved pediatric transfer, or approved pediatric health care facility would be allowed to submit, in addition or as an addendum to its sexual assault treatment plan or an areawide sexual assault treatment plan, a plan for the use of a TeleSANE interactive telecommunications system, which allows a qualified medical provider to precept a medical forensic examination while located at a distant site.
- SB 3211, which concerns teledentistry, also passed both houses in Illinois. If enacted, it would allow the initial examination for new patients, excluding patients seeking orthodontic treatment, to be conducted through teledentistry if the authorizing dentist establishes a bona fide dentist-patient relationship by reviewing the patient’s medical and dental history and verifying both the patient’s identity and physical location to ensure that dental care is being administered within the state. It would require initial examinations for orthodontia treatment to be performed in person and would require an in-person clinical examination to be performed immediately before providing or authorizing services or treatments to patients that are not reversible. For ongoing dentist-patient relationships, dentists would be required to strongly encourage patients to be seen in person at least annually.
- California’s proposed AB 1999 would revise the conditions under which veterinarians and veterinary technicians can practice telemedicine. Registered veterinary technicians, for example, would be permitted to render lifesaving aid in emergency conditions through any means, including teletriage. The bill would also place duration restrictions on antimicrobial drugs prescribed through telemedicine.
Finalized legislation and rulemaking:
- Oklahoma enacted SB 1651, which permits respiratory care to be performed by telemedicine.
- Georgia enacted HB 1195, amending existing state law on the practice of veterinary medicine. It affirmatively allows veterinarians to provide teleadvice or teletriage without a valid VCPR and eases the conditions under which a licensed veterinarian or veterinary technician may practice veterinary teletriage with or without a VCPR.
- South Carolina enacted S 453, officially establishing guidelines and restrictions for the practice of teledentistry and requiring the Board of Dentistry to promulgate regulations governing the provision of dental services through teledentistry. The law requires bona fide provider-patient relationships before the provision of teledentistry services and sets forth requirements related to informed consent and the confirmation and verification of a patient’s identity. It also places limitations on the advertisement of teledentistry services.
- Connecticut passed HB 5142, which grants residents in residential care homes the right to use virtual monitoring technology (i.e., devices capable of remote audio or video communications that may include recording capabilities) owned and operated by the resident in the resident’s room or living quarters, at the resident’s expense. The service must comply with applicable privacy law, and appropriate notice of the monitoring must be provided in the resident’s room. If the resident lives in a shared living arrangement, the resident’s roommate must consent to the use of the monitoring. The law provides residential care homes with limited immunity from liability for violation of privacy rights of any individual under state law caused by a resident’s use of technology in accordance with the law; damage to the resident’s technology, including malfunction not caused intentionally or negligently by the residential care home; and instances when audio or video produced by the resident’s technology is inadvertently or disclosed to, intercepted, or used by an unauthorized third party, provided the residential care home does not intentionally cause such audio or video to be disclosed to, intercepted, or used by an unauthorized third party.
- Minnesota enacted HF 3825, which revises practice requirements across several health occupations, including physical therapy. The revisions clarify that telecommunications do not meet the requirement for direct supervision of student physical therapists or student physical therapy assistants, but that telehealth observation of physical therapy assistants is permitted.
- West Virginia finalized amendments to an existing rule concerning pharmacist licensure and the practice of pharmacist care, including new guidance on the provision of telehealth services and the circumstances under which telehealth services are permitted. The amendments permit telepharmacy services for direct patient care and institutional drug regimen review when the patient is offsite, provided the pharmacist is appropriately licensed. The amendments restrict prescribing via telehealth by prohibiting Schedule II controlled substances absent narrow circumstances, unless prescribed by a physician or a member of the same group practice with an established patient, and impose new substantive limits, including prohibitions on pharmacist prescribing or dispensing of abortifacients and certain gender-altering medications for minors. The amendments require all telehealth providers to comply with West Virginia law and submit to West Virginia Board of Pharmacy’s jurisdiction and discipline. The rule is set to terminate on August 1, 2031.
- The Maine Office of MaineCare Services adopted a new rule that adds High Fidelity Wraparound Services as a new Behavioral Health Home (BHH) service tier for children. The rule allows the BHH to conduct telehealth services to establish reimbursement eligibility when unforeseen and uncontrollable circumstances prevent in-person service delivery.
- The New Mexico Health Care Authority’s Behavioral Health Services Division adopted a rule that expands access to medications for opioid use disorder treatment, reduces stigmatizing language and practices, supports a patient-centered approach, and promotes provider flexibility in providing care, including through telehealth. Audio-visual telehealth platforms must be used, except when not available to the patient. When not available, it is acceptable to use audio-only devices, but only when the patient is in the presence of a licensed practitioner who is registered to prescribe (including dispense) controlled medications.
- In association with the CalWORKs Home Visiting Program, a new rule from the California Department of Social Services pairs new parents with a nurse or other trained professional who makes regular visits to the participant’s home to provide guidance, coaching, access to prenatal and postnatal care, and other health and social services. The Home Visiting Program’s resources include prenatal, infant and toddler care, infant and child nutrition, child developmental screening, parent education, training in parent/child interaction, child development and child care, job readiness and barrier removal, domestic violence and sexual assault services, and mental health and substance abuse treatment and support. The rule allows home visits to be provided via telehealth as needed.
- In Wisconsin, the Physical Therapy Examining Board adopted a rule to define “telehealth” and remove the onsite requirement for patient assessment and reevaluation, allowing these tasks to be performed via telehealth under specified conditions.
Compact activity:
- In Alaska, HB 173 would adopt the Occupational Therapy Licensure Compact with the goal of improving public access to occupational therapy services, including through the use of telehealth technology.
- HB 110 would enter Alaska into interstate compacts related to psychology and social work and includes provisions governing the use of telepsychology and telehealth services under the compacts.
- In Iowa, SF 2139 established the Athletic Trainer Compact, facilitating increased access to athletic training services through telehealth.
Why it matters:
- States are expanding the scope of telehealth. States are broadening the availability of telehealth in areas such as dentistry, veterinary care, respiratory care, and psychology. Providers in these areas should review the guidelines to determine their eligibility for providing remote services.
- Establishment of proper patient-provider relationships still matters. Even with the changes to laws and regulations involving the provision of telehealth services, states remain adamant that telehealth providers must create official provider-patient relationships before rendering those services. Providers should ensure that they properly establish these relationships even in areas where telehealth availability has increased.
Telehealth is an important development in care delivery, but the regulatory patchwork is complicated. The McDermott Will & Schulte digital health team works alongside the industry’s leading providers, payors, and technology innovators to help them enter new markets, break down barriers to delivering accessible care, and mitigate enforcement risk through proactive compliance.


Tick tock: Related trade secrets have single accrual date under DTSA statute of limitations
ARTICLE
Tick tock: Related trade secrets have single accrual date under DTSA statute of limitations
Jun 11, 2026
Read time: 4 min
The US Court of Appeals for the Federal Circuit reversed a judgment awarding damages and a permanent injunction, finding that the plaintiff’s trade secret misappropriation claims were barred by the statute of limitations under the Defend Trade Secrets Act (DTSA). Insulet Corp. v. EOFlow, Co. Ltd., Case No. 25-1807 (Fed. Cir. May 28, 2026) (Dyk, Reyna, JJ.) (Prost, J., dissenting).
Insulet manufactures the Omnipod, an adhesive wearable insulin patch pump currently sold in 25 countries. EOFlow developed a competing product, the EOPatch 2, marketed in Europe and South Korea. On August 3, 2023, Insulet filed suit against EOFlow alleging trade secret misappropriation under the DTSA and patent infringement.
The misappropriation allegedly occurred when EOFlow hired several former Insulet employees to develop the EOPatch 2. The employees included Steve DiIanni, former director of mechanical engineering at Insulet, who possessed “detailed technical information” about the Omnipod. Between March and May 2018, DiIanni provided EOFlow with computer-aided design (CAD) files and information regarding the Omnipod’s soft cannula and occlusion-detection algorithm.
The district court bifurcated the DTSA and patent claims. At trial on the DTSA claims, the jury found misappropriation of four trade secrets, including the Omnipod CAD files, and concluded that none of Insulet’s claims were barred by the statute of limitations. The jury initially awarded $170 million in compensatory damages and more than $280 million in exemplary damages. These amounts were reduced to $26 million and $34 million, respectively, with the district court’s grant of a permanent injunction. Insulet’s patent claims were dismissed without prejudice.
On appeal, Insulet moved to transfer to the Court of Appeals for the First Circuit. The Federal Circuit denied the motion, concluding that it retained jurisdiction because the dismissal of the patent claims functioned, at least in part, as a dismissal with prejudice, since the statute of limitations expired with respect to certain alleged acts of patent infringement. The Court then addressed two issues under the DTSA statute of limitations: when the statute of limitations begins to run and whether related trade secrets are subject to a single accrual date.
On the first issue, the parties disputed the applicable standard. EOFlow argued that the statute of limitations began to run under an inquiry-notice standard while Insulet contended that the Supreme Court’s 2010 decision in Merck & Co. v. Reynolds required application of a discovery standard under which the limitations period begins when the plaintiff discovers or reasonably should have discovered the facts underlying its claim. The Federal Circuit declined to decide which standard governed, concluding that Insulet’s claims were time-barred even under the more demanding Merck standard. Applying an access-plus-similarity framework, the Court found that, before the critical date, Insulet knew or should have known that EOFlow had access to its trade secrets through a former Insulet employee, and possessed sufficient information regarding similarities between the EOPatch 2 and Insulet’s trade secret technology to plead a misappropriation claim.
On the second issue, for which there was no controlling First Circuit authority, the Federal Circuit determined that the asserted trade secrets constituted a single claim of misappropriation for statute-of-limitations purposes. Relying on the DTSA’s provision that a continuing misappropriation constitutes a single claim, as well as analogous authority interpreting the Uniform Trade Secrets Act, the Court concluded that the trade secrets were disclosed by the same individual during substantially the same time period and for the same purpose. The Court determined that all four trade secrets shared the same accrual date. Because the CAD files trade secret was time-barred, the remaining trade secret claims were likewise barred by the statute of limitations.
The dissent disagreed with the majority on several grounds, arguing that the majority effectively applied an inquiry-notice standard while purporting to apply the more demanding Merck discovery standard, adopted an access-plus-similarity framework unsupported by the governing case law, improperly substituted the jury’s factual findings with its own view of the evidence, and risked encouraging premature trade secret litigation based on suspicion rather than actual discovery of misappropriation.


