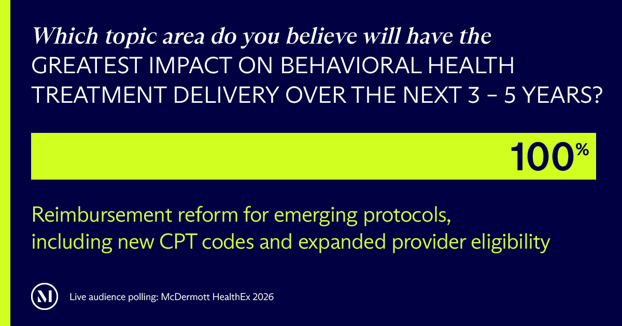
Panelists noted that expanding reimbursement for integrated care models, telebehavioral health, and emerging treatment protocols will help unlock new growth opportunities by allowing providers to deliver care more efficiently, broaden the types of clinicians who can practice at the top of their licenses, and make innovative services economically sustainable at scale.
State investments in crisis infrastructure, community-based care, and behavioral health redesign are also creating additional avenues for reimbursement and expansion, if they’re able to produce measurable results. As one panel discussed, standing up community-based crisis programs – particularly those focused on mobile response and stabilization services (MRSS) – can demonstrate meaningful reductions in emergency department utilization and downstream system involvement when replicated across a state.
Where these outcomes can be documented and sustained, and presented as a “demonstrated business case” to both CMS and SAMHSA, as one panelist detailed, they can open new reimbursement pathways and create further expansion opportunities for providers.
Growth requires stronger foundations and better patient access
The greatest constraint on behavioral health growth is capacity. Demand regularly exceeds available service providers, creating opportunities for providers that can expand access and provide more complete support and education, especially in growing needs bases.
In autism care services, families in some markets may wait 12 months or longer for a diagnosis and subsequent treatment, not including the time-intensive evaluations that precede that diagnosis. Families and patients also need meaningful support to understand that diagnosis, its potential impact, and available treatment options.
Whether with autism or another complex behavioral health condition, providers that address both the diagnostic and the post-diagnosis education and support gap are solving a more complete version of the access problem, which requires more than a steady opening of new sites of care to solve. This more comprehensive approach requires well-established clinician pipelines, better clinical oversight, and more extensive care delivery models that can be replicated across markets. Providers that build those capabilities can turn access challenges into sustainable growth opportunities.
Managed care organizations are also playing a larger role in defining network requirements, quality expectations, and reimbursement structures. Providers that can improve care access by working collaboratively in their markets – while operating effectively in performance-oriented models – will stand a better chance of growing long-term and differentiating themselves in a crowded market.
Technology is enabling specialization and better integration
Unlike more mature healthcare segments, many behavioral health organizations still have substantial opportunities to strengthen core infrastructure, standardize workflows, and invest in scalable platforms in support of long-term growth and increased attractiveness to potential buyers.
One panel described behavioral health’s relatively immature technology infrastructure, electronic medical records (EMR) capabilities, and operating systems as a source of significant upside rather than a disadvantage, given the ability to create and customize solutions as needed. At the same time, panelists emphasized that strong technology foundations – from EMR integration and revenue cycle capabilities to data and outcomes measurement – are becoming increasingly important differentiators as investors place greater emphasis on operational rigor and demonstrated growth capabilities.
In autism services, panelists highlighted how AI is supporting earlier diagnoses, creating greater consistency in clinical decision-making, and helping clinicians serve more patients without sacrificing quality. Technology is most valuable when it strengthens, not replaces, the operational and clinical foundations that differentiate high-performing organizations.
Integrated care is reshaping behavioral health delivery
Integration is a strategic priority as organizations seek to improve care quality, enable more seamless patient engagement, and create more coordinated experiences for patients with complex behavioral health and comorbid conditions. Behavioral health providers with care models that extend beyond individual encounters are gaining more market attention.
Substance use disorder (SUD) treatment presents immense opportunities for organizations looking to connect treatment needs, recovery support, and ongoing rehabilitation. Interest is growing in longitudinal care models that maintain engagement over time and provide greater visibility into patient progress. These approaches align with broader efforts to improve outcomes while reducing fragmentation.
As one panelist described, their organization’s SUD care model has a three-part clinical framework: outpatient counseling at the core, wrapped with medical care from physicians and nurse practitioners, anchored by a third component of recovery support services addressing social determinants of health. The combination of all three – under one roof, and simultaneously for each patient – is what drives differentiated outcomes.
The shift is influencing payor strategy as well. There is a growing demand for measurable outcomes and performance-based reimbursement. Organizations pursuing these arrangements will need to be able to track outcomes consistently and demonstrate clinical impact.
Looking ahead
Growth in behavioral health won’t come without friction. Workforce shortages are creating obstacles for nearly every segment. Regulatory complexity and reimbursement variability remain unresolved. The gap between what patients need and what the system delivers hasn’t closed.
Some behavioral health organizations see partnerships as the path to scale and new operational capabilities, while others are evaluating new market opportunities and expanding service offerings in search of a competitive advantage.
The behavioral health landscape has transformed, and organizations need to find a new way forward. The platforms best positioned to scale and lead are the ones improving care access, meaningfully impacting outcomes, and turning a typically fragmented collection of services into a longitudinal, integrated care experience.