













ARTICLE / CLIENT ALERT
FDA’s Fresh Take on Use of “Healthy” in Food Labeling
January 7, 2025
Read time: 8 min
On December 19, 2024, the US Food and Drug Administration (FDA) issued a new final rule titled “Food Labeling: Nutrient Content Claims; Definition of Term ‘Healthy.’” The rule revises regulations that govern when food products may be labeled as “healthy” and when a derivative term (e.g., “health,” “healthful,” or “healthier”) may be used to make a claim about the product’s nutritional content. Broadly, the new final rule adopts the regulatory approach spelled out in the FDA’s September 29, 2022, proposed rule.
These amendments represent the first significant changes to “healthy” labeling requirements in 30 years. In its new scheme, the FDA attempts to bring labeling requirements in line with 21st century advances in nutrition science that have resulted in new federal dietary guidelines. To do so, the FDA places newfound emphasis on food products’ umbrella food groups as opposed to individual nutrients.
In addition to changes in nutrition science, changes in US culture and dietary patterns prompted the amendments. The FDA describes the changes as part of its contribution to a government-wide initiative to address the “ever-growing crisis of preventable, diet-related chronic diseases in the U.S.” (such as cardiovascular disease, diabetes, and obesity) that “requires immediate action.” The FDA states that the crisis disproportionately affects certain racial and ethnic minority groups and the disadvantaged. The FDA anticipates that the amendments will advance health equity by helping consumers identify foods that can be the foundation of a healthy diet. The updated criteria allow affordable, accessible, and nutrient-dense foods associated with disparate cultural traditions and found within varied food groups and subgroups to bear the “healthy” claim, including frozen, canned, dried, and other shelf-stable products.
The FDA will begin to enforce these new regulations in February 2028, but manufacturers can start using a “healthy” claim in accordance with the new requirements as soon as the rule enters into effect on February 25, 2025.
Background
In 1990, Congress enacted the Nutrition Labeling and Education Act, which had three primary objectives:
- To enable consumers to make informed decisions about their dietary choices by providing them with relevant nutritional information.
- To standardize definitions for claims related to food products’ nutritional content.
- To encourage manufacturers to produce and market food products with greater nutritional value.
Acting in line with these objectives, the FDA adopted regulations in 1994 that created enforceable standards for manufacturers to follow when labeling their food products as “healthy” or a related derivative term (e.g., “health” or “healthful”). These regulations apply specifically to labeling that uses the term “healthy” or the like to imply that consumption of a food product comports with healthy dietary practices. These claims are distinct from those referring to a food product’s special dietary functions or effects on a consumer’s bodily structures.
The criteria established by the 1994 regulations focus on whether food products contain certain enumerated levels of nine individual nutrients, such as protein, cholesterol, and saturated fat. Although many stakeholders continue to support this approach, the FDA has concluded that it is difficult to reconcile with advances in nutrition science over the past three decades.
According to the FDA, nutrition science has evolved to take a more holistic view of diet, focusing on an individual’s consumption of synergistic, foundational food groups (foods that, because of their overall nutrition profiles, can be the “foundation” or “building blocks” of a healthy dietary pattern) – e.g., vegetables, fruits, whole grains, fat-free and low-fat dairy, lean game meat, and seafood with no added ingredients – rather than on pure nutrient intake. The FDA argues that under the 1994 regulations, foods that are now widely considered to be healthy cannot be labeled as such. For example, manufacturers have likely been unable to include “healthy” on a salmon food product’s packaging because of the fish’s high fat content. Similarly, some foods that could previously carry the “healthy” claim, such as white bread and heavily sweetened cereal and yogurt, will no longer qualify. In addition to salmon, newly qualifying foods will include nuts and seeds, olive oil, and some peanut butters and canned fruits and vegetables.
Key Concepts
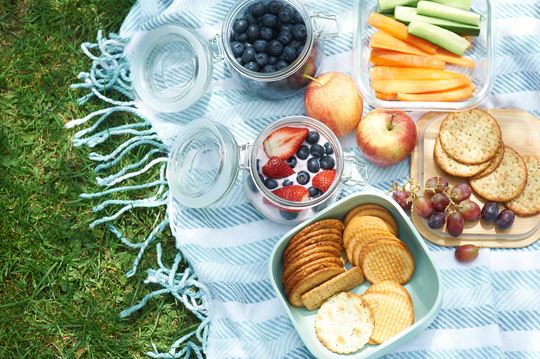
In place of individual nutrients, the FDA has centered its new criteria on the five food groups recommended in the current federal dietary guidelines: vegetables, fruits, grains, fat free or low-fat dairy, and proteins (e.g., lean meat, seafood, eggs, beans, peas, lentils, nuts, and seeds). The FDA applies some nuances to these groups. Vegetable or fruit pastes, purees, and powders may qualify if they represent a mere change in the food product’s form. Likewise, the FDA intends to consider plant-based dairy alternatives as members of the dairy group when they have similar nutritional content to true dairy products.
Under the “food group equivalent” (FGE) system carried over from the 2022 proposed rule, a “healthy” nutrient content claim generally must contain a certain amount of food from at least one of the food groups or subgroups recommended by the federal dietary guidelines and also must fall below specific nutrient limits for added sugars, sodium, and saturated fat. For example, one FGE for a vegetable food is established as a half cup equivalent. The exact amount of a vegetable product that would satisfy this criterion may vary based on its preparation. To illustrate, both one cup of raw spinach and a half cup of cooked green beans equal half cup equivalents, and thus each would individually constitute one FGE.
These FGEs form the basis of the FDA’s new labeling criteria. In total, there are six scenarios where a food product may carry a “healthy” claim:
- Single Ingredient Exception: Food products with only ingredients from the five food groups and water.
- Individual Food: Consumed in quantities of greater than 50 grams, contains one or more FGE. Includes oil-based products and those less than 50 grams if they meet FGE and nutrient requirements per 50 grams.
- Mixed Food Product: Contains one or more FGE, with at least one quarter FGE from two food groups. Example: one quarter vegetable FGE and three quarters protein FGE.
- Main Dish Product: Serving contains two or more FGEs, with at least one half FGE from two food groups. FGEs can be aggregated.
- Meal Product: Serving contains three or more FGEs, with at least one half FGE from three food groups. FGEs can be aggregated.
- Low-Calorie Beverages: Coffee, tea, and water with fewer than five calories per serving. FDA may exercise discretion in labeling these as “healthy.”
Manufacturers that ultimately decide to make a “healthy” claim for a qualifying food product must also follow new bookkeeping requirements. The final rule establishes that in situations where a food’s ability to qualify under the “healthy” criteria is not obvious from its nutritional label, manufacturers must maintain written records establishing the same. The form these records take may vary based on a manufacturer’s preferences, but they must be kept for at least two years after a product’s introduction to the market.
The FDA stresses that manufacturers whose products fail to meet the above criteria still have an array of valid marketing options at their disposal. Indications of a product’s low sodium content, for example, would still be acceptable in a variety of circumstances. The FDA also intends to engage in consumer education efforts so that failure to meet the listed criteria is not equated to a product’s being “unhealthy.”
Next Steps
Manufacturers can begin to use a “healthy” claim in accordance with the new requirements as soon as the rule enters into effect on February 25, 2025. The FDA intends to create and publish additional resources to aid manufacturers in determining FGE amounts before the regulation’s compliance date in February 2028. The FDA stated that these resources may include guidance documents, FAQs, direct responses to questions, or online webinars.
The agency also announced an intent to publish a proposed rule on front-of-package nutrition labeling, which may include a “healthy” symbol to designate qualifying food products.
For more information on how to comply with the FDA’s new “healthy” labeling requirements, contact the authors of this article or any other member of McDermott’s Food, Drug & Medical Device Regulatory Group.






CMS Updates Scope of Providers Subject to Provisional Period of Enhanced Oversight
ARTICLE / CLIENT ALERT
CMS Updates Scope of Providers Subject to Provisional Period of Enhanced Oversight
January 7, 2025
Read time: 4 min
The Centers for Medicare & Medicaid Services’ (CMS) 2025 Home Health Prospective Payment System final rule (Final Rule) expanded the scope of providers subject to a provisional period of enhanced oversight (PPEO) to include providers reactivating their Medicare enrollment and billing privileges after being in a deactivated status. Previously, a PPEO was limited to providers and suppliers that were newly enrolling in Medicare (starting July 13, 2023), undergoing a change of ownership under 42 CFR 489.18, or undergoing a 100% ownership change that does not fall under 42 CFR 489.18. Currently, qualifying hospices in Arizona, California, Nevada, and Texas are subject to a PPEO. Hospices in these states, which now includes hospices seeking reactivation, can expect a closer review by CMS on claim submissions from between 30 days to one year, effective when the provider submits its first claim.
Under Section 1866(j)(3)(A) of the Social Security Act of 1935, the US Secretary of the Department of Health and Human Services (HHS) has the authority to establish procedures for a PPEO over Medicare providers and suppliers. A PPEO can last between 30 days and one year and allows CMS to take actions such as prepayment medical review and payment caps. CMS has utilized this authority to place new hospices in Arizona, California, Nevada, and Texas on a PPEO. The HHS Secretary may establish a PPEO by program instruction or other subregulatory guidance.
A new provider or supplier for purposes of a PPEO is defined as a newly enrolling Medicare provider or supplier, a certified provider or certified supplier undergoing a change of ownership consistent with the principles of 42 CFR 489.18, or a provider or supplier (including a home health agency or hospice) undergoing a 100% change of ownership via a change of information request under 42 CFR § 424.516. CMS has stated that the effective date of a PPEO is the date the new provider submits its first claim as opposed to date of enrollment.
In the Final Rule, CMS included providers that are reactivating their Medicare billing privileges under 42 CFR 424.540(b) in the definition of a “new provider or supplier” as it relates to a PPEO authority. CMS stated in commentary to the Final Rule that reactivation is effectively establishing a new provider or supplier for purposes of Medicare. CMS declined to respond to the majority of submitted comments about the scope and duration of a PPEO, stating that such comments were out of scope.
Key Takeaways
The inclusion of reactivating providers as eligible providers for a PPEO shows CMS’s consistent focus on combatting fraud and abuse through the use of a PPEO as well as its continued focus on hospices. Applicable Medicare Administrative Contractors publish pre-payment review results for hospices subject to a PPEO with the reports identifying the number of providers subject to review, the number of providers deemed compliant and removed from review, and the number of providers deemed noncompliant and subject to subsequent probe reviews. These reports also identify the top denial reasons and guidance on how to avoid such denials.
Hospices in Arizona, California, Nevada, and Texas that are newly enrolling in Medicare, undergoing a change of ownership under 42 CFR 489.18, undergoing a 100% ownership change, or reactivating their enrollment and billing privileges should review these published reports and audit their documentation to ensure compliance with Medicare billing requirements. Other Medicare providers should monitor CMS reports that expand the scope of providers subject to a PPEO, including hospices in other states and providers outside of hospice.


Bedtime for Serta: The Fifth Circuit Unravels Serta’s Uptier LME Transaction
ARTICLE / CLIENT ALERT
Bedtime for Serta: The Fifth Circuit Unravels Serta’s Uptier LME Transaction
January 7, 2025
Read time: 11 min
On Dec. 31, 2024, the US Court of Appeals for the Fifth Circuit issued a long-awaited decision reversing the ruling of former Judge David Jones of the Bankruptcy Court for the Southern District of Texas, blessing the Serta Simmons Bedding 2020 uptier transaction. The ruling deemed the uptier transaction impermissible and potentially puts pressure on other uptiering transactions. In re Serta Simmons Bedding, LLC, No. 23-20181 (5th Cir. Dec. 31, 2024).
More specifically, the Court held that Serta’s exchange of the Prevailing Lenders’ (i.e., participating lenders) existing debt for new super-priority debt — to the detriment of Excluded and LCM Lenders (i.e., non-participating lenders who objected to the transaction) — did not qualify as a permissible open market purchase under the governing loan agreement and violated the agreement’s pro rata sharing provision. The Fifth Circuit also excised from Serta’s bankruptcy Plan provisions indemnifying certain Prevailing Lenders that participated in the transaction and other selected parties. The Fifth Circuit remanded the Excluded Lenders’ potential breach claims against the Debtors and Prevailing Lenders for further consideration at the Bankruptcy Court.
The Fifth Circuit’s Serta decision reversed the Bankruptcy Court’s decision that was notably favorable to the uptiering transaction. While the Serta ruling is contract-specific and does not signal any pattern for future liability management transactions, it does demonstrate that courts in the Fifth Circuit (most notably the Houston Bankruptcy Court) cannot rubber stamp similar transactions. Consequently, we expect increased caution in considering liability management transactions, especially ones that involve non-pro-rata debt exchanges. In its preamble, the Fifth Circuit states: “Ratable treatment is an important background norm of corporate finance. Pursuant to this norm, a borrower must treat all of its similarly situated lenders, well, similarly.”
Background
A. The Terms of the 2016 Credit Agreement
In 2016, Serta entered into its First Lien Term Loan Agreement. The following provisions of the loan form the center of the case:
- §2.18 (Pro-Rata Sharing): Pursuant to § 2.18, “[e]ach Borrowing, each payment or prepayment of principal of any Borrowing, each payment of interest in respect of the Loans of a given Class and each conversion of any Borrowing…shall be allocated pro rata among the Lenders in accordance with their respective Applicable Percentages of the applicable Class.”
- §9.01(b)(A) (Protection of Sacred Rights): As noted by the Fifth Circuit, “[r]atable treatment is such an important norm that it is often described as a lender’s ‘sacred right.’” To protect this sacred right, § 9.01(b)(A) requires “unanimous consent of any affected lender to waive, amend, or modify § 2.18 in any way that would ‘alter the pro rata sharing of payments required thereby.’”
- §9.05(g) (Exceptions to Pro-Rata Sharing): § 9.05(g) sets out two ways through which Serta can repay loans without having to engage in pro rata sharing: (1) a Dutch auction, and (2) an open market purchase (which the loan leaves undefined).
B. The Uptier
In 2020, after facing years of financial hardship, exacerbated by the pandemic, Serta entered into the uptiering transaction with the Prevailing Lenders. To carry out the uptier, Serta and the Prevailing Lenders took the following steps:
- Taking advantage of the Prevailing Lenders’ majority of the outstanding first-lien debt, Plaintiffs amended the loan to allow the uptier.
- Plaintiffs preemptively labeled the uptier an “open market purchase,” “apparently in recognition that the 2016 Agreement’s ratable-sharing provision would otherwise bar the 2020 Uptier.”
- Serta agreed to indemnify Prevailing Lenders for any and all future losses, claims, damages and liability incurred in connection with Prevailing Lenders’ participation in the uptier.
C. Prior Proceedings
In January 2023, Serta filed for Chapter 11 Bankruptcy in the Southern District of Texas. On Jan. 24, 2023, Plaintiffs (here, the Debtors and Participating Lenders) filed an action in the Bankruptcy Court seeking a declaratory judgment that the uptier (i) was permitted by the loan agreement’s pro-rata provision, and (ii) did not violate the implied covenant of good faith and fair dealing. The Bankruptcy Court ruled for Plaintiffs, granting partial summary judgment and holding that the uptier was an open market purchase.
Serta then proposed a Chapter 11 Plan premised upon the capital structure implemented following the uptier. Serta’s final proposed Plan contained an indemnity that only covered certain Prevailing Lenders and other selected parties. The Bankruptcy Court ultimately confirmed this Plan and ruled in favor of the indemnity provision.
The Excluded and LCM Lenders appealed both the open market purchase ruling and the indemnity ruling, and the Fifth Circuit consolidated the appeals for resolution.
The Validity of the Uptier as an Open Market Purchase
The Fifth Circuit held that the uptier was not a permissible open market purchase within the plain meaning of § 9.05(g) of the loan. Focusing on the language of the loan itself, the Fifth Circuit reached this conclusion for two reasons.
First, the Fifth Circuit found that an “‘open market’ is a specific market that is generally open to participation by various buyers and sellers” and an open market purchase “takes place on such a market as is relevant to the purchased product — here, the secondary market for syndicated loans.” Thus, “if [Serta] wished to make a § 9.05(g) open market purchase and thereby circumvent the sacred right of ratable treatment, it should have purchased its loans on the secondary market,” not “privately engage individual lenders outside of this market.”
Second, the Court’s definition of open market purchase comports with § 9.05(g)’s other exception (i.e., the Dutch auction), while Plaintiffs’ more expansive definition of an open market “would swallow that exception and render it surplusage.” According to Serta’s brief, an open market purchase is simply an acquisition of “something for value in competition among private parties.” The Fifth Circuit noted that if Plaintiffs’ definition governs, “the Dutch auction exception does no work,” because “the completion of a Dutch auction and accompanying buyback of loans would constitute an acquisition for value in competition among participants.”
Based upon the above analysis, the Fifth Circuit reversed the Bankruptcy Court’s decision and remanded Excluded Lenders’ breach of contract counterclaims for reconsideration.
Invalidating the Plan’s Indemnity
A. The Merits of Excising the Indemnity
Turning to the merits of the confirmed Plan’s indemnity, the Fifth Circuit held that the indemnity “was an impermissible end-run around” Bankruptcy Code § 502(e)(1)(B) and violative of the Code’s equal treatment requirement.
- §502(e)(1)(B)
The Fifth Circuit ruled in favor of excising the indemnity from the confirmed Plan because it is impermissible under § 502(e)(1)(B).
Bankruptcy Code § 502(e)(1)(B) prohibits reimbursement of contingent claims where the claiming entity is co-liable with the debtor. However, Bankruptcy Code § 1123(b)(3)(A) allows a plan to provide for the settlement of any claim belonging to the debtor.
Because Prevailing Lender plaintiffs’ claims for indemnification fall within § 502(e)(1)(B), Plaintiffs recharacterized the initial indemnity as a settlement between Serta and Prevailing Lender plaintiffs in the confirmed Plan, hoping for it to fall within the ambit of § 1123(b)(3)(A). In support of this recharacterization, Plaintiffs argued that the Plan indemnity differed from the pre-petition indemnity provisions. More specifically, Plaintiffs argued that the “pre-petition indemnity covered all of and only the Prevailing Lenders who participated in the 2020 Uptier, whereas the settlement indemnity covered only those holders of super-priority debt as of June 29, 2023,” meaning that “the settlement indemnity was not an impermissible attempt to resurrect the pre-petition indemnity.”
The Fifth Circuit rejected this argument, holding that “the settlement indemnity is sufficiently similar to the pre-petition indemnity so as to still view it as an end-run around § 502(e)(1)(B).” The Fifth Circuit went on to explain that if Plaintiffs’ argument was “[t]aken to its logical conclusion, a § 1123(b)(3)(A) settlement could thus resurrect a clearly disallowed claim or related indemnity so long as it was modified slightly from its original form.”
- Equal Treatment
The Fifth Circuit additionally held that “[e]ven if the settlement indemnity was justified under § 1123(b)(3)(A), its inclusion in the Plan violated the Code’s requirement of equal treatment.”
Bankruptcy Code § 1123(a)(4) sets out that a plan must “provide the same treatment for each claim or interest of a particular class, unless the holder of a particular claim or interest agrees to a less favorable treatment of such particular claim or interest.”
The Fifth Circuit found that the Plan’s inclusion of the indemnity violated § 1123(a)(4) because “the expected value of the indemnity varied dramatically depending on whether members had participated in the 2020 Uptier.” For example, to Prevailing Lender plaintiffs, the indemnity could be worth millions of dollars, but to class members who had no involvement with the uptier, the indemnity was worth little or even nothing.
The Fifth Circuit further stated that the Supreme Court, in Czyzewski v. Jevic Holding Corp., 580 U.S. 451 (2017), previously held that the Bankruptcy Code’s priority scheme is embedded in the entire Bankruptcy Code – and any actions under the Bankruptcy Code must comport with bankruptcy priority – irrespective of the language of a specific provision of the Bankruptcy Code. Quoting Jevic, the Fifth Circuit held: “‘statutory construction . . . is a holistic endeavor,’ by which courts must ‘look to the provisions of the whole law.’ . . . Without adequate textual support for its maneuver, the bankruptcy court was wrong to approve such an end-run around the Code.”
Holding that the court may “fashion whatever relief is practicable’ for the benefit of [Defendants],” the Fifth Circuit excised the offending indemnity.
B. Plaintiffs’ Equitable Mootness Argument
In ruling whether to excise the indemnity from the confirmed Plan, the Fifth Circuit also addressed Plaintiffs’ argument that the request for excision is equitably moot. The Fifth Circuit held that the argument is not equitably moot.
To determine equitable mootness, courts analyze three factors: “(i) whether a stay has been obtained, (ii) whether the Plan has been ‘substantially consummated,’ and (iii) whether the relief requested would affect either the rights of parties not before the court or the success of the Plan.” The Fifth Circuit exercises caution in applying equitable mootness to direct appeals from the Bankruptcy Court.
The Fifth Circuit held that while Defendants failed to obtain a stay of the Plan’s confirmation and the Plan had been substantially consummated, these two factors are not dispositive. Instead, the Fifth Circuit looked to the third factor, holding that no third party rights would be affected by excision. The Fifth Circuit also rebuked Plaintiffs’ contention that by excising the indemnity the entire Plan would be unwound, stating that “excision does not toll doom for the Plan, and the third factor properly weighs against equitable mootness.” Moreover, the Court stated: “To the extent equitable mootness exists, we affirm that it cannot be ‘a shield for sharp or unauthorized practices.’”
Takeaways
- The Serta ruling marks the first federal Court of Appeals ruling on the recent spate of liability management transactions. Thus it will receive significant attention from other courts.
- However, its practical impact (and applicability to other LMEs) remains unclear. The Serta decision (like other recent LME opinions) is focused on the plain language of the specific loan agreement. Of course, each credit agreement has its own language.
- Questions remain whether the Serta decision will apply to other uptier LMEs where credit documents contain dissimilar buyback language but the uptier LME has the same net effect as the Serta LME.
- What remains clear, however, is that Serta demonstrates that uptier transactions will continue to receive close judicial scrutiny.
- As the Fifth Circuit’s ruling regarding the Plan’s indemnity demonstrates, the Bankruptcy Code’s core principles and provisions (g., § 502(e)(1)(B) and equal treatment) will prevail once LMEs are brought to courts that must apply Federal bankruptcy law. Any use of a Plan to resolve a LME will face typical plan scrutiny.
- The Court makes general statements about ratable treatment and cites to the Code’s precepts of ratable treatment consistent with Jevic.
- The decision revives the breach of contract claims of the non-participating lenders. We expect litigation to continue as the non-participating lenders reevaluate their claims against the participating lenders following this decision.
Authored by Douglas Mintz, David Arnstein, Bill Gussman, Douglas Koff, Reuben Dizengoff and Lindsey Neuberger.
If you have any questions concerning this Alert, please contact your attorney at Schulte Roth & Zabel or one of the authors.
This communication is issued by Schulte Roth & Zabel LLP for informational purposes only and does not constitute
legal advice or establish an attorney-client relationship. In some jurisdictions, this publication may be considered attorney advertising. © 2024 Schulte Roth & Zabel LLP. All rights reserved. SCHULTE ROTH & ZABEL is the registered trademark
of Schulte Roth & Zabel LLP.



Data Privacy and Cybersecurity Developments We Are Watching in 2025
CLIENT ALERT / US POLICY
Data Privacy and Cybersecurity Developments We Are Watching in 2025
January 6, 2025
Read time: 8 min
The act of predicting what will become the dominating storyline of data privacy and cybersecurity in 2025 is a hazardous enterprise, as one is almost surely to get something wrong. Without fail, every year, regulators and the plaintiffs’ bar push data privacy and cybersecurity in a direction that seemed unlikely the prior calendar year. Yet, we are undeterred. After canvassing our global group of data privacy and cybersecurity professionals, below are the topics that we are watching most closely as we kick off 2025. While these may not be the headlines that dominate when we look back after 12 months, we anticipate that companies will have spent significant time in 2025 working through the developments below.
Website Tracking: Make Sure You’re Doing It Right
As we explained in our recent Cookie Deep Dive webinar, there has been an explosion of enforcement and litigation targeting the use of cookies, chat bots, session replay, and other technologies (collectively, cookies). Regulators in the United States have undertaken extensive investigations and imposed massive fines. Plaintiffs allege cookies constitute “wiretapping” under archaic laws such as the California Invasion of Privacy Act (CIPA), which permit statutory damages of $5,000 to $10,000 per violation. The trend of more plaintiffs’ firms asserting additional claims and increasing settlement demands is likely to escalate given the trend in recent CIPA jurisprudence. Fortunately, there was some good news for defendants in 2024. The Massachusetts Supreme Court, in a case argued by McDermott Partner Dave Gacioch, held that Massachusetts’ wiretapping law did not apply to cookies.
To mitigate these heightened risks, clients are focusing more on cookie management while still enabling marketing, analytics, and data monetization. Now is the time to audit practices, document procedures, and make a plan, because we see no end in sight to these risks heading into 2025.
Artificial Intelligence (AI): Because of Course
There may not have been a bigger story in 2024 than the proliferation of publicly available AI tools. And the race to regulate AI likely is still in its early stages. Generative AI (GenAI) provides incredible capabilities but presents a bevy of privacy and potential security risks. GenAI tools also pose novel issues related to intellectual property rights and data ownership. To fully grasp and balance the potential risks and benefits of GenAI, companies first must understand the types of data being used to train the model, the provenance of such data, and ensure that the company has the appropriate rights and consents to use that data. Keeping up with the AI curve can feel daunting, but we have developed a series of standard operating procedures, templates, and training materials that can make things less scary. McDermott’s Artificial Intelligence Law Center is a resource for those looking to dig into this cutting-edge issue.
PCI DSS 4.0: It’s Almost Here!
The Payment Card Industry Data Security standard (PCI DSS) 4.0 for credit-card processing is fully effective March 31, 2025. If a company accepts credit cards as a merchant, it has PCI DSS and card-brand obligations under its contracts with its bank and any third-party processors. The new 4.0 security obligations are some of the most robust and onerous of any framework, and they will have numerous implications for any company taking, processing, or storing credit or debit cards. Preparing for these changes will require significant time and effort. The transition to new PCI DSS 4.0 controls involves numerous new workflows, including the need for new policies, processes, and technology solutions. We recently examined how PCI DSS 4.0 will impact digital health and healthcare companies, especially as e-commerce models expand.
There are a number of challenges and obstacles to full PCI DSS 4.0 compliance, including the fact that many companies mistakenly believe that fully outsourcing credit card functions to a third-party payment platform exempts them from PCI DSS obligations. That is not true. If you are not sure about the state of your company’s PCI DSS compliance, now is the time to dig in.
Federal Privacy Regulation and Enforcement: What Comes Next?
What will the second Trump administration bring? Between chatter of shuttering entire agencies and shifting enforcement priorities, the one thing that is clear is that 2025 will see a change in the way that the federal government approaches its role in the consumer privacy arena.
One development we are watching is what is going to happen with the Consumer Financial Protection Bureau (CFPB). The CFPB recently issued a proposed rule seeking to bring certain data brokers within the scope of the Fair Credit Reporting Act (FCRA). The proposed rule would revise the definitions of “consumer reporting agency” and “consumer report” in Regulation V and modify restrictions on when consumer reporting agencies may furnish, and users may obtain, consumer reports. Comments on the proposed rule are due March 3, 2025, but what will be interesting to see is whether the rule making process will continue under the new administration.
State Laws: You Knew We Couldn’t Omit This One
Seven. That was the number of new state consumer privacy laws passed in 2024. That was on the heels of eight new laws passed in 2023. The smart money for 2025 is that there will be another half-dozen states that enact consumer privacy laws as we move closer and closer to a complete patchwork of state consumer privacy laws in the absence of a federal consumer privacy law (the likelihood of which, under Republican control, is low). It can be hard to keep up with all the changes and requirements of the different laws, which is why McDermott has an online resource to help you keep track. Our consumer privacy law map is regularly updated and is a free resource.
Another thing that bears watching, of course, is the progress of the new California Consumer Privacy Act (CCPA) regulations, which are in the public comment period. These proposed regulations are onerous and overbroad, and they seem destined for a legal challenge if they are finalized.
EU Data Act: Something Like We’ve Never Seen Before
Among the EU Digital Package regulations, the EU Data Act is quite likely to be the most challenging to implement. We anticipate that many clients will begin or continue their implementation work streams well into 2025. The three primary obligations of the EU Data Act include:
- The obligation to provide an access mechanism by design and by default and, if technically feasible, to provide users with direct access to their data (Data Act, Art. 3(1)).
- The obligation to provide users with indirect access to their data (Data Act, Art. 4(1)).
- The obligation to provide third parties with data upon request from users (Data Act, Art. 5(1)).
When these obligations become applicable will vary based on a variety of factors, including jurisdiction and product type. However, they will phase in between September 2025 and September 2026. Given this time frame, we anticipate that many companies will focus significant effort on their EU Data Act compliance activities in 2025 if they have not already started doing so.
EU Cybersecurity Frameworks: Time to Revisit Past Practices
In 2025, businesses operating in the EU will need to focus their cybersecurity efforts to comply with either the Network and Information Security 2 (NIS2) Directive (the cornerstone of the EU legal framework for cybersecurity), the Digital Operational Resilience Act (DORA, a cybersecurity regulation for financial institutions), or the Cyber Resilience Act (a regulation applying to manufacturers of products with digital elements placed on the EU market). This framework imposes, among others, cybersecurity controls and obligations to report incidents, and it is backed up by potentially heavy fines and, in some cases, personal liability of members of boards of directors.
While the NIS2 Directive became applicable in October 2024, only a handful of EU countries (e.g., Belgium, Italy) have implemented the Directive through their legal order. In 2025, we expect other EU countries to do the same. The NIS2 Directive covers businesses from a broad spectrum of industries deemed highly critical – such as energy, health, and digital infrastructure – and critical. DORA becomes effective on January 17, 2025, and applies to financial institutions. For both DORA and NIS2, covered entities must implement measures ensuring supply chain security, including supply chain contractual terms with their direct suppliers/service providers.
Take a Deep Breath: It Will (Mostly) Be OK
Reviewing the above, it is easy to see how in-house privacy counsel could become overwhelmed. But for (almost) every problem, there is a solution. It begins with understanding whether any of the above laws apply to your business. Most companies have already some cybersecurity measures in place, so the project will inevitably entail conducting a gap analysis. At this point, companies will have to design methods to address and mitigate any existing gaps. McDermott has a variety of toolkits, templates, presentations, and other materials that can help companies address the privacy and cybersecurity challenges that they may face heading into 2025.
If you have any questions or would like to discuss anything contained in this article, contact your regular McDermott lawyer or one of the article’s authors.


What the New CLIA Rules Mean for Labs and At-Home Testing
ARTICLE / CLIENT ALERT
What the New CLIA Rules Mean for Labs and At-Home Testing
January 3, 2025
Read time: 6 min
New regulations under the Clinical Laboratory Improvement Amendments (CLIA) introduced updated proficiency testing (PT) and PT referral rules that are now in effect. Although the regulations became effective on July 11, 2024, the final rule on PT Regulations Related to Analytes and Acceptable Performance (CMS-3355-F), issued by the Centers for Medicare & Medicaid Services (CMS), was not implemented until January 1, 2025.
PT and the rules around PT referral form a critical safety net for ensuring trust and accuracy in patient diagnostics. This is true not just for traditional labs, but also for a broad spectrum of healthcare providers, including hospitals, digital health companies, and telehealth providers offering at-home testing solutions. Behind the convenience and accessibility of modern clinical laboratory testing lies a complex web of rules governing quality assurance, namely PT, which evaluates a laboratory’s ability to deliver accurate and reliable results.
To assist providers in understanding the rule changes, CMS issued a guidance brochure for CMS-inspected laboratories, with the caveat that accredited laboratories must follow the applicable accreditation organization’s PT requirements.
What’s New in the Final Rule?
The updated regulations refine the PT framework, emphasizing stricter adherence and accountability for providers across the clinical laboratory spectrum:
- Clarified PT Requirements for Complex Testing. The new rule reinforces mandatory PT participation for all non-waived regulated analytes and specialties listed in Subpart I of the CLIA regulations. Providers performing moderate or complex tests must align with these standards.
- Stronger Focus on Waived and Unregulated Testing. While PT remains optional for waived tests – often used in point-of-care diagnostics (e.g., urine pregnancy tests) – the updated rule highlights the importance of voluntary participation to bolster quality assurance. For unregulated tests, which do not require PT, the updated rule highlights that entities holding a CLIA certificate must continue verifying the accuracy of these tests at least twice a year, with a renewed emphasis on documentation.
- Tightened PT Referral Provisions. New provisions aim to close loopholes in PT sample handling. Forwarding PT samples or discussing results with external entities is strictly prohibited, and enhanced enforcement measures are in place to deter violations. This prohibition applies to CLIA-certified laboratories that voluntarily participate in PT for waived tests as well as laboratories performing compulsory PT for non-waived tests.
- Enhanced Oversight and Reporting. Labs and providers must maintain robust records of their PT participation, results, and corrective actions. These records will be subject to stricter audits from CMS during biennial inspections to ensure compliance.
- Accountability for Cybersecurity. New provisions require labs to follow the manufacturer’s instructions for installing all software updates, including cybersecurity updates.
Why Does It Matter?
- Detecting Errors Early: PT acts as a safeguard, identifying potential issues before they compromise patient care.
- Ensuring Competency: PT validates the entire testing process, from staff proficiency to equipment accuracy.
- Building Confidence: Reliable results enhance trust among patients, providers, and regulatory bodies.
To Whom Does the PT Final Rule Apply?
The PT final rule and guidance brochure apply only to CMS-inspected laboratories and therefore may not apply to accredited labs, which are subject to independent accreditation organizations’ PT requirements, or laboratories performing cytology testing, which have unique PT requirements set forth at 42 CFR § 493.945.
What PT Must a Laboratory Undertake?
Labs performing non-waived tests must enroll in a US Department of Health and Human Services-approved PT program. The PT program will send the laboratory unknown test samples for each regulated analyte that the laboratory tests, usually three times a year. The lab then reports its results to the PT program, which evaluates the lab’s performance. A lab performing moderate and complex tests must enroll and participate in PT for each CLIA certificate it holds (i.e., one PT program per location), excluding certificates of waiver.
PT Referral Risks in Collaborative Healthcare Models
The interconnected nature of healthcare delivery – spanning hospitals, reference labs, and telehealth – increases the risk of forwarding PT samples to another lab or discussing results externally. This act, known as a PT referral, is a major violation under CLIA regulations, even if the referral is inadvertent. Potential consequences for PT referrals include:
- Revocation of the laboratory’s CLIA certificate.
- Restrictions on the organization’s ability to conduct testing (e.g., restricting lab director’s or owner’s lab operations).
- Reputational damage through public sanctions.
- Loss of patient trust.
Staying Compliant: What Labs Must Do
- Keep It In-House: Never send PT samples outside your lab, even if it is standard practice for patient specimens.
- Educate Your Team: Staff must clearly understand the difference between PT and patient sample handling.
- Take Immediate Action: If another lab sends you PT samples, report it to CMS or your state agency and refuse to test the samples.
Recovering From Setbacks
Repeated PT failures or referral violations can lead to sanctions, including halted testing and suspended reimbursements. Labs can recover by:
- Diagnosing the Problem: Identify and address root causes of the breakdown and where it occurred, whether in lab analysis, sample logistics, or internal training.
- Earning Back Trust: Complete two consecutive successful PT events to regain compliance.
PT is not solely about avoiding penalties; it is about maintaining the highest standards of care. Every accurate test result reinforces patients’ trust in healthcare. By taking PT and referral rules seriously, labs can strengthen consumer confidence in their services, whether in-person or remote.
For more information on clinical laboratory operations and PT testing, please contact Greg Fosheim or Ashley Ogedegbe.
Beck’sches Family Office Handbook
ARTICLE
Beck’sches Family Office Handbook
2025
Read time: 2 min
Prof Dr Clemens Just is co-author of the handbook ‘Beck’sches Handbuch Family Office’ published by C.H. Beck Verlag.
The handbook ‘Beck’sches Handbuch Family Office’ offers a comprehensive presentation of the management of large family assets by a family office. It deals with business and legal issues, including succession planning, tax law and investments outside Germany, and offers practical and academically sound contributions.

New Year, New Rules: Global Equity and Employment Law Considerations for Calendar Year 2025
ARTICLE / CLIENT ALERT
New Year, New Rules: Global Equity and Employment Law Considerations for Calendar Year 2025
December 31, 2024
Read time: 9 min
Many countries finalized new regulations and released new guidance in 2024 regarding global equity plans. Multinational companies should confirm whether their equity grant materials and plan administration align with such updates, especially if equity grants are expected during Q1 2025. Given the frequent overlap between global equity compensation and global employment laws, it is also recommended that in-house counsel teams collaborate to ensure equity grant materials comprehensively address any employment-related matters. This summary highlights selected updates that many companies are currently addressing.
Brazil
A court decision reaffirmed that stock options are not considered labor remuneration and instead are considered “commercial income” (Brazilian Superior Court (STJ), Case No. 1226). As such, stock options are not subject to income tax at grant or exercise. However, upon the sale of any shares, the value is subject to capital gains taxation. The decision is pending a formal appeal but, if upheld, helps to solidify the position that no tax is due at exercise.
Next Steps for Companies: Continue to monitor ongoing updates. The court decision highlights the tension between Brazilian tax authorities and labor courts regarding tax treatment of stock option and restricted stock unit (RSU) grants. Assuming the decision is upheld, companies may elect to increase utilization of stock option grants to Brazil employees.
Canada
- Quebec – A court of appeals in Quebec held that a former employee remained entitled to the value of unvested RSUs that would have vested during a notice of termination period (Endeavour Canada Holdings Corporation v. Boucher). In the case, the employee received an indemnity in lieu of a notice period. With this, he did not vest in his final tranche of RSUs because his employment terminated prior to the applicable notice period. Although the court noted its analysis was fact dependent, conflicting termination language within the plan materials and severance policy supported the argument that the employee remained entitled to the RSUs.
Next Steps for Companies: Review grant materials and company programs/policies (e.g., severance plans, clawback policies, notice periods) to ensure termination provisions for termination of employment events are clear and consistent across all documents.
- Ontario – A court of appeals in Ontario held that a terminated employee waived his right to a vested equity grant upon execution of a settlement and release agreement (Preston v. Cervus Equipment Corporation, 2024 ONCA 804). Upon termination, the employee filed a wrongful dismissal claim against the employer and the parties settled. The settlement was contingent on the execution of a settlement and release agreement (release) and the employee had not been paid any amounts related to his vested equity when the release was signed. The employee subsequently filed a claim against the employer for payment of the vested equity. However, the court of appeals overturned the lower court’s initial holding and held in favor of the employer given that the release specifically barred any claims regarding “stock or share awards.”
Next Steps for Companies: Review form settlement and release agreements to ensure treatment aligns with current grant materials and company programs/policies. Although general releases may be enforceable in most circumstances, consider drafting distinct provisions for each element of compensation that may apply to the terminated employee (e.g., vacation payout, leave accruals, equity grants). Specificity will help mitigate ambiguity regarding enforcement and interpretation of such agreements.
European Union
Under the Pay Transparency Directive, the gender pay gap must not exceed 5% (Directive (EU) 2023/970). A reporting requirement also applies with the reporting interval varying based on employer size. For example, companies with at least 250 workers must report annually beginning in June 2027. Reports must reflect data beginning in calendar year 2026, including but not limited to: (a) average gender pay gap; (b) median gender pay gap; (c) proportion of female/male workers in each quartile pay band; and (d) average gender pay gap across categories of workers. Additional disclosure requirements regarding pay range and pay progression also apply. Member states must implement the directive by June 7, 2026, and may establish state-specific obligations.
Next Steps for Companies: Evaluate whether current pay transparency practices for entities in the European Union can be expanded to comply with the Pay Transparency Directive. Alternatively, consider whether pay transparency practices for entities outside of the European Union can be implemented for entities in the European Union. Our teams are available to evaluate initial compliance and develop an appropriate strategy. Many companies are concerned that enhanced visibility may result in employee concerns between countries.
Finland
The ombudsman for equality released a statement affirming that equity grants are subject to equal pay laws (TAS/667/2023 as of July 9, 2024, and released on September 12, 2024). Although equity incentive plans can provide for employer discretion in granting equity, the criteria and terms of such grants must be transparent and objective.
Next Steps for Companies: Evaluate whether the nomination process for equity grants is objective (e.g., based on grantee title, salary). If the process provides for discretion, the general criteria (e.g., sales metrics, annual review rating) should be clearly communicated to employees in the grant materials or employment-related documents/agreements.
Indonesia
Foreign public companies relying on a private placement exemption for purposes of offering equity grants in Indonesia must now request an exemption letter from the Financial Services Authority (Otoritas Jasa Keuangan, or OJK). The request for exemption requires companies to submit a cover letter and “information memorandum” detailing the overall business and expected plan administration in Indonesia. Most of the content can be compiled based on plan documents and other public company filings. Approval typically must be renewed annually. Failure to obtain approval may result in criminal or administrative sanctions.
Next Steps for Companies: Consider whether equity grants in Indonesia satisfy the private placement exemption. As a practical matter, the requirements and drafting of the information memorandum are straightforward, but the OJK often requires multiple reviews before granting approval (which can extend the approval process). Companies should factor additional time into their timeline for approval.
Israel
Effective January 1, 2025, the amended Income Tax Rules permit equity plans to be approved by the Israel Tax Authority via a new online platform. A new questionnaire also has been implemented as part of the amended process. Approval is required only if the plan utilizes a trust pursuant to Section 102 of the Israel Income Tax Ordinance.
The amended Income Tax Rules will also resume the quarterly and annual reporting obligations. Quarterly reports (Form 146) must be submitted within 120 days following the end of the quarter and generally include information regarding the terms of equity grants. Annual reports (Form 156) must be submitted by April 30 for the prior tax year and generally include information regarding grant vesting/exercise/transfer. The Israel Tax Authority is expected to release additional guidance regarding format and contents of the reports, which must be submitted online.
Next Steps for Companies: Begin compiling the applicable data. The first quarterly report is due July 29, 2025, for Q1 2025 activity and the annual report is due April 30, 2025, for calendar year 2024 activity.
United Kingdom
- Tax-Free Allowances – The tax-free allowance for dividend and capital gains taxes on employee shares has decreased in prior years. If amounts exceeded the tax-free allowance, employees generally needed to file an annual tax return. Under new guidance, employees can now contact HM Revenue & Customs (HMRC) to report applicable taxes. For dividend taxes less than or equal to £10,000, employees can call HMRC to request amounts are collected via pay as you earn (PAYE). For capital gains taxes, employees can report via an online HMRC portal.
Next Steps for Companies: Continue to include language in grant materials recommending grantees consult with a personal tax and/or legal advisor regarding participation in the plan. Given that filing an individual tax return is uncommon in the United Kingdom, also consider communicating these updates to grantees to ensure amounts are properly reported/collected prior to the January 31 deadline for annual tax returns.
- Tax Rates and Payroll – Effective October 30, 2024, the capital gains range of rates increased from 10 – 20% up to 18 – 24%. Effective April 6, 2025, the employer portion of national insurance contributions will increase from 13.8% to 15%. Additionally, the minimum income threshold for national insurance contributions will decrease from £9,100 to £5,000.
Next Steps for Companies: If grant materials or tax summaries reference tax/social contribution rates, continue to include language in grant materials recommending grantees consult with a personal tax and/or legal advisor regarding participation in the plan. Additionally, coordinate with local payroll teams to implement the tax rate and income threshold adjustments and ensure equity compensation is properly reported and taxed.
- Trusts – Additional tax reforms are expected with respect to employee ownership trusts and employee benefit trusts.
Next Steps for Companies: If equity benefits are provided through a trust, continue to monitor ongoing updates. Recognize that the use of trusts may also prolong the diligence process for cross-border transactions.
Vietnam
Multinational equity plans are typically subject to Decree No. 135/2015/ND-CP, regarding foreign equity plan administration in Vietnam. Circular No. 10/2016/TT-NHNN previously identified the applicable registration and reporting requirements, but such requirements were recently amended by Circular No. 23/2024/TT-NHNN (Circular 23). Generally speaking, Circular 23 simplifies plan administration in Vietnam.
Instead of waiting for approval from the State Bank of Vietnam (SBV), the local subsidiary in Vietnam can work directly with a commercial licensed bank to register and commence equity plan transactions. This is a welcome change considering the historically cumbersome document requests, signature requirements, and approval waiting period. Additionally, the reporting period has shifted from a quarterly basis to a monthly basis. Despite the increased reporting frequency (due the 12th of each month for prior-month activity), the reports no longer require individual grantee information and report entity information on an aggregated level (e.g., total value of transactions). Interaction with the SBV is now significantly reduced for both US and local Vietnamese entities.
Next Steps for Companies: For in-force equity plans, confirm that a process has been implemented to satisfy the monthly reporting obligations. For new equity plans, register the plan with the appropriate licensed bank and confirm whether such bank will assist with ongoing reporting requirements.
Looking Ahead
Our team is available to assist with additional questions and considerations regarding changes in the new year. We also provide annual compliance calendars to assist companies with tracking global equity and compensation plan filing and reporting deadlines. For more information about these calendars (which are customized based on the company’s current multinational presence and employee counts) or this summary, please contact a member of your McDermott team or one of the authors listed below.


Corporate Transparency Act Update: Preliminary Injunction Reinstated and Reporting Voluntary Once Again
ARTICLE / CLIENT ALERT
Corporate Transparency Act Update: Preliminary Injunction Reinstated and Reporting Voluntary Once Again
December 31, 2024
Read time: 4 min
On Dec. 26, 2024, the US Court of Appeals for the Fifth Circuit reinstated the nationwide preliminary injunction that enjoins enforcement of the Corporate Transparency Act (“CTA”) and its implementing regulation (31 C.F.R. §1010.380), including the filing deadlines thereunder.[1] The Fifth Circuit’s Dec. 26 order by the panel which will hear the pending appeal vacates an earlier order of a motion’s panel of the Fifth Circuit that had stayed the nationwide preliminary injunction pending the government’s appeal on the merits. The panel left in place an order expediting the appeal; oral argument on the merits of the government’s appeal is scheduled for March 25, 2025.
On Dec. 27, 2024, the US Department of the Treasury’s Financial Crimes Enforcement Network (“FinCEN”) issued a statement advising that “as of December 26, 2024, the injunction issued by the district court in Texas Top Cop Shop, Inc. v. Garland is in effect and reporting companies are not currently required to file beneficial ownership information with FinCEN.” The statement also advised that “reporting companies may continue to voluntarily submit beneficial ownership information reports” but “are not subject to liability if they fail to do so while the [nationwide preliminary injunction] remains in force.”
At this time, all beneficial ownership interest report (“BOI Report”) filings for both existing entities and newly formed/registered entities are voluntary. No BOI Reports are due on Jan. 1, 2025, or Jan. 13, 2025, which were prior BOI Report filing deadlines issued by FinCEN. Clients who defer filing BOI Reports should nonetheless continue to prepare for anticipated BOI Report filings in the event the nationwide preliminary injunction is vacated or modified. We will continue to monitor for developments related to this case, including whether the nationwide preliminary injunction gets vacated or modified and whether the Justice Department, the Treasury Department or FinCEN issues any additional guidance in order to assist clients in navigating any obligations under the CTA.
Authored by Melissa G.R. Goldstein, Betty Santangelo, Michael S. Didiuk, Jessica Romano, Kyle B. Hendrix and Bryson Kern.
For assistance in navigating the CTA’s reporting requirements, please contact one of the authors or your attorney at Schulte Roth & Zabel.
[1] For more information on the nationwide preliminary injunction, please see our prior Alerts: “Important Update – Corporate Transparency Act: Reporting Reinstated by Appellate Court and FinCEN Extends Deadline to Jan. 13”; “Corporate Transparency Act Update: Government Challenges Nationwide Preliminary Injunction & FinCEN Clarifies That Reports Are Voluntary”; and “Corporate Transparency Act Update: Nationwide Preliminary Injunction Enjoining Enforcement.”
This communication is issued by Schulte Roth & Zabel LLP for informational purposes only and does not constitute legal advice or establish an attorney-client relationship. In some jurisdictions, this publication may be considered attorney advertising. © 2024 Schulte Roth & Zabel LLP. All rights reserved. SCHULTE ROTH & ZABEL is the registered trademark of Schulte Roth & Zabel LLP.





Fifth Circuit Reinstates Nationwide Injunction Against Enforcement of the CTA
ARTICLE / CLIENT ALERT
Fifth Circuit Reinstates Nationwide Injunction Against Enforcement of the CTA
December 27, 2024
Read time: 3 min
On December 26, 2024, in response to an emergency motion for rehearing filed by plaintiffs, the US Court of Appeals for the Fifth Circuit reinstated the nationwide preliminary injunction against enforcement of the Corporate Transparency Act (CTA) (31 U.S.C. § 5336) and the Beneficial Ownership Information Reporting Requirements final rule (Final Rule) promulgated thereunder (31 C.F.R. 1010.380).
The injunction was originally entered by the US District Court for the Eastern District of Texas on December 3, 2024, in Texas Top Cop Shop, Inc., et al. v. Garland, No. 4:24-cv-00478 (E.D. Tex). On December 23, 2024, the Fifth Circuit motions panel had granted the US Department of Justice’s motion to stay the district court’s preliminary injunction pending appeal on the merits. The court explained that it was reinstating the injunction to preserve the constitutional status quo while the Fifth Circuit merits panel considers the parties’ weighty substantive arguments in this case. The Fifth Circuit has scheduled oral argument on the merits of this case for March 25, 2025.
Accordingly, the nationwide preliminary injunction against enforcement of the CTA and the Final Rule continues to apply. Entities are not currently required to comply with the reporting requirements of the CTA and the Final Rule.
Entities can, if desired, voluntarily submit Beneficial Ownership Information Reports (BOIRs) with the Financial Crimes Enforcement Network (FinCEN) at www.fincen.gov/boi. FinCEN had previously extended certain deadlines by which BOIRs need to be submitted (e.g., entities created or registered prior to January 1, 2024, were given an extended deadline of January 13, 2025, to file their initial BOIRs). However, no such reporting is currently required.
McDermott will continue to monitor for relevant developments. If you have any questions or need advice about the CTA or its application to your business, please contact your regular McDermott lawyer or one of this client alert’s authors.


Corporate Transparency Act Update: Nationwide Injunction Stayed; Deadlines Extended
ARTICLE / CLIENT ALERT
Corporate Transparency Act Update: Nationwide Injunction Stayed; Deadlines Extended
December 26, 2024
Read time: 3 min
On December 23, 2024, in response to an emergency motion by the US Department of Justice, the US Court of Appeals for the Fifth Circuit stayed the nationwide preliminary injunction against enforcement of the Corporate Transparency Act (CTA) (31 U.S.C. § 5336) and the Beneficial Ownership Information Reporting Requirements final rule (Final Rule) promulgated thereunder (31 C.F.R. 1010.380), which was entered by the US District Court for the Eastern District of Texas on December 3, 2024, in Texas Top Cop Shop, Inc., et al. v. Garland, No. 4:24-cv-00478 (E.D. Tex).
Accordingly, entities not otherwise exempt from the CTA will need to comply with reporting obligations under the CTA and the Final Rule. However, the Financial Crimes Enforcement Network (FinCEN) has extended certain deadlines by which Beneficial Ownership Information Reports (BOIRs) will need to be submitted. Importantly, nonexempt reporting companies created or registered on or after January 1, 2025, will continue to have 30 days to file their initial BOIRs.
The extended reporting deadlines include the following:
- Reporting companies that were created or registered prior to January 1, 2024, have until January 13, 2025, to file their initial BOIRs. (These companies would otherwise have been required to report by January 1, 2025.)
- Reporting companies created or registered on or after September 4, 2024, that had a filing deadline between December 3, 2024, and December 23, 2024, have until January 13, 2025, to file their initial BOIRs.
- Reporting companies created or registered on or after December 3, 2024, and on or before December 23, 2024, have an additional 21 days from their original filing deadline to file their initial BOIRs.
- Reporting companies that qualify for disaster relief may have extended deadlines that fall beyond January 13, 2025. These companies should abide by whichever deadline falls later.
- Reporting companies that are created or registered on or after January 1, 2025, have 30 days to file their initial BOIRs.
The plaintiffs filed an emergency motion for rehearing en banc from the Fifth Circuit. Until a ruling on that motion, the reporting requirements under the CTA and the Final Rule are in force effective immediately and reporting companies should be prepared to submit their BOIRs by the applicable deadlines, as extended by FinCEN.
Read more about the Fifth Circuit’s order and the district court’s underlying injunction order.
McDermott will continue to monitor for relevant developments. If you have any questions or need advice about the CTA or its application to your business, please contact your primary McDermott lawyer or one of the authors of this article.
December 26, 2024: Fifth Circuit Reinstates Nationwide Injunction Against Enforcement of the CTA