ARTICLE
Where healthcare exits are heading in 2026
December 2025
Read time: 5 min
As we look to 2026, exits aren’t just about timing. Dealmakers are utilizing process, planning, and creativity to find new paths to liquidity. Investors across healthcare sectors are looking to dynamic opportunities while integrating flexible exit pathways and regulatory readiness to maximize values.
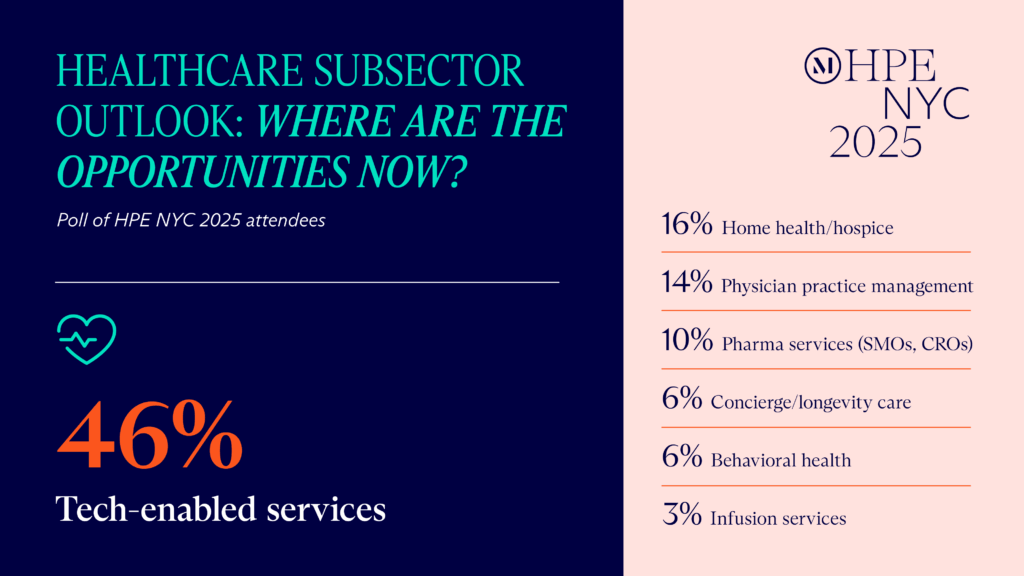
At McDermott Will & Schulte’s HPE NYC 2025 conference, industry leaders explored new sectors alongside investors’ shifting focus to innovative and deliberate exits. Here, we continue the conference conversations with a review of emerging opportunities and strategic exits amid regulatory developments.
Emerging opportunities
- Development and commercialization partnerships. Strategic acquirers are increasingly targeting tech-enabled contract research organizations and commercialization platforms as initial public offerings (IPOs) and cross-border activity lag. To illustrate, our event panelists noted investments in drug manufacturing, supply chains, and drug administration (including pharmacies and infusion centers). Liquidity is consolidating around those strategic acquirers, which are historically slower to get to closing and do not pay a private equity premium.
- Pharmaceutical industry. HPE NYC panelists expect increased mergers and acquisitions activity in the pharmaceutical industry. Specifically, looming patent cliffs and the resulting need to replace lost revenue make late-stage, de-risked assets strong targets with strategic advantages. Additionally, the panelists pointed to potential for partnerships in artificial intelligence (AI) and other technologies, which would enable the development of increasingly comprehensive data collection and maintenance via life sciences services.
- Behavioral health. Demand and competition continued to grow in the behavioral health sector, with valuation rates tracking the realities of contract structures, operational stability, and reimbursements. Notably, the increasing role of technology is helping enhance success rates and implement evidence-based care while boosting efficiency in the sector.
- Investor-payor collaboration. Our panelists pointed to the desirability of pursuing potential partnerships to mitigate current pressures facing physician groups. Collaboration with payors would help reduce reimbursement lags and offer opportunities to launch lab services.
Creative exits
- Flexible pathways. Private equity is turning to continuation vehicles and sponsor-to-sponsor trades for flexible exit pathways, maximizing value as the market’s appetite for IPOs is diminished.
- Trial execution. Platforms that enhance trial execution, including in the oncology and central nervous system spheres, offer another framework for creating exits. HPE NYC panelists pointed out that, given the financial risks in the trial arena, venture capital investment is common.
- Physician practice management (PPM). The panelists further highlighted the stability and potential for tech enablement in the PPM sector, predicting an uptick in exits over the next few years. PPM organizations are less impacted by the macro dynamics and regulatory issues affecting other industry businesses, and the improvements driven by technology should solidify exit opportunities.
Regulatory readiness
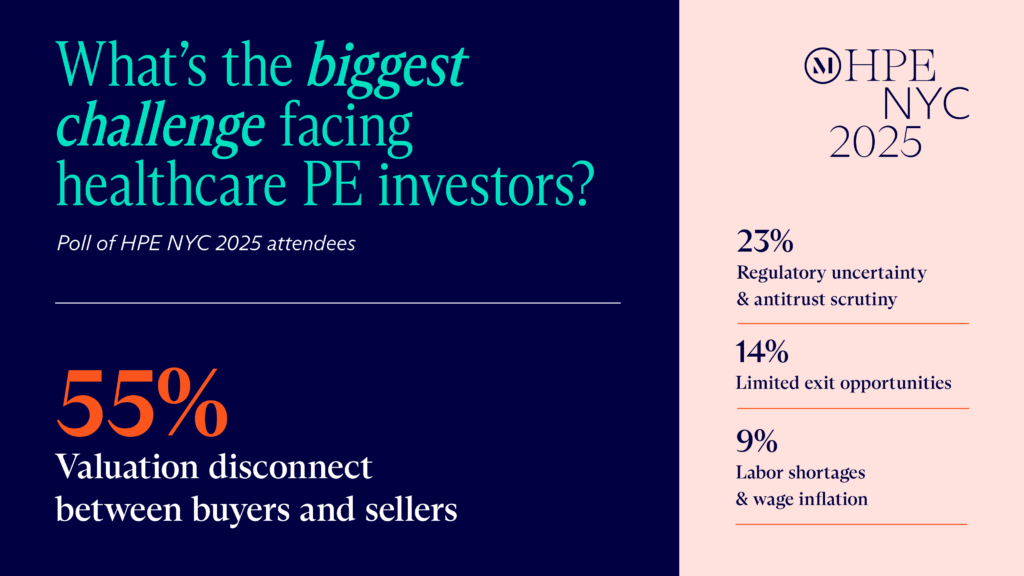
Investors face growing risks from fragmented state privacy laws, HIPAA and Federal Trade Commission enforcement, and US Food and Drug Administration scrutiny of AI. In fact, 50% of HPE NYC 2025 attendees believe that navigating complex regulatory and compliance landscapes is the most significant nonfinancial challenge faced by private equity firms investing in healthcare. Federal and state regulators are imposing new notice and approval requirements that have significant transaction implications for healthcare providers, industry operators, dealmakers, and investors.
- Baby HSR. Modeled on the federal Hart-Scott-Rodino (HSR) Act, “Baby HSR” or “mini-HSR” laws are state laws that impose notice and approval requirements on parties to certain healthcare transactions. While the timing and details vary by state, event panelists noted concern that these relatively new regulations will delay deals. As an initial matter, parties should monitor Baby HSR laws in the states in which they operate (or plan to operate) and consider the impact that doing business in a state may have on the timing of future exit transactions.
- Work with lawmakers. When new laws are proposed, it may be wise to turn to lobbyists or public relations firms in an effort to minimize current deal disruptions or future exit delays. Building relationships with lawmakers is key, as is communicating the positive results healthcare investors have achieved – and continue to achieve – in their communities.
- Readiness audits. A review of the relevant state’s filing requirements is essential before going to market. Readiness audits completed in conjunction with regulatory preparedness help effectively position assets in both strategic and sponsor exits. In addition to managing the deal timeline, that analysis may provide alternative structures to minimize filing requirements.
Conclusion
Looking toward increased activity in dynamic sectors and creative exit opportunities, stakeholders should consider the impact of regulatory reforms across the healthcare industry.
As always, we look forward to continuing the conversation with our clients and partners. To explore these topics further, please reach out to a member of the firm’s Health & Life Sciences Practice Group.



Unlocking global data center opportunities
ARTICLE
Unlocking global data center opportunities
December 2025
Read time: 7 min
Key takeaways
- The accelerated rise of AI is driving demand for high-density data centers.
- These data centers require massive amounts of power, and the grid is ill-equipped to handle such power.
- In addition to traditional data center development opportunities, there is an investment opportunity around onsite electricity generation that requires significant capital for growth.
- This is an innovative space: new chips, cooling technologies, and designs; battery storage; collocated solar and wind power; and small modular nuclear reactors solutions are fast-emerging.
- New financing structures are being developed to fund powered land and powered shell opportunities or to refinance stabilized assets.
- There are geopolitical and regulatory issues to navigate in both the US and Europe.
The recent surge in generative artificial intelligence (AI) has resulted in an arms race to develop the technology, which will require many high-density data centers and significantly more electricity to power them. That challenge is creating a swathe of investment opportunities for private funds across debt, equity, energy, and infrastructure, right at the intersection of two global megatrends: digitization and decarbonization.
What is clear is that the global data center market is in serious need of power, further fueled by the growth of cryptocurrencies, and the traditional grid is not equipped to respond. Consequently, energy providers well-versed in data center developers’ needs are pursuing onsite electricity generation options, leading to interesting new structures in both the United States and Europe.
What is emerging is a market opportunity characterized by innovation, scale, and a deep need for capital. With traditional capital providers increasingly limiting their lending, private credit is seen as a growing source of finance at a time when deals are getting larger and the geopolitical and regulatory context is more challenging.
AI has created an arms race that will require many high-density data centers and significantly more electricity to power them.
Diversification of power essential
While electricity grids are under intense pressure, in all but extreme cases power is still available – just not necessarily where data centers are located. That means instead of bringing power to data centers, data centers need to be built near new power sources.
Developers must either improve data connectivity to and from those new sites or build onsite electricity generation as a complement – but rarely a total substitute – to the grid, an option known as behind-the-meter generation.
As the ability to deliver data center capacity quickly becomes crucial, data center owners and developers are increasingly offering their tenants – most often large US tech companies, or hyperscalers – solutions to bridge a temporary lack of capacity. Alternative power sources are installed to increase the site’s total capacity and provide backup power in case of grid deficiencies. While the market for renewable energy powered data centers continues to grow, this is progressively done via the installation of gas turbines which, once the onsite plant is built, then transition to a backup role.
At full production capacity, a data center powered by onsite generation has the added advantage of potentially selling surplus power back to the grid. This could help avoid a loss of production capacity and alleviate some of the financial pressure on the overall project.
Innovation’s impact
Ironically, AI will accelerate innovation and substantially affect how data centers are designed, powered, and connected to networks. A world where IT drives the economy represents an entirely new paradigm, one that will lead humanity into uncharted territory.
The current race for advanced chips and the pursuit of superintelligence – an intelligence that surpasses human capability – is a striking example of how the data center sector will evolve over the next decade.
Square footage is becoming less important as servers become more efficient. But these servers require significantly more power and cooling to function, and their numbers have increased dramatically. In response to that new challenge, small modular nuclear reactors are expected to be operational and deployed across data centers within two to four years. Similarly, solar and wind power generation is improving, and the use of hydrogen sources is being regularly tested.
Financing behind-the-meter data centers
We see a growing number of private funds exploring data center power opportunities. Powered land (or land with a timeline to power) in or near a cluster of existing data centers is seen as the golden ticket.
The market is also pursuing powered shells, on which data centers matching hyperscaler designs can be developed. These can either be rented with an option to purchase or purchased once built.
A similar logic is emerging for onsite power generation. Energy developers are buying large tracts of land, securing a connection to the grid, and building initial onsite generation plants. This first move is generally financed through equity and followed by a series of debt financing.
Once the initial groundwork is in place, developers seek equity partners to finance part of the construction of the data center through a joint venture. The remainder is financed through debt at the joint venture level, with lenders secured by a series of subordination, non-disturbance, and attornment agreements; enforcement rights; and, ultimately, the lease secured with the anchor tenant. Given that the overall power capacity may not be fully delivered at this stage, some projects rely on additional mezzanine financing.
The final step for the energy company that initiated the project is to secure additional funding to complete and build the onsite generation plant. This not only delivers a reliable primary power source for the existing buildings but may attract new customers who may request the construction of additional data center buildings powered by the plant.
The markets continue to evolve
The current global market capacity of data centers is approximately 59 gigawatts (GW), and Goldman Sachs estimates there will be around 122GW of data center capacity online by the end of 2030.
The US currently represents approximately 50% of globally installed data center capacity and looks set to account for the majority of data center power demand growth. This reflects the presence of many major hyperscalers, plus good access to reliable energy, strong connectivity, a low country risk profile, and a favorable regulatory environment.
The US Department of Energy recently directed the Federal Energy Regulatory Commission (FERC) to initiate a rulemaking process to expedite grid interconnection for data centers, aiming to ensure the grid can keep up with demand and processes are smoothed out. It remains to be seen how that proposal, which essentially expands FERC’s jurisdiction over the interconnection of large loads, will be met by state regulators.
Conclusion
The construction of high-density data centers and quickly increasing electricity demands present vast opportunities for private capital to support both data center and power project developers, and particularly those capable of bridging the two domains.
As deals continue to get larger and the pace of innovation intensifies, investors who can adeptly navigate these trends will be well positioned to capitalize on a meaningful growth trend.



Hybrid financing in life sciences: Unlocking growth amid market challenges
ARTICLE
Hybrid financing in life sciences: Unlocking growth amid market challenges
December 18, 2025
Read time: 5 min
Life sciences companies and investors continue to navigate a complex and challenging investment landscape – marked by high interest rates, a volatile regulatory environment, tight venture capital (VC) markets, and slowly rebounding initial public offering (IPO) activity. Even so, the sector’s deep reliance on partnerships with major pharmaceutical companies and innovative MedTech providers is keeping deal activity alive, enabling strong performers to secure capital while driving life sciences advancements.
Against this backdrop, alternative financing strategies are no longer niche – in life sciences especially, they’re now essential. As costs continue to rise and pricing and reimbursement headwinds shift commercial assumptions, hybrid and crossover financing models – including royalty financing, innovative debt structures, and flexible capital stacks – are reshaping how capital is deployed across the life sciences sector and changing how deals get done.
Hybrid financing structures are helping catalyze sector growth and value creation, giving investors earlier, less crowded access to life sciences and MedTech operators. Blended finance approaches are helping companies secure better pricing and deal terms, de-risk investments, and position investors for significant upside when market favorability returns. And as life sciences mergers and acquisitions (M&A) accelerate and buyers look to acquire earlier in the development cycle, hybrid financing has become a critical bridge to acquisition – giving target companies the capital influx needed while providing investors structured protections and multiple paths to liquidity.
Creative financing and dealmaking options are also helping life sciences companies keep up with the rapid pace of scientific progress, while maintaining cash reserves to drive growth, development, and top-line success. At the same time, investors are structuring deals focused on creating value for all parties, whether that’s co-investing with VCs or partnering with strategics to reduce risk.
With these key trends in mind, what should life sciences investors and targets focus on for dealmaking success in 2026 and beyond? Six actionable steps include:
1. Spread financial risk and remain competitive
In a crowded market, creative life sciences dealmakers must move beyond binary “exit-or-bust” financing models to achieve success. Royalties, build-to-buy, or partial-liquidity structures help spread financial exposure while letting investors capture upside from pivotal inflection points like regulatory approvals and asset development milestones. These flexible structures give companies access to needed capital without forcing premature exits or excessive dilution.
2. Prioritize metrics and measurement
A comprehensive risk management strategy must include internal metrics and measurement to evaluate hybrid deal performance, such as milestone-to-capital spend ratios, actual vs. modeled probability-of-success curves, non-dilutive capital leverage, structured-return realization rates, and portfolio-level hybrid exposure concentration. Investors who make measurement a strong, repeatable capability will shape the next wave of investment wins and market norms.
3. Match funding models and capital needs to sector dynamics
Not every funding model works everywhere or at every point in time. In MedTech, hybrid financing options can shorten the path to commercialization, giving companies timely, flexible access to capital during the incredibly expensive clinical, regulatory, and scale-up phases. By reducing dilution and funding critical milestones without delays, companies and investors can accelerate launch preparation and reach commercialization faster. For specialty pharma, on the other hand, royalties may be a simpler investment approach, given fewer operational entanglements, clearer economics, and more predictable risk/return characteristics. Leveraging advisors with deep life sciences industry knowledge around the models that resonate in specific sectors can help investors move quickly and ensure alignment among stakeholders.
4. Build the right syndicate early
Deals succeed when investors line up and begin their due diligence before a capital raise is critical. Now more than ever, investors need to build strong relationships and explore proactive deal terms with potential partners well before a formal fundraising round begins, including providing strategic advice and expertise. This forward-looking, collaborative approach often leads to more favorable deal terms, better strategic alignment, and a smoother overall fundraising process for both parties, reducing the pressure and competition typical of later-stage, more crowded raises.
5. Treat hybrids as a core strategy, not a side bet
Hybrid structures allow for a combination of high-growth potential assets, which carry higher risk, with more de-risked or cash-flowing assets, thereby creating a more stable portfolio with longer-term viability. Embedding hybrid structures into the core investment playbook – not just using them opportunistically – creates more consistent returns across cycles and improves resilience when traditional equity markets are tightened.
6. Embrace the power of secondary markets
Secondary markets are opening new pathways for early investors to realize liquidity well before traditional exits. In the life sciences sector, secondary markets help investors and founders unlock capital even while clinical trials are ongoing or regulatory milestones are pending, reducing pressure to sell under suboptimal conditions, such as today’s unpredictable reimbursement and regulatory ecosystem. Secondary markets also help new investors acquire stakes in later-stage, more derisked companies, meaning investors can participate in the upside of targets with validated pipelines, established manufacturing capabilities, or early revenue streams, while mitigating the operational and clinical risks that often challenge earlier-stage ventures.
The life sciences sector is at an exciting inflection point, with headwinds and opportunities aplenty. But as we think about the actual assets that are coming online – those with high-ROI potential and thus ability for continued reinvestment into growing pipelines – hybrid financing options represent the kind of creative, strategic dealmaking that will drive scientific and technological advancements now and in the future.



Strategic investments in sports full article
ARTICLE
Emerging leagues, emerging opportunities: Strategic investments in new professional sports
From the Private Markets Update 2026 report
Read time: 7 min
Key takeaways
- Professional sports represent a sought-after investment sector, with valuations continuing to climb.
- There are a growing number of investment opportunities in emerging sports like pickleball, lacrosse, and women’s soccer.
- New investors are entering space, including current and former athletes, private equity firms, and high-net-worth individuals.
- Tech investors can help sports leagues use new means to monetize IP and expand fan bases.
- Emerging sports leagues can be nimbler and more innovative in how they build visibility and reward players.
- More dealmaking in emerging sports leagues is expected in 2026.
Professional sports is currently one of the hottest sectors in the United States, as enterprise valuations of teams continue to dramatically increase. Historically, the preserve of ultra-high-net-worth individuals where investment opportunities arose once in a generation, the relaxation of league shareholding rules, and a growing appetite among institutional investors have fueled a robust and vibrant deal environment.
In August 2025, McDermott Will & Schulte represented Aditya Mittal and trustees of the Mittal family trusts as part of a buying group led by William Chisholm that acquired the National Basketball Association’s Boston Celtics for $6.1 billion. At the time, it was the largest sale of a US professional sports team in history. But the value of professional sports sector deals continues to climb, boosted by eye-popping media deals and investors attracted to stable revenue streams and loyal fan bases.
As high valuations continue to bring more sellers to market in the big four US professional sports of football, basketball, hockey, and baseball, investors that do not have billions at their disposal are starting to look deeper into the sector. We are seeing the interest in emerging sports increasing as investors continue to look for new angles and networks remain hungry for sports content to satisfy viewers.
All eyes on emerging sports
So, what are those emerging sports presenting attractive investment opportunities? Pickleball, lacrosse, women’s soccer, padel, bull riding, drone racing, and various forms of football (such as flag football, spring football, and women’s football) are all gaining momentum. We recently closed a transaction in women’s volleyball, now one of the most popular women’s sports in the US.
As the range of opportunities grows, the range of investors accessing the sector is also diversifying. Anyone with capital is now able to participate.
We have seen many deals spearheaded by current and former athletes. Magic Johnson, a Los Angeles Lakers legend, was a trailblazer in showing professional athletes that they can use their fame and money to lead lucrative investing careers once their playing days are over. As the salary cap increases across top professional sports leagues to keep up with the league’s revenue, professional athletes have more money to spend.
Smartly, and with the right advice, athletes are realizing that with any investment, starting earlier is better. Even before making it to the professional ranks, name, image, and likeness (NIL) deals are affording college athletes the ability to make money and subsequently invest where they see fit, including in emerging sports.
Paige Bueckers, while a star on University of Connecticut’s women’s basketball team, received equity in Unrivaled, the three-on-three basketball league, in connection with signing an NIL deal.
Not only do current and former athletes have capital, but they also add value to these leagues. For example, Houston Rockets forward Kevin Durant and tennis pro Naomi Osaka are becoming the unofficial faces of pickleball while former professional women’s basketball player Candace Parker’s investment in the National Women’s Soccer League’s Angel City FC allows them to leverage her personal brand and increase visibility for the team.
Private equity firms, which have entered the top US sports leagues in the last five years, are also starting to enter emerging sports. We have already seen deals completed in the National Women’s Soccer League, the Professional Fighters League, lacrosse, padel, and SailGP, the new global sailing competition.
There is a growing opportunity for high-net-worth individuals, too. While ownership in the top sports leagues is reserved for those with net worths over the billion-dollar range, individuals who have substantial wealth at a slightly lower level are using emerging sports as a new way to deploy capital.
The rules of the major professional sports leagues include express protection for control owners to ensure team and league stability. Private equity investors must hold passive stakes and, in general, most control owners would prefer that any new investors in their capital tables take a passive role.
By contrast, emerging leagues are looking for active investors that can help them grow the sport. Synergies via partnerships, brand recognition, and past success in the sports business arena are characteristics that emerging sports leagues are looking for in an investor.
Technology in sports
Successful Silicon Valley tech investors have become a large portion of the investor pool for sports teams because of their accomplishments, capital, and ability to provide synergistic value. Sports are intellectual property (IP), and technology is the most efficient method for monetizing this IP.
Technology connects people so that a league based in the US can establish a global audience. The technology can be as straightforward as having players mic’d up during a game or as in-depth as using artificial intelligence to obtain fan data that can subsequently be used to pitch sponsorships, enhance the fan experience, and direct marketing according to fans’ personalized data sets.
A win-win opportunity
The major professional sports leagues are firmly established, but emerging sports leagues have the room and passion to innovate and shape their sports – both on the field and off – to cater to a modern audience. Like the top sports leagues, media contracts will be a significant driver of success. With the right visibility, an emerging sports league can explode overnight.
There is no better example than pickleball. Rarely do you find a sport that can be played by both a 70-year-old and a 10-year-old. Pickleball is popping up all over the country, including on our TVs, and investors see an incredible opportunity to monetize that.
With the right visibility, an emerging sports league can explode overnight.
Certain emerging sports leagues, like the Premier Lacrosse League, which recently signed a long-term contract with ESPN, are sharing the league’s upside potential with their players via creative player equity participation programs. These are possible because emerging sports leagues are more nimble, less focused on rules and regulations, and more focused on pure growth. The lack of league red tape allows emerging sports leagues to scale at a faster rate with rapid decision-making.
Conclusion
The top professional sports leagues are not taking their foot off the gas, and fighting for fan time, attention, and money will not be easy for emerging sports leagues. But these new leagues are taking advantage of a fast-evolving media landscape that provides multiple ways for fans to consume sports in order to break through to their fan base.
These emerging leagues are looking for enthusiastic, proven, strategic investors to help them find and expand their market, and investors are increasingly looking for these opportunities to get in on the “next big thing” in sports. We expect more deals to take place in 2026 as dealmakers broaden their horizons and the scope of the opportunity within the sports sector continues to rise.
At McDermott, we know sports are more than just games—they’re global businesses, cultural touchstones, and platforms for innovation. Our sports law team works at the intersection of law, business, and culture, guiding clients through regulatory challenges, advising on high-profile transactions, managing labor matters, and addressing critical IP issues.
In the past year, McDermott has advised on transactions totaling almost $10 billion in value. Beyond structuring transactions, we help clients create lasting value that extends well beyond the season.


Vague definitions deflate tire trade secret claims
ARTICLE
Vague definitions deflate tire trade secret claims
Dec 18, 2025
Read time: 4 min
The US Court of Appeals for the Federal Circuit affirmed a district court’s judgment as a matter of law (JMOL) that the plaintiff failed to prove misappropriation of five alleged trade secrets related to self-inflating tire (SIT) technology and separately rejected the plaintiff’s claim for correction of inventorship of defendant’s patent related to the alleged trade secrets. Coda Dev. S.R.O., et al. v. Goodyear Tire & Rubber Co., et al., Case No. 23-1880 (Fed. Cir. Dec. 8, 2025) (Lourie, Dyk, Cunningham, JJ.)
Coda sued Goodyear in the Northern District of Ohio, alleging that Goodyear misappropriated trade secrets disclosed during SIT-technology collaboration discussions and that Coda’s founder should be added as an inventor on Goodyear’s patent related to the same technology. A jury initially found for Coda on five trade secrets (TS 7, 11, 20, 23, and 24) and awarded more than $64 million in compensatory and punitive damages. The district court, however, granted Goodyear JMOL, holding that the asserted trade secrets were insufficiently definite, not secret, and/or never used or disclosed by Goodyear. It later denied Coda’s inventorship claim of a Goodyear patent related to the alleged trade secrets after a bench proceeding. Coda appealed.
Trade secret claims
TS 24 concerned the “optimal” pump location in a tire sidewall above the rim. The Federal Circuit found that Coda had already disclosed this placement in a 2007 PCT application and a 2008 Tire Technology article, both of which discussed pump placement in the sidewall. At trial, Coda confirmed that these publications described the same location. The Federal Circuit determined that because the information was public, it could not be a trade secret.
Coda’s attempt to narrow TS 24 post hoc by adding qualifiers such as “conventional tire sidewall” failed because those limitations did not appear in Coda’s interrogatory responses in compliance with the district court’s order to provide “a complete list of the trade secrets (with particularity).” The Federal Circuit rejected Coda’s attempt to belatedly introduce additional specificity into the trade secret based on trial testimony and attorney arguments.
The Federal Circuit similarly affirmed that TS 7, 11, and 20 (which described broad categories of SIT system components and functions) failed the definiteness requirement. Each trade secret identified a list of desired features but did not specify the underlying “design and development” knowledge Coda claimed to own. Without a concrete articulation of the claimed technical know-how, the Court found that the descriptions were too vague to distinguish trade secret information from general design concepts already known in the field.
TS 23 comprised a set of pump-pressure test results. At trial, Coda offered only a single 2009 email that mentioned one of the pressure values listed in TS 23. The Federal Circuit found that this partial overlap could not sustain a verdict of “use,” particularly when no evidence showed Goodyear had received or relied on the totality of the testing data. The Court also found that Coda’s arguments about Goodyear proceeding with its SIT project after the email failed to establish a causal link to TS 23.
Inventorship challenge
Coda argued that because Goodyear allegedly misappropriated TS 24 and used it in its patent, Coda’s founder should be named as an inventor. The Federal Circuit rejected this argument, finding that the trade secret claims failed and left no basis for an inventorship claim tied to misappropriated information. Even on the merits, the district court found, and the Federal Circuit agreed, that TS 24 and the patent claims did not cover the same subject matter. Because inventorship requires proof of conception of every claim element, Coda’s alleged trade secrets could not supply the necessary evidence to sustain the claim.
Practice note: This decision underscores the heightened requirement that trade secrets be articulated with specificity, especially in technical fields. Describing categories of features or broad functional capabilities is insufficient; plaintiffs must isolate the precise technical information claimed to be secret. The decision also confirms that public disclosures, even by the plaintiff, are fatal.




Sedona Conference releases draft model DTSA jury instructions
ARTICLE
Sedona Conference releases draft model DTSA jury instructions
Dec 18, 2025
Read time: 5 min
The Sedona Conference published the first comprehensive draft Model Jury Instructions for the Defend Trade Secrets Act of 2016 (DTSA) and invites public comment through January 17, 2026. The draft instructions, which have been three years in development, aim to provide clear, consensus-driven guidance on the key issues that juries must resolve in DTSA cases, against the backdrop of an evolving and often inconsistent body of federal trade secret law.
Background
Although the DTSA has been in effect since 2016, federal courts are only now beginning to generate a meaningful body of appellate decisions interpreting the statute, largely because of the slowdown in trial activity during the COVID-19 pandemic. According to the Sedona Conference’s announcement, more than 9,600 federal trade secret cases were filed between 2017 and 2022, but only about 300 reached a jury verdict in that period. This emerging landscape has underscored the need for model jury instructions that can guide courts and litigants in identifying, framing, and presenting DTSA issues at trial.
The draft instructions were prepared by members of the Sedona Conference Working Group 12 on Trade Secrets, a group dedicated to developing nonpartisan, consensus-based principles for managing trade secret litigation. As described in the commentary, the working group has published influential guidance on governance of trade secrets, clean room practices, and interorganizational sharing of confidential information.
Overview of the draft instructions
The Model Jury Instructions consist of core DTSA concepts and follow a familiar model instruction format, pairing proposed instructions with supporting authority and explanatory commentary. As summarized in the one-page publication outline, the instructions cover an introduction to DTSA claims, the elements of misappropriation, existence of a trade secret, misappropriation theories, and damages.
Key issues highlighted in the draft
Identifying trade secrets with “sufficient particularity”
Recent cases suggest that in some circumstances, the jury may need to decide whether the asserted trade secrets have been identified with sufficient specificity, although most practitioners agree that courts should police this issue before trial. This specificity requirement reflects a growing tension between early disclosure obligations and strategic concerns about revealing sensitive information.
What constitutes “reasonable measures”?
Whether a plaintiff took “reasonable measures” to maintain secrecy remains a fact-intensive inquiry. The commentary notes emerging case law holding that general confidentiality policies, cybersecurity protections, or “need to know” restrictions may be insufficient if not specifically tied to the trade secrets at issue. At least one court has suggested that failing to affirmatively tell an employee that a piece of proprietary information (such as source code) is a trade secret may defeat DTSA protection.
Combination trade secrets and proof of misappropriation
The draft rejects a patent-style “all-elements” test and instead endorses assessing substantial similarity between the combination trade secret and the accused method or system. This recommendation reflects a shift away from rigid element-by-element comparisons toward more flexible, fact-driven analyses.
Whether retention alone can constitute misappropriation
One unresolved issue is whether mere retention of trade secret information (once lawfully acquired) can qualify as improper acquisition under the DTSA. The commentary notes a lack of consensus and cautions practitioners to be aware of jurisdictional variation.
Damages: Extraterritoriality, burdens of proof, and apportionment
The draft instructions underscore that damages under the DTSA remain one of the most unsettled areas of trade secret law, with courts diverging on multiple foundational questions. A key issue is the statute’s extraterritorial reach. Following the US Court of Appeals for the Seventh Circuit’s 2024 Motorola v. Hytera decision, a plaintiff may recover for foreign conduct if at least one act “in furtherance” of the misappropriation occurred in the United States, but what constitutes such an act is a highly fact-specific and still-developing inquiry.
The draft also highlights uncertainty surrounding unjust enrichment damages, including whether the judge or the jury should decide them – an issue that has led many courts to submit the question to juries while acknowledging that the law is unsettled. Courts also disagree on the burdens of proof for disgorgement, with some requiring plaintiffs to prove only the defendant’s sales before shifting the burden to the defendant to prove profits while others require plaintiffs to attempt to show profits attributable to the misappropriation.
The commentary notes that the law has not yet converged on a clear standard for apportionment, particularly where a defendant’s product incorporates multiple trade secrets or significant non-secret technology. The open question is whether plaintiffs must disaggregate the value contributed by each asserted secret or whether they may instead seek recovery tied to the overall value of the resulting product or system.
Collectively, these uncertainties reflect the DTSA’s relative newness and signal that damages will continue to be a fertile ground for litigation strategy and doctrinal development.
Practice note: These draft instructions offer courts and practitioners a much-needed framework for navigating DTSA claims and are likely to influence judicial practice even before a final version is adopted. Litigators should pay particular attention to the commentary on particularity, reasonable measures, and combination trade secrets, as these issues continue to generate significant motion practice and divergent results in federal courts.
IRS roundup: November 25 – December 10, 2025
ARTICLE
IRS roundup: November 25 – December 10, 2025
Dec 16, 2025
Read time: 5 min
Check out our summary of significant Internal Revenue Service (IRS) guidance and relevant tax matters for November 25, 2025 – December 10, 2025.
November 25, 2025: The IRS released Notice 2025-70, requesting comments on the implementation of a new individual tax credit under the newly enacted Section 25F under the One Big Beautiful Bill Act (OBBBA). Beginning in 2027, taxpayers may claim up to $1,700 under Section 25F for contributions to Scholarship Granting Organizations that provide scholarships for elementary and secondary school students from low- and middle-income families. Comments are due by December 26, 2025.
November 25, 2025: The IRS released Notice 2025-72, providing guidance on the OBBBA’s repeal of the one-month deferral election under Section 898(c)(2) for specified foreign corporations (SFCs), effective for taxable years beginning after November 30, 2025. For SFCs that previously elected a one-month deferral, the first required tax year will be a short period ending on the same date as their majority US shareholder’s tax year. The notice addresses administrability concerns and provides a method for allocating foreign income taxes between this short year and the next year for subpart F, global intangible low-taxed income (GILTI), and foreign tax credit purposes. The notice also previews proposed Section 987 regulations that would modify the 10-year transition election for recognizing pre-transition gain or loss, allowing ratable recognition over 120 months. Comments are requested by January 24, 2026, particularly on the allocation rule and other multiyear provisions affected by short tax years.
December 2, 2025: The IRS released Notice 2025-68, which addresses the new Trump Accounts. Created by the OBBBA, Trump Accounts are a type of traditional individual retirement account for individuals under 18 years of age who have a social security number issued before the date of the election. The notice provides initial guidance on the potential benefits of these accounts and outlines details of the pilot program under Section 6364. Comments on the guidance are due by February 20, 2026, though the IRS notes that proposed regulations governing the election to open a Trump Account and the pilot program contribution election under Section 6434 may be issued before the comment period closes.
December 3, 2025: The IRS released Announcement 2025-22 and Announcement 2025-23, identifying taxpayers and the amounts of Section 48C credits allocated for projects that received certifications under the Section 48C(e) advanced energy project program. Section 48C(e)(1) directs the secretary of the treasury to establish a program to award certifications for qualified investments eligible for Section 48C credits. The US Department of the Treasury and the IRS provided two allocation rounds. Announcement 2025-22 lists Round One taxpayers and allocations, and Announcement 2025-23 lists Round Two taxpayers and allocations.
December 4, 2025: The IRS released Notice 2025-75, which provided a transition rule and proposed regulations that modify the application of Section 951(a)(2)(B) following the OBBBA changes for certain controlled foreign corporation (CFC) taxable years beginning before January 1, 2026. The notice clarifies that reductions to subpart F income and GILTI inclusions will not apply to dividends that do not increase a US person’s taxable income, with determinations made on a share-by-share basis. Subpart F and GILTI inclusions will now be linked to actual ownership periods to prevent any redundant overlaps. Dividends subject to the transition rule include those paid or deemed paid before a US shareholder acquires stock and those paid after June 28, 2025, but before the CFC’s first taxable year beginning after December 31, 2025. The notice also previews look-through rules for dividends received by partnerships and S corporations. Comments on this guidance are due by February 2, 2026, and taxpayers may rely on these rules until proposed regulations are issued, provided they apply them consistently and in their entirety.
December 4, 2025: The IRS released Notice 2025-77, offering interim guidance on the effective date of the OBBBA amendment to Section 960(d)(4). The amendment reduces the haircut applied under Section 960(d)(4), which reduces the foreign tax credit from 20% to 10% for certain previously taxed earnings and profits (PTEP) distributions because of a Section 951A(a) inclusion. The Section 960(d)(4) haircut becomes effective for inclusions occurring after June 28, 2025. The notice clarifies that the effective date is determined by the US shareholder’s taxable year, not the CFC’s, and introduces new PTEP tracking requirements that bifurcate Section 951A PTEP accounts into pre- and post-June 28, 2025, categories. The IRS also announced plans to modify the 2024 proposed PTEP regulations to align with the notice.
December 4, 2025: The IRS released Notice 2025-78, clarifying how the OBBBA’s exclusion from foreign-derived deduction-eligible income (FDDEI) applies to income from sales or dispositions of intangible property and property subject to depreciation, amortization, or depletion. The exclusion, effective for transactions after June 16, 2025, does not cover copyrighted works and generally does not apply depreciable property unless the property has been depreciable in the hands of the taxpayer. The notice also introduces an anti-abuse rule targeting related-party transactions structured to circumvent the FDDEI exclusion. Comments on this guidance are due by February 2, 2026, and taxpayers may rely on these rules until proposed regulations are issued, provided they apply them consistently and in their entirety.
The IRS also released its weekly list of written determinations (e.g., Private Letter Rulings, Technical Advice Memorandums, and Chief Counsel Advice).
Recent court opinion
November 25, 2025: The US Court of Federal Claims released its opinion in Kwong v. United States. Check out our recent insight on the case, which analyzes the Court’s holdings and provides key practice points for taxpayers.






Potential refund opportunity of buyback excise tax based on § 4501 final regulations
ARTICLE
Potential refund opportunity of buyback excise tax based on § 4501 final regulations
Dec 15, 2025
Read time: 4 min
Taxpayers who paid the stock repurchase excise tax based on prior guidance provided in Notice 2023-2 and the proposed regulations under Internal Revenue Code (IRC) § 4501 may be entitled to a refund based on changes made in the recently issued IRC § 4501 final regulations.
On November 21, 2025, the US Department of the Treasury (Treasury) and the Internal Revenue Service (IRS) issued final regulations under IRC § 4501, which took effect on November 24 and significantly narrowed the applicability of the stock repurchase excise tax compared to prior guidance provided in Notice 2023‑2 and the April 9, 2024, proposed regulations (collectively, the prior guidance). As a result, many transactions that were previously treated by the prior guidance as “repurchases” subject to the 1% stock repurchase excise tax are now no longer taxable. Taxpayers who paid the excise tax based on the prior guidance may be eligible for a refund.
The final regulations eliminated the prior guidance’s broad “funding rule,” which treated a US affiliate that was considered to have “funded” a foreign publicly traded parent (or its foreign affiliates), including via distributions or capital contributions, as having engaged in a covered stock repurchase. The final regulations also significantly narrowed the proposed regulations’ expansive treatment of transactions as “economically similar” to a stock repurchase by specifically excluding leveraged buyouts and other take-private transactions, complete liquidations, and tax-free acquisitive reorganizations under IRC § 368 from being subject to the excise tax. Moreover, the final regulations narrowed what qualifies as “stock” for IRC § 4501 purposes, specifically excluding certain preferred stock described in IRC § 1504(a)(4) (e.g., “plain vanilla” non-voting, non-participating preferred stock) and certain mandatorily redeemable or puttable stock issued before August 16, 2022 (i.e., the date of enactment of IRC § 4501).
The changes in the final regulations have potentially sweeping implications for taxpayers who paid the IRC § 4501 stock repurchase excise tax based on the prior guidance. The narrower scope of the applicability of stock repurchase excise tax under the final regulations creates a substantial opportunity to seek a refund of stock repurchase excise tax previously paid under the now-obsolete prior guidance.
To seek a refund, taxpayers should file Form 720-X, Amended Quarterly Federal Excise Tax Return, for each quarter they filed an original Form 720 reporting and paid the stock repurchase excise tax and attach a Form 7208 (with “Amended” at the top of each form) to each quarterly Form 720-X. Both Form 720-X and amended Form 7208 should be completed, and the excise tax recomputed, based on the final regulations. Because Form 720-X will serve as the taxpayer’s refund claim, it is critical that Form 720-X contains a detailed explanation of the legal basis for the adjustments to the original Forms 720 and 7208 to meet regulatory requirements imposed by the Treasury on refund claims. See Treas. Reg. § 301.6402-2 (setting forth the basic requirements for refund claims).
Taxpayers considering this refund opportunity should be aware that the statute of limitations deadline for filing a refund claim expires three years from the time the original Form 720 was filed or two years from the date on which payment was made – whichever is later (unless the statute of limitations period was otherwise extended).
Treasury issues transition guidance for taxpayers with one-month deferral elections
ARTICLE / CLIENT ALERT
Treasury issues transition guidance for taxpayers with one-month deferral elections
December 12, 2025
Read time: 5 min
The Internal Revenue Service (IRS) recently released Notice 2025-72 as a preview of forthcoming regulations addressing the repeal of the one-month deferral election under Section 898(c)(2) and modifications to the treatment of pretransition foreign currency gain or loss under Section 987 when taxpayers face short taxable years. These changes were made by the One Big Beautiful Bill Act (OBBBA) and have significant implications for controlled foreign corporations (CFCs), US shareholders, and multinational groups that rely on coordinated timing rules for foreign income tax and foreign currency purposes.
The one-month deferral election
Prior to the OBBBA, Section 898(c)(2) allowed certain foreign corporations to adopt a taxable year beginning one month earlier than the taxable year of their majority US shareholder. Many taxpayers made this one-month deferral election, which allowed them to delay the effect of certain changes in law by up to 11 months.
The OBBBA repealed this election, effective for taxable years beginning after November 30, 2025. For foreign corporations that previously made this election, repeal results in a mandatory one-month short taxable year to realign the foreign corporation’s tax year with that of its majority US shareholder. The US Department of the Treasury (Treasury) and the IRS recognize that this forced realignment may create distortions in how foreign income taxes are matched to US taxable income. Without guidance, a full year of foreign taxes could be treated as accruing in that one-month short taxable year, even though only one month of income is recognized for US federal income tax purposes. This could cause the foreign corporation to have a loss during that one-month short taxable year and prevent the taxpayer from getting any foreign tax credits.
In Notice 2025-72, the Treasury and the IRS provide guidance for taxpayers facing a one-month short taxable year. The notice describes forthcoming Section 898 regulations that will apply a structured framework for allocating foreign net income taxes that accrue in the short taxable year (specified foreign income taxes). The rules identify the foreign taxes subject to allocation, apply modified Section 1.861-20 principles to assign those taxes to relevant income groups, and allocate the taxes between the short taxable year and the succeeding full taxable year. The allocation percentage generally is based on the ratio of foreign law taxable income attributable to the short year versus the full foreign year.
The proposed framework also provides that taxes assigned to previously taxed earnings and profits (PTEP) groups will be fully allocated to the short taxable year and adjusts the allocation mechanics where Treas. Reg. Sec. 1.901-2(f)(5) “covered events” occur. While the amounts allocated to each period will be treated as accruing in those respective years for subpart F, global intangible low-taxed income, earnings and profits, and Section 960 deemed-paid credit purposes, all specified foreign income taxes will be treated as accruing in the short taxable year for purposes of Sections 905(c) and 986(a). This ensures that any later adjustments to those foreign tax liabilities relate back to the short year, avoiding additional complexity and preventing misalignment in foreign tax credit computations.
Section 987 transition rules
Notice 2025-72 also addresses how Section 987 transition rules should apply when taxpayers encounter short taxable years, including years shortened because of the repeal of Section 898(c)(2). Under the existing Section 987 regulations, taxpayers may elect to recognize pretransition foreign currency gain or loss ratably over a 10-year transition period. The Treasury and the IRS now intend to modify this rule so that pretransition gain or loss is recognized ratably over 120 months rather than a fixed number of taxable years. This change avoids distortions and preserves proportional recognition where a taxpayer’s first or subsequent taxable years are shorter than 12 months.
For taxpayers that have already recognized a ratable portion of pretransition gain or loss in a short year ending before November 25, 2025, that short year will be treated as containing a full 12 months solely for purposes of determining the remaining months in the amortization schedule. This rule ensures consistent treatment and prevents taxpayers from being penalized simply because the initial applicable year was compressed by statutory changes.
Reliance
Taxpayers may rely on the allocation rules and Section 987 modifications described in Notice 2025-72 for relevant taxable years until formal regulations are issued, provided the rules are applied consistently. The Treasury and the IRS also request comments on whether the allocation regime should be extended to other categories of foreign taxes (such as partnership-level taxes that may be indirectly affected by year-end conformity) and whether additional multiyear rules warrant similar adjustments in light of short taxable years created by the OBBBA.
Conclusion
Notice 2025-72 provides essential transitional guidance for multinational groups facing timing mismatches in foreign tax and foreign currency regimes as a result of the repeal of the one-month deferral election. CFCs and their US shareholders should begin modeling the potential impact on foreign tax credit capacity, high-tax exception and high-tax exclusion calculations, Section 960 deemed-paid credits, earnings and profits, and the timing of Section 987 gain and loss. Taxpayers must revisit tax-year alignment decisions, evaluate systems for tracking foreign-law taxable income across short periods, and consider whether comments should be submitted to the Treasury to address administrative hurdles or unintended consequences.
Key takeaways | AI Governance and Security Assessment Workshop
ARTICLE
Key takeaways | AI Governance and Security Assessment Workshop
December 12, 2025
Read time: 4 min
During the AI Governance and Security Assessment Workshop, Shawn Helms and Jason Krieser of McDermott Will & Schulte and Patrick Murphy of Palo Alto Networks Unit 42, discussed ways to govern the use of generative artificial intelligence (AI) and how to address security risks associated with AI in a fast-paced environment.
Key takeaways from the program included:
- AI is becoming ubiquitous. AI is rapidly permeating all facets of business operations. We are approaching an environment in which the “oddball” case will be the absence of AI rather than its presence. Organizations must proactively plan for and guide AI adoption instead of attempting to block it. This includes implementing safe and responsible deployment practices and developing a clear understanding of each tool’s risk profile. Thoughtful governance at the outset will help facilitate adoption and utilize AI tools.
- Fragmented legal landscape in the US. There is no comprehensive federal framework that provides unified guidance or regulatory oversight for AI in the United States. Common themes emerging across state legislatures include transparency obligations, consumer and employee protection requirements, data privacy safeguards, bias mitigation mandates, and restrictions on deepfakes. States appear to be diverging in their approaches. For example, Texas is taking a business friendly approach, whereas Colorado imposes heavier burdens (especially for high risk systems) while offering an affirmative defense tied to risk mitigation frameworks. This divergence will affect the overall compliance approach of organizations, particularly those that operate across multiple states or globally.
- Zero trust foundation. Human oversight should be integrated into every AI-driven action, and outputs generated by AI tools must undergo appropriate human review. Recent incidents have demonstrated that AI can be used to create or amplify security vulnerabilities that adversaries might not have been able to exploit without AI-powered capabilities. The introduction of AI into the threat landscape has also accelerated the pace of attacks and compressed incident-response timelines, which increases the pressure on organizations to evaluate, strengthen, and routinely stress-test their security infrastructure with AI-related risks in mind.
- Autonomous AI attacks. The threat landscape now includes autonomous or semi-autonomous AI-assisted cyber operations that are highly scalable, adaptable, and difficult to attribute. Adversaries are now leveraging LLMs, agents, and model context protocols to automate data exfiltration, and perform post exfiltration analysis. As a result, organizations must prepare for attackers executing faster, more persistent, and more sophisticated attack campaigns, and must modernize their defense systems accordingly.
- AI governance programs. Organizations of all sizes should prioritize the development of durable, comprehensive AI governance programs. A key component of this effort is to establish cross-functional governance committees to steer AI adoption in a safe direction. Other efforts include overseeing AI adoption, establishing and updating AI policies, conducting enterprise-wide AI inventories (including identifying shadow AI), and monitoring legal and regulatory developments. The National Institute of Standards and Technology (NIST) has published a NIST AI Risk Management Framework, which helps organizations reduce AI risk, automate AI risk management, and continuously monitor AI risks.