ARTICLE
Latest tax updates: AI-generated citations warning, Section 951A deduction allocation, and holding-period limits
October 1, 2026
Read time: 4 min
In this edition of IRS Roundup, we cover proposed rules from the Internal Revenue Service (IRS) and the US Department of the Treasury that address the allocation of deductions to foreign-source § 951A category income, and how the IRS granted relief from a defective consolidated-return consent. We also discuss recent US Tax Court decisions concerning the § 245A dividends-received deduction, collection due process proceedings, artificial intelligence (AI)-assisted briefing, and penalty-notice requirements.
September 11, 2026: Treasury and the IRS published proposed regulations implementing recent statutory changes to the allocation and apportionment of deductions for purposes of calculating foreign-derived deduction eligible income and the foreign tax credit limitation for foreign-source § 951A category income.
For § 951A purposes, interest expense and research and experimental expenditures would not reduce foreign-source § 951A category income, while other deductions generally would reduce that income only if they are “directly allocable.” Deductions that otherwise would have been allocated to the § 951A category but do not satisfy the proposed rules generally would be reallocated to US-source income. Because that reallocation may create or increase a domestic loss, taxpayers should consider the potential multiyear consequences in addition to the immediate foreign tax credit benefit. The proposed rules generally would apply to taxable years beginning after December 31, 2025, and comments are due November 10, 2026.
September 11, 2026: In written determination 202637011, the IRS treated a subsidiary as having consented to join its parent’s consolidated return even though the parent failed to attach Forms 1122 and 851 or check the consolidated-return box.
Applying the facts-and-circumstances rule under Treasury Regulation § 1.1502-75(b)(2), the IRS emphasized that the parent included all of the subsidiary’s income, gain, deductions, and losses on its return and that the subsidiary did not file a separate return. The IRS therefore treated the subsidiary as if it had timely filed Form 1122. The determination is nonprecedential but illustrates the facts that may support relief from a defective consolidated-return consent.
Recent court decisions
September 14, 2026: In Sysco Corporation v. Commissioner, T.C. Memo. 2026-84, the Tax Court followed its prior decisions in Varian Medical Systems, Inc. v. Commissioner and rejected the taxpayer’s additional arguments concerning the § 245A dividends-received deduction.
The Court held that § 246(c)(1) limits the § 245A deduction to dividends attributable to shares directly held by the taxpayer. Indirect ownership sufficient to establish US shareholder status therefore did not satisfy the applicable holding-period requirement. The Court also held that, when calculating the foreign tax credit disallowance under § 245A(d)(1), the taxpayer’s net § 965 inclusion in the denominator must reflect the related § 965(c) deduction.
September 15, 2026: In Moore v. Commissioner, T.C. Memo. 2026-85, the Tax Court sustained the IRS’s filing of a Notice of Federal Tax Lien. The taxpayer’s statement during the collection due process proceeding that he was unsure whether the IRS’s balances were correct – without specific allegations or supporting evidence – was insufficient to place the underlying liabilities properly at issue. The Court therefore reviewed the IRS’s determination only for abuse of discretion.
The Court also observed that the taxpayer’s opening brief appeared to have been prepared with AI and contained citations to nonexistent pages and decisions that did not support the stated propositions. The Court emphasized that its rules do not prohibit the use of AI tools but that parties remain responsible for verifying all authorities and information submitted to the Court.
September 16, 2026: In Groves v. Commissioner, T.C. Memo. 2026-86, the Tax Court denied a taxpayer’s motion for summary judgment in a collection case involving a § 6707 tax-shelter penalty.
The taxpayer argued that the assessment was invalid because the IRS’s Form CP15 did not include a computation of the reduced penalty as required by § 6751(a). The Court held that the omission was a procedural error that did not invalidate the assessment absent prejudice. The taxpayer previously had received the original computation, and the IRS had explained the reduced amount during an IRS Appeals conference. Because the taxpayer understood how the penalty was calculated and did not establish prejudice, the Court denied his motion. The underlying collection case remains pending for trial.




Texas comptroller moves to end tax on marketplace fees
ARTICLE
Texas comptroller moves to end tax on marketplace fees
Sep 30, 2026
Read time: 3 min
On September 30, 2026, Texas Comptroller Don Huffines announced that he signed an executive order directing the comptroller’s office to propose an amendment to Rule 3.330 that would remove marketplace and platform fees from the definition of “data processing services” subject to sales and use tax.
The move represents a significant reversal of the comptroller’s prior approach to marketplace fees. As we discussed in prior Inside SALT posts in 2023 and 2024, the comptroller took the position that commissions charged by marketplace providers could themselves constitute taxable data processing services, even where sales tax was separately collected on the underlying marketplace transaction. The practical result could be tax on as much as 130% of a marketplace sale: tax on 100% of the underlying sale and a second tax on the portion of the proceeds retained by the marketplace provider as its commission.
The comptroller subsequently amended Rule 3.330 in 2025 to formalize that position, providing that marketplace provider services may constitute taxable data processing services when they involve activities such as the computerized entry, retrieval, search, compilation, manipulation, or storage of data or information.
Comptroller Huffines is now directing the agency to reverse course. In announcing the executive order, he criticized the prior interpretation, stating that the agency had “cast a huge net” and adding, “That’s not tax policy. That’s tax invention. A Comptroller doesn’t get to invent new taxes by rulemaking any more than a judge gets to invent new crimes that aren’t on the books.”
The proposed change would take a substantially narrower approach to the taxation of marketplace services and eliminate the additional tax on marketplace fees that resulted from the prior interpretation. According to the comptroller’s announcement, the amendment would remove marketplace and platform fees associated with online retail marketplaces, prepared food and grocery delivery, short-term lodging, ride-hailing and other transportation services, vehicle rental or sharing, pet care, and household and personal services from the definition of taxable data processing services.
The announcement also signals that the new comptroller intends to take a fresh look at the broader sales and use tax treatment of data processing services in Texas. Comptroller Huffines stated that his office will continue reviewing how the tax is interpreted and may propose additional changes in the future. For taxpayers navigating a statute enacted for a very different technological era, a clearer delineation of what constitutes taxable data processing would be a welcome development.
The executive order does not amend Rule 3.330. The comptroller will file a proposed amendment with the Texas secretary of state for publication in the Texas Register, after which the proposal will be subject to a 30-day public comment period.
Companies that previously conceded or otherwise accepted the comptroller’s prior treatment of marketplace fees in an audit or other proceeding should contact the authors to discuss potential next steps, including whether any refund or other procedural avenues may be available.




PE investment in law firms: 6 considerations as MSO market enters next phase
ARTICLE
PE investment in law firms: 6 considerations as MSO market enters next phase
September 29, 2026
Read time: 13 min
Key takeaways
Private equity is expanding into law firms, and regulators have noticed.
Through management services organizations (MSOs), outside capital can invest in a law firm’s business operations while preserving lawyer ownership. In response, regulators are establishing clearer boundaries around outside investments in law firms. Here are six issues every sponsor should weigh before entering a law firm MSO deal.
Private equity’s (PE) expansion into professional services is reaching one of the few sectors that, historically, has remained largely outside the institutional investment model: law firms. This has quickly attracted the attention of lawmakers and regulators. While such attention does not spell the end of these types of investments, it signifies that things are already changing.
PE sponsors, law firms, and financing sources are increasingly evaluating management services organizations (MSOs) that allow outside capital to invest in firms’ business operations, enabling the MSO to support a law practice while preserving lawyer ownership and control of legal services and counsel. Early transactions in this space were concentrated primarily among personal injury firms. However, there has been an increasing number of MSO transactions in a wide variety of other types of law firms.
Legislators and regulators are taking note. Following related regulatory developments in Colorado and Illinois, California recently passed legislation addressing the potential influence of outside investors on litigation decisions. While the details of these initiatives vary by jurisdiction, the developing framework reflects several recurring principles: Investors should not control or influence lawyers’ professional judgment, lawyers must continue to protect confidential client information, and the economics between an MSO and a law firm must be structured to avoid impermissible fee sharing.
As transaction activity grows, the relevant questions for sponsors are shifting from whether an MSO can be created and toward the identification of structures that can withstand regulatory scrutiny, obtain financing, support growth, and ultimately deliver the economics contemplated at underwriting.
For sponsors evaluating the legal sector, consider these six issues from the outset.
Structural separation must be more than a diagram
The basic concept underlying a law firm MSO is relatively straightforward: A law firm performs two broad categories of functions, including the practice of law and the nonlegal business operations that support that practice. Under a typical MSO structure, the law firm continues to perform the legal functions while certain nonlegal functions, such as marketing, human resources, information technology, and other administrative services, are transferred to or performed by a separate MSO. Certain nonlegal assets, employees, and intellectual property (IP) also may reside at the MSO.
The two organizations are then connected contractually. The MSO generally provides services to the law firm pursuant to a management services agreement and may license IP to the firm under a separate licensing arrangement. Investors can acquire a minority or majority interest in the MSO while the law firm remains separately owned and controlled by lawyers.
The critical principle is that legal functions remain with the law firm. Lawyers must remain free to exercise independent professional judgment and represent their clients in accordance with applicable professional obligations.
This architecture will be familiar to healthcare investors. For decades, MSOs have been used to separate professional healthcare services from nonclinical business operations in jurisdictions restricting nonprofessional ownership of medical practices.
While this structural principle generally translates from healthcare delivery to legal practice, the regulatory framework does not. Legal MSOs must operate in compliance with professional-conduct rules specific to lawyers, and those rules must drive the structure of agreements from the outset, rather than being layered after the fact onto a pre-fab healthcare model. It is possible to separate professional services and judgment from nonprofessional operations, in large part because the architecture of such arrangements complies with the relevant regulatory regime. For sponsors of such transactions, the objective is to create an investable business services enterprise alongside a genuinely independent professional practice.
MSO economics are a central regulatory and underwriting issue
Given the requirements, the economic relationship between the law firm and the MSO is a key point of focus. In almost every state, professional-conduct rules restrict lawyers from sharing legal fees with nonlawyers. Because legal fees generally are the principal source of law firm revenue, the MSO will be paid from cash generated by the professional practice. The challenge is to design compensation for legitimate services and assets without creating an arrangement that could be characterized as impermissible fee sharing.
Depending on the applicable law and particular facts, potential approaches may include fixed fees, cost-plus arrangements, per-lawyer fees, consulting fees, and IP licensing fees supported by an appropriate valuation analysis. Earlier approaches that tied MSO compensation directly to a percentage of law firm revenue or profits present more significant concerns.
It is important to note that these analyses don’t end once the deal has closed. For example, a law firm that expands, post-transaction, through lateral hiring, geographic growth, or acquisitions may consume substantially more MSO resources and derive additional value from MSO-owned assets. The contractual framework therefore should be sufficiently flexible to enable the economics to evolve with the business. Potential mechanisms can include periodic fee reviews, updated IP valuations, and fee methodologies that scale with lawyer headcount or other measures of firm growth. Ultimately, the investment’s durability will significantly depend on the durability and defensibility of the financial relationship between the professional practice and the MSO.
Governance and lawyer retention require a different PE playbook
PE investors typically expect meaningful governance and contractual protections with respect to their investments. For law firm MSOs, such protections must be considered through a unique lens.
For example, in addition to the fundamental regulatory principle that an MSO investor cannot improperly control or influence the practice of law, lawyers also must preserve client confidentiality. As a result, governance rights that might be routine in another portfolio company typically require closer consideration in a law firm MSO. Investor protections should be designed to protect the MSO investment without migrating into decisions reserved for lawyers and the professional practice.
Lawyer retention creates another distinctive challenge. Traditional PE investments frequently rely on restrictive covenants to protect enterprise value. The professional rules applicable to lawyers significantly constrain that tool. The American Bar Association Model Rule 5.6, for example, generally restricts agreements that limit a lawyer’s right to practice, making conventional noncompetition protections particularly challenging in the law firm context. This rule increases the importance of economic alignment and thoughtful incentive design; depending on the structure and applicable requirements, potential mechanisms to address these industry-standard restrictions may include MSO equity vesting or forfeiture, deferred consideration, and clawback arrangements.
From an underwriting perspective, law firms also can have substantial key-person and concentration risk. When underwriting law firm MSOs, financing sources should be prepared to examine lawyer retention, partner economic incentives, and revenue concentration by partner, among other factors. Sponsors also should consider, early in the investment process, how the structure will keep key lawyers aligned with the platform when conventional restrictive covenants may not provide the protections available in other industries.
Financing is developing into its own law firm MSO workstream
The emergence of a more sophisticated financing market may be one of the strongest indications that law firm MSOs are beginning to mature as an investment category. Historically, law firm lending was concentrated among a relatively small group of sector specialists. More recently, a developing cohort of direct lenders has emerged that can underwrite law firm MSO transactions at pricing in line with, or at a modest premium to, other sectors.
That said, financing a law firm MSO involves much more than applying conventional leveraged buyout financing to a new industry. Lenders must take into account a recurring set of sector-specific issues, including lawyer retention and key-person exposure; case generation and barriers to entry; contingency versus hourly revenue and revenue visibility; collections and receivables; regulatory put mechanics; the durability of the MSO structure; transaction ethics; and concentrations by partner, case, referral source, geography, and practice area.
Law firm MSO transaction documentation can also involve concepts unfamiliar to lenders entering the sector for the first time. An effective financing structure will address the issues noted above, as well as business services agreements, nonlegal asset transfer agreements, licensing arrangements, continuity agreements, and indemnification arrangements.
Ultimately, financing considerations should inform transaction architecture from the beginning rather than being addressed after the MSO structure is complete. A transaction that satisfies the sponsor and law firm but cannot support the contemplated financing may fail to deliver the capital structure assumed in the investment thesis.
The structure should be designed for the second transaction, not just the first
The initial transaction is only one stage in the life cycle of a PE investment. As noted above, a sponsor may expect to expand the platform through lateral hiring, additional offices, new partnerships, or acquisitions. Other strategies include investing in technology and marketing; increasing MSO earnings before interest, taxes, depreciation, and amortization; refinancing the business; and, ultimately, pursuing an exit option that may involve selling its investment. Each of these initiatives can place additional pressure on the original structure.
Further, multistate expansion requires analysis of jurisdiction-specific professional rules. Growth may require adjustments to management fees and licensing arrangements. Add-on transactions can introduce new-partner economics and governance considerations. Financing sources may require additional structural protections. And a successful exit typically requires creating an MSO structure that remains workable under new ownership.
Despite some fundamental differences, the healthcare MSO market provides useful lessons with respect to such life cycle issues. While law firm MSOs involve a different regulatory framework, many of the transaction pressure points are recognizable: Management fee mechanics, governance alignment, multistate expansion, and exit risk need to be considered when the platform is formed and through add-ons, financing, and an eventual exit. A structure designed only to complete the initial transaction is likely to be substantially less valuable than one designed to support the sponsor’s full investment thesis.
Regulation may be defining the market, but it is not closing it
California is just the latest example of how increased transaction activity in the legal sector has brought increased legislative and regulatory attention. There, the state legislature recently passed legislation aimed at preventing outside investors from controlling or improperly influencing litigation decisions, including decisions regarding client selection, representation terms, settlement, and legal strategy. The legislation follows developments in Colorado and Illinois also addressing PE investment and law firm MSOs.
These developments should be taken seriously. They are likely to affect transaction structures, economic arrangements, and documentation and compliance obligations. Sponsors pursuing multistate strategies will need to account for differences among jurisdictions. However, these developments also point toward a maturing market.
The recurring regulatory themes (professional independence, client confidentiality, and separation between investor economics and legal fees) are largely focused on the boundary between legitimate investment in the business infrastructure surrounding a law firm and impermissible investor participation in the practice of law. This is a natural evolution: As investment grows, scrutiny will grow with it. The structures most likely to endure will be those designed from inception around genuine professional independence, defensible economics, and meaningful separation between the investor-owned MSO and lawyer-controlled practice.
PE sponsors are evaluating opportunities. Law firms beyond the first wave of personal injury practices are considering the model. Financing sources are developing sector-specific underwriting frameworks. And legislators and regulators are beginning to establish more explicit boundaries around outside investment.
All of this has led to increased scrutiny. Investors and law firms must now make decisions and build structures designed for that scrutiny. Within these structures, professional independence should be genuine; economics should be defensible; key lawyers should remain aligned; financing considerations must be addressed from the outset, and transaction architecture should be prepared to accommodate growth, multistate expansion, and an eventual exit.
While other sectors provide a useful precedent and law firm MSOs involve a different rule set, the larger lessons carry over: The most durable structures are not those designed to get around professional regulation. They are those designed to work within it.
McDermott was an early leader in developing the MSO structure. Contact the authors or your McDermott lawyer to learn more about how we can draw on our experience with law firm MSOs and healthcare private equity to help drive your success.



Where MedTech is attracting PE attention with less FDA burden
ARTICLE
Where MedTech is attracting PE attention with less FDA burden
September 25, 2026
Read time: 11 min
MedTech investment trends: Part 2 (Read Part 1, “Where private equity is finding value in MedTech.”)
PE is getting into component manufacturing and device servicing opportunities, where US Food and Drug Administration (FDA) distinctions are creating a compelling case for MedTech investment – if those regulatory advantages hold post-close.
Not every MedTech business carries the same regulatory obligations. Two MedTech companies can serve the same customers and markets but face very different levels of FDA scrutiny depending on their role in the medical device supply chain – a distinction that is creating attractive opportunities for private equity.
Component manufacturers and companies that service or refurbish medical devices are emerging as particularly appealing targets. They benefit from demand across the MedTech market without necessarily facing the same direct FDA requirements as finished-device manufacturers or remanufacturers. For sponsors, that combination can offer a compelling way to capture MedTech growth with less regulatory complexity.
The key for investors is understanding where those regulatory distinctions apply and how they can affect the investment over time.
What’s happening
Medical device companies can rely on outside suppliers for everything from basic parts to highly specialized technology. When those suppliers manufacture components that on their own cannot function as finished devices, they generally sit outside of direct FDA regulation. On the other hand, a contract manufacturer that provides a finished device based on another company’s specifications must register with the FDA and is subject to FDA regulation including inspections, among other things.
Component manufacturers can operate more like traditional industrial businesses, with heightened quality focus, while supplying a highly regulated industry. Specialized components used in high-value medical devices can also command premium pricing.
Why it matters for PE firms
The regulatory distinction depends in part on whether the manufactured product is itself a finished device. A supplier that provides components – even according to specifications set by the finished-device manufacturer – is in a different position than one that produces a finished device according to manufacturer specifications or controls design, tolerances, software, or other features affecting the device’s safety or performance.
That makes scope creep an important diligence issue. Sponsors should understand who controls key decisions, how customer agreements divide responsibilities, and whether the supplier’s product is independently regulated by the FDA. Further, a component manufacturer that has gradually taken on more responsibility from its customers under their supply agreements may carry regulatory obligations that are not obvious from its business model or financials. Finally, indemnification and insurance coverage with customers should be carefully monitored.
The proof is in the deals
PE investment is already following this opportunity. Sponsors are targeting specialized suppliers with established original equipment manufacturer (OEM) relationships, differentiated manufacturing capabilities, and opportunities to build scale through acquisition.
- KKR agreed to acquire Integer Holdings, a major supplier of components and finished products to medical device companies, in a $5.7 billion take-private.
- MCM Capital Partners acquired Octex, a manufacturer of highly engineered thermoplastic components for medical device and life sciences customers.
- Montagu and Kohlberg’s $1.5 billion acquisition of Teleflex Medical OEM, a global leader in custom-engineered solutions for extrusions, tubing, catheters, balloons, sutures, and more.
- Avista’s acquisition of Bentec Medical, a manufacturer of complex silicone components and finished goods for medical device OEMs.
The activity underscores growing sponsor interest in the businesses behind finished medical devices – particularly where specialized capabilities and opportunities for consolidation can support a broader MedTech investment thesis.
Component manufacturing is not the only area where regulatory classification can shape investment decisions. The same principle is at work in the medical device servicing and refurbishment market.
What’s happening
The FDA draws a distinction between servicing a medical device and remanufacturing it. Under the agency’s May 2024 Remanufacturing of Medical Devices guidance, servicing generally returns a device to the safety and performance specifications established by the OEM without changing its intended use. Remanufacturing, however, involves activities that significantly change a finished device’s performance, safety specifications, or intended use.
Why it matters for PE firms
The FDA states that an entity solely performing servicing activities is not required to register and list with the agency and is not subject to most manufacturing-related requirements. Remanufacturers, by contrast, are subject to applicable device requirements, including registration and listing, adverse-event reporting, the Quality Management System Regulation (QMSR), and premarket submissions, where applicable.
Preserving that distinction depends on the exact work being performed. The FDA focuses on activities, not how a company describes its business, so sponsors should independently test a target’s classification against the FDA’s framework. Using substitute, more cost-effective components does not necessarily trigger FDA regulation, whereas making software or specification changes, even if inadvertent, can push servicing toward remanufacturing and bring additional FDA requirements. This highlights the importance of upstream vendor qualification, proper release testing, and identification of appropriate safety and performance standards against which the serviced products are to be evaluated.
Regulatory classification is not the only consideration for independent servicers. Their ability to operate and grow can also depend on relationships with OEMs. Restrictions on proprietary parts, software, or technical information can limit which devices a third party can service, making these dependencies important to the investment case.
The proof is in the deals
PE interest is also extending into device servicing. Recent investments reflect the opportunity sponsors see in businesses that repair, maintain, and refurbish medical equipment.
- Healthcare-focused private investment firm BPOC invested in both Master Medical Equipment and ReNew Biomedical, which provide equipment distribution, refurbishment, rental, repair, and preventive maintenance services.
- NMS Capital-backed Surplus Solutions acquired Boston Industries, expanding its technical repair and refurbishment capabilities for laboratory instruments.
- Frazier Healthcare-backed DirectMed acquired Tri-Imaging Solutions to create a scaled aftermarket diagnostic imaging platform spanning parts, systems, repair, and service.
The activity highlights a fragmented market where recurring demand for critical equipment servicing can support platform growth through expanded technical capabilities, geographic reach, and customer relationships.
Sponsors must consider how a company’s growth plans could change its FDA requirements and the economics of the investment. The question for them is not whether to avoid growth that brings additional regulation, but whether the opportunity justifies the regulatory investment needed to support it.
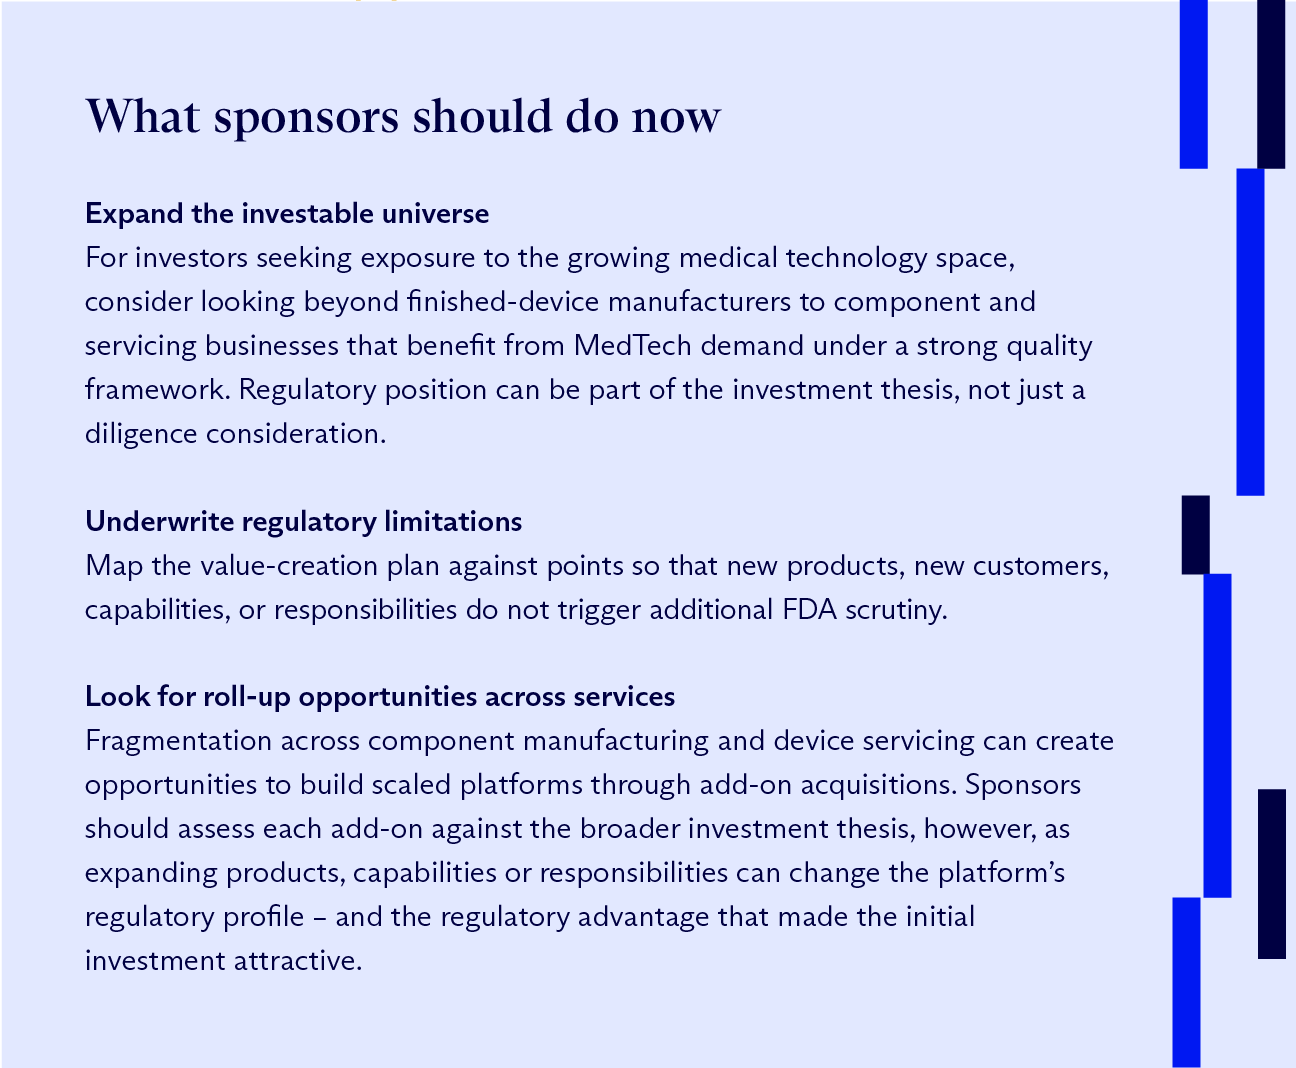
For private equity investors, component manufacturing and device servicing can offer a distinct path to identifying investments in the MedTech industry without the regulatory exposure of device manufacturers and OEMs – but sponsors should diligence scope creep and underlying contractual obligations closely.
To learn more about these trends and their implications for MedTech investors, contact the authors or your McDermott lawyer. We will also be discussing these developments and more at our upcoming Healthcare Private Equity NYC and Life Sciences Investment Forum.


Federal Circuit: Unjust enrichment available as damages theory for trade secret misappropriation
ARTICLE
Federal Circuit: Unjust enrichment available as damages theory for trade secret misappropriation
Sep 24, 2026
Read time: 6 min
The US Court of Appeals for the Federal Circuit vacated a judgment limiting a trade secret plaintiff to a reasonable royalty based on the parties’ licensing history, finding that unjust-enrichment damages are available under the Defend Trade Secrets Act (DTSA) and Michigan Uniform Trade Secrets Act (MUTSA). The Court rejected the defendant’s argument that liability for misappropriating a combination trade secret requires proof that the defendant knew each specific element comprising the combination. Versata Software, LLC v. Ford Motor Co., Case Nos. 24-1140; -1206; -1234 (Fed. Cir. Sept. 10, 2026).
Ford licensed Versata’s Automotive Configuration Manager (ACM) software, which helped Ford configure vehicles for manufacturing. When the parties were unable to agree on an extension of their licensing agreement, Ford released its own configuration software, PDO, which it had developed while still licensing Versata’s software. Versata asserted claims for breach of contract and trade secret misappropriation under the DTSA and the MUTSA. Versata alleged that Ford misappropriated three interdependent “combination” trade secrets within ACM: Grid, Buildability, and Workspaces.
Before trial, the district court excluded Versata’s damages expert’s proposed unjust-enrichment analysis, concluding that Versata’s trade secret damages had to be measured by reference to the parties’ licensing history. The court permitted Versata to submit revised reasonable-royalty models but excluded two models because they incorporated the value Ford obtained from using the trade secrets rather than relying solely on the parties’ licensing history.
A jury later found that Ford misappropriated all three ACM trade secrets and breached the parties’ agreement. It awarded Versata approximately $22 million for trade secret misappropriation and $82 million for breach of contract. The district court subsequently reduced the trade secret award to zero and the contract award to $3 million. Versata appealed, and Ford cross-appealed the finding of trade secret liability.
Unjust-enrichment damages
Versata argued that the district court improperly prevented it from seeking unjust-enrichment damages and instead required its damages to be based on the parties’ licensing history. The Federal Circuit agreed.
Applying Sixth Circuit law, the Federal Circuit explained that the plain language of both the DTSA and the MUTSA expressly permits a plaintiff to recover unjust enrichment caused by trade secret misappropriation to the extent that enrichment is not accounted for in calculating actual loss. The statutes separately permit a reasonable royalty “in lieu of” damages measured by other methods. The Court found that Versata was entitled, as a matter of law, to pursue unjust-enrichment damages.
The Federal Circuit rejected the district court’s conclusion that the parties’ licensing history required Versata’s damages to be measured by a reasonable royalty. Although prior Sixth Circuit decisions had upheld royalty-based awards derived from licensing history, those cases did not establish that a plaintiff was prohibited from pursuing unjust enrichment.
Nor was unjust enrichment available only where damages could not otherwise be measured. The Federal Circuit emphasized that the statutory language expressly allows a plaintiff to pursue unjust-enrichment damages. Because the district court’s contrary ruling affected Versata’s damages case throughout the litigation, the Federal Circuit vacated the judgment awarding zero trade secret damages and remanded for a new damages trial. It also instructed the district court to reconsider Versata’s previously excluded reasonable-royalty models that incorporated the value Ford obtained from using the trade secrets.
The $82 million contract award
The Federal Circuit separately reversed the district court’s reduction of Versata’s $82 million breach-of-contract award to $3 million.
At trial, Versata presented the jury with three annual damages figures derived from the parties’ licensing history: $17 million, $14 million, and $10 million. Versata asked the jury to multiply the appropriate figure by seven and a half years, representing the period of Ford’s breach through trial. The jury’s $82 million award equated to approximately $11 million per year – nearly identical to the lowest annual figure presented by Versata.
The Federal Circuit determined that the jury had a sufficient evidentiary basis to calculate damages with reasonable certainty. Versata’s expert distinguished the $11 million base license fee from the higher fee that included support and maintenance services, the underlying agreements were admitted into evidence, and even Ford’s damages expert acknowledged that $11 million was a more reasonable starting point because it excluded fees for additional services. The Court concluded that this evidence gave the jury a “discernible path” to calculate damages and reinstated the full $82 million award.
Knowledge of combination trade secrets
The Federal Circuit rejected Ford’s argument that Versata was required to prove Ford knew the specific elements that comprised each asserted combination trade secret. The Court explained that neither the DTSA nor the MUTSA imposes such a heightened knowledge requirement. Although a combination of otherwise known elements may qualify for trade secret protection, the statutes do not require proof that a defendant knew the precise combination or each individual element comprising it. Instead, the statutory inquiry focuses on whether the defendant acquired the trade secret through improper means or used or disclosed it while knowing or having reason to know that its knowledge was obtained under circumstances imposing a duty of secrecy or restricted use.
Versata also presented sufficient evidence of disclosure. Its technical expert testified that Versata disclosed the combination trade secrets to Ford through user guides and presentations, and a former Versata employee testified that the information was disclosed through manuals, technical documents, emails, onsite discussions, and the software itself. The Federal Circuit affirmed the denial of Ford’s motion for judgment as a matter of law on trade secret liability.
Practice note: A prior licensing relationship does not necessarily confine a trade secret plaintiff to royalty-based damages. The DTSA expressly permits recovery of unjust enrichment not accounted for as actual loss, allowing plaintiffs to pursue damages tied to the value or benefits obtained through misappropriation where supported by the evidence. The decision also provides useful guidance for combination trade secrets: a plaintiff need not prove that the defendant specifically recognized each element of the asserted combination as comprising a trade secret.




Trending in Telehealth: August 2026
ARTICLE
Trending in Telehealth: August 2026 recap
Sep 23, 2026
Read time: 8 min
Trending in Telehealth highlights monthly state legislative and regulatory developments that impact healthcare providers, telehealth and digital health companies, pharmacists, and technology companies that deliver and facilitate the delivery of virtual care.
Trending in August:
- Telehealth access expansion
- Coverage and reimbursement developments
- Multistate licensure compacts
- Remote patient monitoring coverage
A closer look
Proposed legislation and rulemaking
- California lawmakers are considering AB 2551. The bill would require health plans and insurers to analyze and report on out-of-network behavioral health utilization and spending. The proposal would require carriers to assess whether patients are seeking out-of-network care because of insufficient access to in-network behavioral health services, including telehealth behavioral healthcare. The reporting requirement is intended to provide greater visibility into behavioral health network adequacy and access barriers.
- California’s AB 2540 would require community colleges with student health centers to provide access to medication abortion services and would expressly permit those services to be delivered via telehealth. The proposal reflects continued efforts to expand access to reproductive healthcare services through virtual care modalities and campus-based health programs.
- California is also considering AB 1930, which would expand protections for individuals and entities involved in abortion-related and gender-affirming care. The proposal would extend existing protections against certain out-of-state investigations and enforcement actions to encompass healthcare services delivered via telehealth.
- AB 375 is awaiting the California governor’s signature and would expand the types of healthcare professionals authorized to provide services through telehealth. The bill would add qualified autism service paraprofessionals to the Medical Practice Act’s definition of “health care provider,” allowing them to furnish certain services using telehealth technologies consistent with applicable supervision and practice requirements and medical practice act telehealth provisions.
- California lawmakers are also advancing AB 1999. The bill would revise the state’s veterinary telemedicine framework. The proposal would modify the rules governing how veterinarian-client-patient relationships may be established and maintained remotely, establish continuity-of-care requirements for veterinarians providing follow-up telemedicine services, and permit certain teleconsultation activities by individuals assisting California-licensed veterinarians.
Finalized legislation and rulemaking
- Illinois enacted SB 3211, which expands access to teledentistry by allowing most initial examinations for new patients to be conducted remotely. The law removes certain barriers to virtual dental care while preserving an in-person examination requirement for patients seeking orthodontic treatment.
- Illinois also enacted SB 3213 modernizing prescription-transfer and electronic prescribing requirements. The law authorizes electronic and facsimile prescription transfers and extends certain exemptions from controlled-substance electronic prescribing requirements through 2028, providing additional flexibility for pharmacies and prescribers as electronic prescribing standards continue to evolve.
- By enacting S4407, New Jersey extended its temporary involuntary commitment procedures and flexibilities for telemedicine in certain behavioral health evaluations. The new law allows psychiatric examinations required for extended involuntary commitment proceedings to be conducted via telemedicine or telehealth, provided the applicable standard of care is satisfied.
- The District of Columbia enacted DC Law 26-356 expanding coverage for remote patient monitoring services during and after pregnancy. The law requires coverage and reimbursement for remote monitoring of blood pressure and blood glucose levels during pregnancy and up to 12 months postpartum, reflecting continued efforts to use telehealth technologies to improve maternal health outcomes.
Compact activity
- New Jersey enacted S 4113, adopting the Athletic Trainer Compact and allowing licensed athletic trainers to practice across participating states, including through telehealth services.
- Michigan adopted the Physician Assistant Licensure Compact, Occupational Therapy Licensure Compact, and Physical Therapy Licensure Compact, enabling qualifying practitioners to provide services across participating states without obtaining a separate full license in each jurisdiction.
Why it matters
- States continue to expand telehealth beyond traditional healthcare settings and provider types. Recent legislative activity affecting veterinary telemedicine, teledentistry, autism services, reproductive healthcare, and behavioral health reflects a broader trend toward integrating virtual care across a wider range of services. As states broaden who can provide care remotely and the circumstances under which telehealth may be used, providers and technology companies should closely monitor scope-of-practice, supervision, and continuity-of-care requirements that often accompany these expansions.
- Interstate practice opportunities continue to grow through licensure compacts. Michigan and New Jersey’s adoption of additional professional licensure compacts reflects continued momentum toward greater provider mobility and expanded access to care across state lines. While these frameworks can reduce administrative barriers to multistate practice, organizations should remain attentive to compact eligibility requirements, state-specific practice rules, and telehealth-related registration or reporting obligations.
Telehealth continues to transform care delivery, but the regulatory landscape remains highly fragmented. The McDermott Will & Schulte digital health team works alongside leading providers, payors, and technology innovators to help navigate evolving telehealth requirements, expand into new markets, structure innovative care models, and manage regulatory and enforcement risk through proactive compliance strategies.



How to rethink physician alignment without breaking the bank
ARTICLE
How to rethink physician alignment without breaking the bank
September 21, 2026
Read time: 10 min
Hospitals and health systems are confronting financial pressure from multiple directions: Medicaid funding cuts, 340B reimbursement uncertainty, the continued shift toward site-neutral payments, and the potential loss of enhanced ACA subsidies.
Against that backdrop, physician alignment deserves a place at the top of the fiscal agenda. It is a low-cost lever for improving financial and operational performance – and better still, there have been meaningful healthcare regulatory developments related to the physician self-referral law (commonly known as the Stark Law) and Anti-Kickback Statute (AKS) that have been underutilized since their inception1 that allow for novel strategies.
As new government policies and proposed changes erode health system reimbursement, it’s time for health systems to take a fresh look at long-term margin strategy. Your organization may already be using physician alignment for your clinical or recruitment approach, but it can do more, helping to diversify revenue sources, keep patients in your network, and strengthen performance.
A click deeper on policies impacting your organization’s bottom line:
The One Big Beautiful Bill Act is expected to reduce federal Medicaid funding substantially over the next decade, and uncertainty remains around enhanced ACA subsidies.
The Centers for Medicare & Medicaid Services (CMS), in its 2027 Hospital Outpatient Prospective Payment System (OPPS) and Ambulatory Surgery Center (ASC) proposed rule, proposed changing the payment formula for drugs acquired through the 340B program.
In that proposed rule, CMS also proposed paying for certain imaging services without contrast at off-campus hospital outpatient departments at the lower Physician Fee Schedule-equivalent rate. In the 2026 OPPS/ASC final rule, CMS eliminated the inpatient-only list, with a three-year transition starting with the reassignment of 285 procedures – and then proposed removing another 637 procedures in the 2027 OPPS/ASC proposed rule. These changes have many potential downstream financial implications: Certain commercial insurance plans could deny inpatient status and pay the lower outpatient rate, and there could be additional options for the same procedures to be performed in outside ASCs. Shifting cases out of the inpatient setting can also impact a health system in other ways, including DSH payments, IME/GME payments, 340B eligibility thresholds, Medicare bad debt, and state supplemental payment formulas.
1. Prepare for a more site-neutral environment
As site neutrality gains steam, services are increasingly moving out of hospitals and into clinics, ASCs, and other outpatient settings. Many health systems are already adapting, but there may be opportunities to take that strategy further by considering ASC, clinic, and physician alignment as a whole rather than approaching them as separate initiatives.
As reimbursement incentives change, health systems should evaluate whether a more nuanced physician alignment structure could strengthen network integrity and other system care goals. Options include ASC joint ventures, revised ASC-physician compensation arrangements, and group practice or clinic models that let physicians share in profits – often in combination.
How it could work:
ASC strategies can be designed to prioritize patient care and reward quality outcomes. Recent advisory opinion activity suggests there may be room for arrangements outside of traditional direct physician-ASC ownership, including structures that allow employed physicians to participate in the performance of an ASC enterprise. These approaches are fact-specific and warrant careful analysis.
Systems can also explore group-practice or clinic joint venture structures that better align physician productivity in a clinic environment.
There is no single model for every system. The right approach depends on the problem your organization is trying to solve, whether that is leakage to outside clinics, a limited outpatient or ASC footprint, or broader physician-alignment challenges. The Stark Law and AKS must be considered, but it is possible to develop structures that comply with their requirements.
2. Use compensation and contracts to strengthen alignment
Stronger physician alignment does not always require an acquisition, joint venture, or other capital-intensive initiative. Before going down those paths, your organization should consider whether existing physician compensation arrangements and contracts can be structured more effectively.
Traditional physician compensation models often deliver a salary and work relative value unit (wRVU) based compensation to physicians. While certainly a great starting point, there are other potential pathways and bonus structures that a health system could consider incorporating. Subject to a broader fraud and abuse review, such options might include a directed referral prong in employed or contracted physician contracts. CMS has even indicated that, from a Stark Law perspective, a physician could be paid a bonus or “withhold” contingent on the physician achieving a percentage (but not a number or value) of “in-network” referrals, so long as the payment otherwise meets the volume or value standards of an applicable Stark Law exception. (Other laws are potentially implicated, and specific requirements need to be satisfied under Stark Law.)
How it could work:
A health system or hospital can incorporate a directed-referral provision in a physician’s employment contract or PSA that allows for the physician to receive an additional bonus for achieving a certain in-network “keepage” threshold (with certain potential carve-outs). Such mechanisms can help align physician behavior with the health system’s network strategy while supporting operational and financial performance. This approach requires careful attention to Stark Law, AKS, and state-level requirements.
If structured strategically, these provisions can also provide the health system with meaningful insights as to why certain patients are migrating out of the health system.
Take advantage of low-hanging fruit that could save your organization time and capital. Determine whether the tools already in place can do more to support alignment and ensure your health system is able to maintain quality standards for your patients.
3. Use value-based structures to create more flexibility
The Stark Law and AKS value-based exceptions and safe harbors can provide additional flexibility for health systems looking to advance both clinical objectives and physician alignment. The exceptions and safe harbors create opportunities for health systems to design their own innovative payment models (which historically would have required CMS and OIG to issue fraud and abuse law waivers) to help incentivize shifts of patient care to a value-centric environment. Now, health systems and other providers can design similar constructs contractually – no need to register or create new legal entities.
Engaging in value-based care and structuring physician arrangements under relevant Stark Law exceptions and AKS safe harbors does not necessarily require a health system to take on risk. The exceptions and safe harbors can potentially apply even to traditional fee-for-service arrangements, as long as the endeavor arrangement meets certain requirements.
For instance, if certain regulatory requirements are satisfied, a physician compensation arrangement relying on a Stark Law value-based exception can take into account the volume or value of their referrals or pay compensation that is not necessarily commensurate with “fair market value.”2 But the value-based purpose must be genuine and commercially reasonable: The arrangement should advance care quality or another legitimate value-based objective rather than simply incentivize referrals.
How it could work:
Compensation arrangements with physicians can be structured to incentivize them to reduce avoidable hospital readmissions for a defined patient population by establishing care-coordination protocols and tying aspects of the physician arrangement to agreed-upon quality and patient-care objectives.
The underlying reimbursement may remain fee-for-service, while the arrangement is designed around a legitimate value-based purpose(s) by incentivizing the physicians to take (or in some instances refrain from taking) certain actions.
When structured appropriately, these models can support clinical goals while creating stronger alignment between physicians and the health system.
Hospitals and health systems face real financial headwinds, which lends new urgency to the old adage that “the mission is in the margin.” But not every path to stronger physician alignment runs through the capital budget. Leaders can act now by:
- Taking a more integrated approach to outpatient strategy
- Using compensation and contractual mechanisms more effectively
- Evaluating whether value-based structures provide additional flexibility
Start with your organization’s specific challenge and build the alignment strategy around it. With the right structure and appropriate fraud and abuse safeguards, your hospital or health system can strengthen physician relationships, improve patient outcomes, support financial performance, and position itself more effectively for a reimbursement environment that continues to evolve.
6 critical actions to take before an R&D credit audit
ARTICLE
6 critical actions to take before an R&D credit audit
September 21, 2026
Read time: 9 min
For a crash course on the basics, see our R&D credit FAQ. For more on this topic, revisit takeaways from our “R&D Credits: What the IRS Is Challenging and How Taxpayers Can Respond” webinar.
Now more than ever, the IRS has its eye on the federal research and development (R&D) tax credit, provided under Section 41 of the Internal Revenue Code for increasing research activities. And there are a lot of dollars at stake. For companies claiming these credits, an audit can be costly and time-consuming.
Recent changes to Form 6765 (which is used to claim the R&D tax credit) give examiners greater visibility into credit claims, requiring taxpayers to report business components, wage categories, and cost details at a granular level. At the same time, several recent decisions have reinforced that R&D credit audits are intensely fact-driven, and the outcome often turns on the quality of a company’s records – and how well they align with IRS requirements.
George v. Commissioner
Qualified research evaluated based on particular trials performed
Contemporaneous evidence and testimony supported some claimed research but not others
Illustrates fact-intensive application of substantially all
Chickens used in qualifying research trials could constitute pilot models giving rise to supply QREs
Little Sandy Coal Co. v. Commissioner
A new or technically complex product does not itself establish a process of experimentation
Focus on activities that actually constitute elements of experimentation
Highlights substantially-all requirement
Business-component and shrinking-back analyses matter
For general counsel at large companies, the stakes are high. Your organization may have thousands of employees, just as many projects, and research expenses incurred years before an audit begins. The engineers who worked on those projects don’t speak the language of Section 41, and the R&D was conducted to develop products, not an IRS audit file. The result is a landscape where even well-intentioned claims can unravel under scrutiny.
The good news? Most examinations turn on two fundamental questions:
- Did the taxpayer (your organization) perform qualified research?
- Are expenses claimed as qualified research expenses (QREs) properly connected to that research?
As a result, most audit pressure points are predictable. We have outlined six recommendations for addressing common issues before the IRS shows up at your door.
The single most important step a company can take is to build a strong audit record before an examination begins.
Start with the case you want to present: Identify the actual research and business components, apply Section 41 to the facts, pinpoint the people with firsthand knowledge, and gather evidence that proves the claim. Then find the weaknesses and fix them before the IRS finds them for you.
Business components remain a contentious area of R&D audits. Examiners routinely challenge components that aggregate multiple products or processes, components with generic or high-level descriptions, and customer-specific components that may look like adaptation rather than qualified research.
Where to start
- Define each business component at a level you can defend. Ask whether it satisfies the Section 41(d) four-part test altogether, and if not, whether a “shrinking-back” analysis applies.
- Make sure your documentation matches your definition. If your records describe something different from what you claimed, the IRS will notice.
- Keep your component definitions consistent with how you report them on Form 6765. Inconsistencies between the return and the study are red flags.
Developing a new product does not, on its own, establish a process of experimentation. You need to show how your team addressed uncertainty, what alternatives were identified, and how those alternatives were evaluated. The IRS focuses on the activities that actually constitute elements of experimentation, not the newness or complexity of the end product.
Where to start
- For each business component, document the uncertainty that existed regarding capability, methodology, or appropriate design.
- Identify the alternatives your team considered and the process you used to evaluate them, whether modeling, simulation, or systematic trial and error.
- Prove that at least 80% of the relevant research activities constituted elements of a process of experimentation.
Examiners often focus on job titles and lose sight of what an employee really did. Senior executives, project managers, sales and marketing personnel, and production employees frequently draw scrutiny, as do employees with mixed qualified and nonqualified activities.
Where to start
- Build your case around activities, not titles. Document what each employee did as part of their day-to-day work.
- Be prepared to explain why a person with a senior or sales-oriented title was engaged in qualified services.
- Anticipate the questions examiners ask about vague labels and have answers prepared. For example, a label of “value engineering” might trigger the exam question, “What did the employee actually do?”
A research credit study is an important starting point, but it is rarely enough on its own. Studies designed to calculate and support the credit often fail to answer the questions examiners really ask. Common pressure points include business components defined at a level that becomes difficult to defend, generic project or employee descriptions, retrospective time or activity estimates, and conclusions reached without underlying facts.
Where to start
- Treat the study as a foundation, not a finish line. The ultimate question is whether you can establish entitlement to the credit under Section 41, not whether a study exists.
- Pressure-test the study before the IRS does. Look for tension between study conclusions and contemporaneous company records, and resolve those conflicts proactively.
- Make sure your sampling methodology is one an examiner can reproduce and test without finding gaps.
Amended research credit claims attract significant scrutiny. An examiner will immediately ask – among other questions – what changed; why QREs are higher than on the original return; and whether the positions can be reconciled across the original return, the amended claim, contemporaneous records, and other tax positions.
Where to start
- Before filing an amended claim, map out exactly what changed and why. Be ready to explain any new activities, employees, costs, or business components.
- If a new or supplemental study was performed, or if qualification percentages or methodology changed, document the rationale clearly.
- Reconcile your positions across every source. Consistency across the original return, the amended claim, and contemporaneous records is essential.
R&D credit audits are challenging, but they are not unwinnable. Treat documentation as an ongoing discipline rather than a retrospective scramble.
By building a strong record from the beginning, along with defining your business components carefully, proving your process of experimentation, looking past job titles to actual activities, pressure-testing your study, and handling amended claims with care, you put your company in the best position to defend the credits it has earned.

Selling a stake or control: Some things we wish clients knew earlier
ARTICLE
Selling a stake or control: Some things we wish clients knew earlier
September 21, 2026
Read time: 14 min
As sophisticated as the alternative investment management industry has become over the last 20+ years, we still see a large percentage of firms that are not aware of, or have delayed, taking steps that would make selling all or part of their business easier and save on taxes.
Don’t let due diligence delay a deal
Understand what deal due diligence of your firm will look like. Clients are often underprepared in the following areas:
Financial books and records.
Books and records should be tidy and organized. Red flags should be addressed (e.g., late financials, aggressive business expensing, deficient evidence of capitalization and ownership). Audited management company financials are not necessary, but they will inevitably ease the due diligence process and should reduce the likelihood of a re-trade on price (assuming other unknown issues are not discovered later). Careful consideration should be given to preparing a sell-side quality of earnings report, particularly in an auction process.
Careful consideration should be given to preparing a sell-side quality of earnings report, particularly in an auction process.
Key personnel.
Key roles (COO, CFO, GC, CCO) should be the responsibility of individuals with appropriate experience and tenure for the applicable role. More times than we would admit, we have seen college roommates and relatives of the founder on their fourth career serve in one of these roles. This is not confidence-inspiring to a prospective buyer.
Compliance and record keeping.
Controllable business risk is within the purview of compliance. A recent US Securities and Exchange Commission (SEC) examination tends to put the compliance house in order. If your firm has not gone through an SEC exam, it is a wise move to undergo a mock examination well before buyer due diligence starts (even better, a year before seeking a buyer). For targets registered with the SEC, ensure that records that support the findings of your annual compliance reviews were completed in a timely manner, because those will be important features in any regulatory diligence by the buyer. We have seen deals delayed for weeks – and poor impressions on a buyer made – when compliance appears to be a low priority. Compliance red flags frequently turn into financial issues, triggering additional buyer-requested terms such as (potentially) significant escrows and holdbacks.
We have seen deals delayed for weeks – and poor impressions on a buyer made – when compliance appears to be a low priority.
Client buy-in.
Understand that direct client (and fund investor) consents will influence deal messaging. Control sales, as well as many minority and stake sales, require direct client and fund investor consents prior to being able to close. While a high percentage of direct client and fund investor consents are obtained in all manager deals, direct clients and fund investors expect to see that the deal will be at least neutral to, if not better for, the firm’s investment team, infrastructure, and operations (e.g., retention of key people, more resources for the manager).
Focusing on these issues before a deal gets rolling will save time and money when a transaction progresses. We have seen too many situations where clients have not adequately prepared for buy-side diligence or considered what the deal messaging will be until they have a deal in sight. This inevitably leads to delays and increased transaction costs.
Understand the tax planning and get it done well before seeking a buyer
If your plan is to have some or many employees participate in sale proceeds (as a reward/bonus or earn-out, or as part of a long-term incentive plan), the most valuable move you can make is to expand ownership (whether actual or phantom) well in advance of the sale event – years before, if possible.
The concept is simple: Anyone whom you want to have participate in sale proceeds needs equity to sell (and profit-only partner status may not be sufficient).
- The holder of that equity is rewarded with a gain in a sale transaction – ideally long-term capital gains treatment.
- There will likely be no long-term capital gains if the equity is issued less than three years before a sale.
- The issuance of equity at a discount to value could trigger a tax liability for the recipient.
- It is not market (save for a few exceptions) to ask employees to purchase equity in their firm. Equity awards (structured to be tax-free at issuance) are much more prevalent.
- Equity is usually nonvoting and subject to forfeiture upon departure.
The concept is simple: Anyone whom you want to have participate in sale proceeds needs equity to sell.
There are alternatives to equity awards, but they come with tradeoffs:
- A phantom equity plan can be implemented as alternative to real equity issuances and can achieve ownership-like objectives. However, these plans are unlikely to be as tax-advantaged as real equity.
- Special bonuses in connection with a sale are another alternative but generally will not have equity-like features. They will also be tax inefficient (no long-term capital gains and possibly not fully deductible).
- Deal-related bonuses (often paid over time post-closing) are ultimately a deduction from purchase price. Their timing, control over administration, deductibility, and tax withholding will need to be negotiated with the buyer and addressed in the deal documents.
There are alternatives to equity awards, but they come with tradeoffs.
The morale, expectations, and motivation of the nonequity recipients can also become a problem. We have seen key employees become resentful of the tax inefficiency of nonequity alternatives at a time when the founders need them to be excited and incentivized about a deal. And very often key employees who receive equity (or phantom equity) awards are a very important component for a successful transaction. If key people are unhappy about missing out on the materially lower long-term capital gains rates, that can strain the transaction process.
You would be amazed at how many important employees (and partners!) are excluded from participating in sale proceeds as a result of a lack of foresight on ownership issues.
You would be amazed at how many important employees (and partners!) are excluded from participating in sale proceeds as a result of a lack of foresight on ownership issues.
The solution: Adopt an equity issuance plan early
At first, most clients are reluctant to broaden equity ownership beyond the founder(s) or a very small senior group. However, partnership agreements provide tremendous flexibility. Done properly, a partnership agreement can enable the firm to have its cake and eat it too:
- Key employees can be given ownership and related incentives early, laying the groundwork for a tax-efficient transaction for all stakeholders.
- As a firm grows in value over time (hopefully), the employees participate in that new value at the time of the sale (and can be overallocated that value to catch them up to full value, if desired).
- The three-year capital gains rate holding period starts at issuance.
- The equity can have special terms, such as time and/or performance-based vesting, and can be designed to mimic a restricted stock unit.
- To protect the downside, those incentives can be designed to be taken away or discounted if the employee fails to perform as incentivized.
- Forfeiture of some (or all) equity if an employee leaves the firm before a sale is also a prevalent feature.
Many clients utilize an employee investment vehicle (EIV) to issue the equity.
- An EIV is a partnership or LLC that owns the equity in the firm. The employees own interests in the EIV. Effectively, the employees own firm equity indirectly.
- This means that the employees do not have direct rights under the firm’s partnership agreement. The EIV does, but the founder or principal owners control the EIV.
In many if not most cases, we have found that equity issuance early (with conditions) is a better approach than delayed or last-minute planning.
We work with executive compensation consultants such as our affiliate Eisenhandler & Co. to help our clients design an appropriate equity or nonequity alternative plan.
We work with executive compensation consultants such as our affiliate Eisenhandler & Co. to help our clients design an appropriate equity or nonequity alternative plan.
See our other publications, including “Looking ahead: Asset manager M&A in 2026,” or contact us for more information about investment manager M&A deal terms and negotiation points.
Where private equity is finding value in MedTech
ARTICLE
Where private equity is finding value in MedTech
September 18, 2026
Read time: 13 min
MedTech investment trends: Part 1 (Read Part 2, “Where MedTech is attracting PE attention with less FDA burden.”)
MedTech’s reset is creating openings for private equity, but disciplined diligence will separate opportunity from risk.
Private equity is putting more money into MedTech, but that capital is concentrating around fewer, bigger deals in faster-growing categories.
In the first half of 2026, MedTech mergers and acquisitions (M&A) value was roughly 160% higher than the same period in 2025, while the number of deals increased just 5%. Average deal value more than doubled, from slightly less than $1 billion to approximately $2.1 billion, according to EY and Capital IQ data.
These numbers point to a more selective MedTech market. Investors are focused on finding innovative businesses with strong growth prospects and recurring revenue models, while large MedTech companies are repositioning their portfolios toward faster-growing areas such as cardiovascular care, neurostimulation, and connected care.
Two key transaction strategies are emerging: carve-outs/divestitures and take-privates.
Recent transactions (including Blackstone and TPG’s acquisition of Hologic and American Industrial Partners’ agreement to acquire Avanos Medical for approximately $1.27 billion) demonstrate the scale of sponsor interest. KKR’s recently announced, approximately $5.7 billion acquisition of Integer further highlights the breadth of private capital moving into the MedTech ecosystem, including medical device contract manufacturing and refurbishing.
MedTech deal opportunities are plentiful, but to find the right ones and capitalize on them, investors need a disciplined targeting framework – including an in-depth understanding of all operational, regulatory, and execution risks.
What it looks like in practice
Acquiring a MedTech division or product line instead of the whole company.
Why strategics are selling
Through the first half of 2026, MedTech equities have been trading at a discount to the S&P 500. Large MedTech companies are increasingly focused on reducing portfolio complexity and are allocating resources to faster-growing areas or a subset of their overall portfolio. As a result, divisions or product lines that perform well but no longer fit the growth profile or long-term strategy of a publicly traded MedTech may become acquisition opportunities.
Why it appeals to PE firms
Carve-outs can provide established products, customers, regulatory clearances, and market share without purchasing an entire company. Buyers can grow the business through new products, new markets, or add-on acquisitions rather than relying mainly on cost-cutting measures. In many instances, a carve-out can even serve as a platform acquisition, delivering sufficient assets, operational capabilities, and financial scale to enter an attractive market segment.
What you should know
Buying a carve-out means separating a business from a larger, integrated enterprise, which involves complexities that can affect price, timing, and key deal terms. Buyers should understand:
- What comes with the business, including products, customers, permits, contracts, employees, real estate, and core technology (including owned, licensed, and commingled intellectual property)
- Where the acquired business still depends on the parent company (and for how long)
- What must be replaced after closing, including regulatory approvals, manufacturing support, intellectual property, documented quality controls, and operating systems
What it looks like in practice
Public MedTech companies going private.
Why the opportunity exists
Take-private opportunities in MedTech can emerge when the public market is not giving full credit to a company’s products, technology, or long-term growth prospects. The market may be focused on near-term earnings pressure, reimbursement uncertainty, uneven procedure volumes, or regulatory concerns – even though the underlying business still has durable assets and room to grow.
Why it appeals to PE firms
Buyers acquire a public platform at a valuation that may not reflect its longer-term potential and then support a multi-year value-creation plan outside the public markets. Taking the company private can give management more room to invest in research and development (R&D), improve commercial execution, pursue acquisitions, or reposition the business without the same quarter-to-quarter pressure.
What you should know
A lower stock price does not automatically mean the company is a bargain. Diligence should test whether the valuation gap reflects temporary market pressure or deeper issues, such as reimbursement risk, product performance, anticipated regulatory shifts, or a weaker pipeline.
Take-privates also require sponsors to manage a public-company process, not just negotiate a private acquisition. Financing, approvals, disclosure obligations, timing, and the possibility of a competing bid can all shape the deal.
Why it matters for investors: These considerations should feed directly into valuation and deal structure. If a target has weak reporting practices, unresolved inspection exposure, recurring quality issues, or a regulatory strategy that depends on untested assumptions, the buyer may seek a lower price, stronger deal protections through indemnification, more complex closing conditions, or a larger post-closing investment plan.
1. FDA scrutiny is shifting, not disappearing
For MedTech buyers, US Food and Drug Administration (FDA) diligence should go beyond whether approvals are in place. Recent FDA enforcement and inspection changes make a company’s regulatory and quality habits central to its value.
Trial-results reporting is a prime example. The FDA recently contacted more than 2,200 sponsors and researchers about thousands of studies that had missing required results or unresolved quality-control issues on ClinicalTrials.gov. Buyers should check whether a target has kept up with disclosure obligations and whether any gaps point to broader compliance weaknesses.
Buyers should also know that the FDA’s device inspection program has moved away from the old Quality System Inspection Technique (QSIT) checklist model and puts more weight on patient risk and real-world signals, including recalls and adverse-event reports. Issues in those areas can move a company to a higher priority on the FDA’s inspection radar. The FDA has already begun inspecting and issuing warning letters under the new Quality Management System Regulation that went into effect in February 2026.
Naturally, enforcement issues can affect valuation. Enforcement issues can affect valuation. A reporting failure can become a pricing issue, an indemnity issue, or a reason to walk away (as demonstrated by a March 2026 deferred prosecution agreement tied to allegedly unfiled adverse-event reports).
2. FDA scrutiny extends to AI
AI-enabled devices and diagnostics are another area where the regulatory path can shape value. For example, the FDA has finalized guidance on predetermined change control plans for AI-enabled device software, giving companies a clearer way to plan for certain model updates up front, facilitating product evolution and growth.
Why it matters for investors: For large language model (LLM) based medical products, the FDA’s digital mental health work offers an important signal about where the FDA may focus next (although it remains preliminary). The key question for investors is whether a business can keep the technology current while staying within FDA expectations. FDA’s very recent discussion paper on generative AI-enabled medical devices is a clear indicator that the agency is working toward regulating the technology – with questions remaining around when and how that will unfold.
3. The MedTech customer is changing, too
Buyers looking to invest in MedTech should be aware of another important shift that is happening on the demand side, where the continued focus on site neutrality is moving more procedures out of hospitals and into ambulatory surgery centers (ASCs) and other outpatient settings.
The Centers for Medicare and Medicaid Services (CMS) has proposed continuing to phase out Medicare’s inpatient-only list, including removing another 638 services. Alongside the 2026 ASC Covered Procedures List expansion, this could move more procedures into lower-cost outpatient settings and push hospitals to shed non-core equipment and service businesses.
Why it matters for investors: As care moves beyond hospitals, device purchasing may move with it. ASCs and free-standing sites have different budgets, buying priorities, and service needs, which can change how MedTech companies must price, sell, and support their products.
MedTech’s M&A market is becoming more concentrated, but the opportunity for private equity is expanding in important pockets. Strategic portfolio reshuffling is bringing carve-out candidates to market, while public valuations are creating openings for take-private transactions.
As more high-quality assets come to market, competition and increased scrutiny will follow. Sponsors must be well prepared long before a deal is on the table, including:
- Build FDA expertise into diligence early (along with reimbursement expertise, where relevant)
- Understand a carve-out’s operational and separation requirements (and the effect on deal terms, timing, and post-close plans)
- Pressure-test the value-creation plan against regulatory, reimbursement, and execution risks
The investors best positioned for the next phase of MedTech M&A will be those that understand not only where high-value assets are becoming available, but why, and what it will take to unlock that value.
To learn more about these trends and their implications for MedTech investors, contact the authors or your McDermott lawyer. We will also be discussing these developments and more at our upcoming Healthcare Private Equity NYC and Life Sciences Investment Forum.