ARTICLE / CLIENT ALERT / RESOURCE / US POLICY
Biden-Harris Administration Approves First Major Offshore Wind Project in US Waters
May 13, 2021
Read time: 5 min
Today, the Biden administration approved the first major offshore wind project in US Waters. The Vineyard Wind project, located approximately 12 nautical miles offshore Martha’s Vineyard, will consist of 800megawatts. The project will serve as a milestone towards the administration’s goal of deploying a minimum of 30 gigawatts of offshore wind in the US by 2030.
Prior to this announcement, Energy Secretary Jennifer Granholm released a statement reinforcing the administration’s commitment to investing resources in offshore wind. The Secretary expects offshore wind to provide a boom to the American economy and boost job growth nationwide through a joint effort by the departments of Energy, Interior, and Commerce.
To support the goal of deploying 30 gigawatts of energy from offshore wind by 2030, the Bureau of Ocean Energy Management (BOEM) will conduct new lease sales and finalize the review of more than a dozen construction and operating plans for wind development by 2025. Additionally, the Biden administration plans to accelerate the permitting of projects, which will give developers, owners and investors the opportunity to build projects quicker, inevitably creating more jobs and stimulating the economy.
In addition, the Biden administration announced the designation of an 800,000-acre area of federal waters off the coast of Long Island and New Jersey for the development of offshore wind projects. The decision is part of the Biden administration’s broader initiative to expand U.S. wind production, marking offshore development as a particular priority. With this announcement, the amount of renewable energy projects are expected to significantly increase.
The Biden administration believes that over $12 Billion of debt will need to be invested annually in renewable energy projects. Industry leaders have noted that the increase in renewable energy projects is not likely to impact terms of project finance deals, as such terms are usually driven by banking and other markets. However, there remains an open question about whether the current size of the tax equity market (around $16 Billion a year) will be sufficiently large to support financing of the offshore wind market. Industry players have long advocated for an expansion of the tax equity market to corporate investors and other non-financial companies to support ongoing growth of the sector.
According to BOEM, many sectors will benefit from the goals set by the Biden administration, as there will be the need for, among others things, upgrading ports, creating turbine installation vessels and wind turbine manufacturing. To date, more than $2 Billion of infrastructure investments to support offshore wind developments have been announced.
The Biden administration also announced an information sharing arrangement with Denmark based renewable energy company Orsted and the National Oceanic and Atmospheric Administration (NOAA). Orsted is constructing a 1,100-megawatt wind farm 15 miles off the southern coast of New Jersey, which is expected to power a half million homes. The data-sharing plan relates to data gathered in federal waters leased by Orsted to assist in future development in the area. BOEM will prepare an environmental impact statement for the project, which will be the third commercial-size offshore wind project in the nation. This arrangement will serve as a boost to jobs, economic growth, and create clean energy opportunities, not only for investors and developers, but also for Americans across the nation.
In an effort to increase funding opportunities for offshore wind projects, the US Department of Transportation’s Maritime Administration announced a grant program to allow port authorities and other eligible applicants to request grants from a $230 million infrastructure fund and the Department of Energy unveiled a $3 billion Innovative Energy Loan Guarantee Program.
Offshore wind developments received an additional boost following the unveiling of the American Jobs Plan, which is aimed at rebuilding America’s infrastructure to be in a position to fight climate change and bolster the economy. As part of the comprehensive plan, the offshore wind industry will be impacted through upgrades to the nation’s transmission system, revitalization of ports vital to offshore wind operations and investments into research and development projects such as floating offshore wind. The Plan demonstrates the central role offshore wind will play in the Biden administrations goal to fight climate change and position the US as the global leader in clean energy. One specific goal of the plan is to “position the US to out-compete China.” Meeting this goal will according to the Biden administration, “require an investment in America in a way we have not invested since we built the interstate highways and won the Space Race.”
These announcements follow through on Biden’s January 27, 2021 Executive Order, which confronts climate change by calling for doubling the nation’s off shore wind capacity over the next decade. Biden’s executive order also encourages the development of other renewable infrastructure on federal and tribal lands.




The FBCSI Branch Rules: Parsing Example 3
ARTICLE
The FBCSI Branch Rules: Parsing Example 3
May 13, 2021
Read time: 1 min

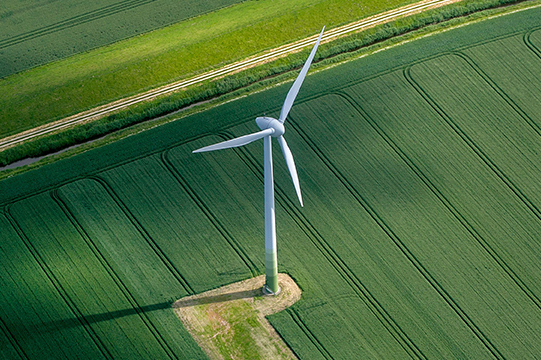
Biden-Harris Administration Approves First Major Offshore Wind Project in US Waters
ARTICLE / CLIENT ALERT / US POLICY
Biden-Harris Administration Approves First Major Offshore Wind Project in US Waters
May 12, 2021
Read time: 5 min
On May 11, the Biden Administration approved the first major offshore wind project in US waters. The Vineyard Wind project, located approximately 12 nautical miles offshore Martha’s Vineyard, will consist of 800-megawatts and will serve as a milestone towards the administration’s goal of deploying a minimum of 30 gigawatts of offshore wind in the US by 2030.
Today, the Biden Administration approved the first major offshore wind project in US waters. The Vineyard Wind project, located approximately 12 nautical miles offshore Martha’s Vineyard, will consist of 800-megawatts and will serve as a milestone towards the administration’s goal of deploying a minimum of 30 gigawatts of offshore wind in the US by 2030.
Prior to this announcement, Energy Secretary Jennifer Granholm released a statement reinforcing the administration’s commitment to investing resources in offshore wind. The Secretary expects offshore wind to provide a boom to the American economy and boost job growth nationwide through a joint effort by the departments of Energy, Interior and Commerce.
To support the goal of deploying 30 gigawatts of energy from offshore wind by 2030, the Bureau of Ocean Energy Management (BOEM) will conduct new lease sales and finalize the review of more than a dozen construction and operating plans for wind development by 2025. Additionally, the Biden Administration plans to accelerate the permitting of projects, which will give developers, owners and investors the opportunity to build projects quicker, inevitably creating more jobs and stimulating the economy.
In addition, the Biden Administration announced the designation of an 800,000-acre area of federal waters off the coast of Long Island and New Jersey for the development of offshore wind projects. The decision is part of the Biden Administration’s broader initiative to expand US wind production, marking offshore development as a particular priority. With this announcement, the amount of renewable energy projects are expected to significantly increase.
The Biden Administration believes that over $12 Billion of debt will need to be invested annually in renewable energy projects. Industry leaders have noted that the increase in renewable energy projects is not likely to impact terms of project finance deals; as such terms are usually driven by banking and other markets. However, there remains an open question about whether the current size of the tax equity market (around $16 Billion a year) will be sufficiently large to support financing of the offshore wind market. Industry players have long advocated for an expansion of the tax equity market to corporate investors and other non-financial companies to support ongoing growth of the sector.
According to BOEM, many sectors will benefit from the goals set by the Biden Administration, as there will be the need for, among others things, upgrading ports, creating turbine installation vessels and wind turbine manufacturing. More than $2 Billion of infrastructure investments to support offshore wind developments have been announced to date.
The Biden Administration also announced an information sharing arrangement with Denmark based renewable energy company Orsted and the National Oceanic and Atmospheric Administration (NOAA). Orsted is constructing a 1,100-megawatt wind farm 15 miles off the southern coast of New Jersey, which is expected to power a half million homes. The data-sharing plan relates to data gathered in federal waters leased by Orsted to assist in future development in the area. BOEM will prepare an environmental impact statement for the project, which will be the third commercial-size offshore wind project in the nation. This arrangement will serve as a boost to jobs, economic growth and create clean energy opportunities, not only for investors and developers, but also for Americans across the nation.
In an effort to increase funding opportunities for offshore wind projects, the US Department of Transportation’s Maritime Administration announced a grant program to allow port authorities and other eligible applicants to request grants from a $230 million infrastructure fund and the Department of Energy unveiled a $3 billion Innovative Energy Loan Guarantee Program.
Offshore wind developments received an additional boost following the unveiling of the American Jobs Plan, which is aimed at rebuilding America’s infrastructure to be in a position to fight climate change and bolster the economy. As part of the comprehensive plan, the offshore wind industry will be impacted through upgrades to the nation’s transmission system, revitalization of ports vital to offshore wind operations and investments into research and development projects such as floating offshore wind. The American Jobs Plan demonstrates the central role offshore wind will play in the Biden Administration’s goal to fight climate change and position the US as the global leader in clean energy. One specific goal of the plan is to “position the US to out-compete China.” Meeting this goal will, according to the Biden Administration, “require an investment in America in a way we have not invested since we built the interstate highways and won the Space Race.”
These announcements follow through on Biden’s January 27th Executive Order, which confronts climate change by calling for doubling the nation’s offshore wind capacity over the next decade. Biden’s executive order also encourages the development of other renewable infrastructure on federal and tribal lands.


You Want Some ‘Metchup’ with That?
ARTICLE
You Want Some ‘Metchup’ with That?
May 11, 2021
Read time: 1 min




Next-Generation Health System and Private Equity Partnerships: Driving Innovation
ARTICLE
Next-Generation Health System and Private Equity Partnerships: Driving Innovation
May 11, 2021
Read time: 1 min






What Employers Need to Know About the NY HERO Act
ARTICLE / CLIENT ALERT
What Employers Need to Know About the NY HERO Act
May 11, 2021
Read time: 16 min
On May 5, 2021, Governor Cuomo signed into law the New York Health and Essential Rights Act (“HERO Act”) to combat the spread of COVID-19. The HERO Act adds two sections to the New York Labor Law: (1) the prevention of occupational exposure to an airborne infectious disease and (2) workplace safety committees. The HERO Act’s first provision is effective on June 4, 2021, and its second provision is effective on Nov. 1, 2021.
Section 1: Prevention of Occupational Exposure to Airborne Infectious Diseases
Coverage and Effective Date
Effective June 4, 2021, the New York State Department of Labor (“NYSDOL”) is directed, in consultation with the New York State Department of Health, to create and publish a model airborne infectious disease exposure prevention standard, differentiated by industry, for all work sites. All employers in New York will be required to adopt and provide to all of their employees an airborne infectious disease exposure prevention plan to protect employees from exposure to COVID-19 and other infectious diseases in the workplace as described below. Notably, “employee” is defined to include independent contractors, part-time workers, domestic workers, home care workers, temporary and seasonal workers, and individuals working for staffing agencies, contractors and subcontractors working on behalf of an employer at a work site. “Work site” is defined to mean “any physical space, including a vehicle, that has been designated as the location where work is performed.” “Employer” is defined to cover almost any entity or person that pays individuals for labor, regardless of size or number of employees.
The Model Prevention Plan
This NYSDOL model standard will establish minimum requirements for preventing exposure to airborne infectious diseases in the workplace. These standards will include requirements for employers on procedures and methods for:
- Employee health screenings;
- Face coverings;
- Required personal protective equipment applicable to each industry;
- Accessible workplace hand hygiene stations and maintaining healthy hand hygiene;
- Regular cleaning and disinfecting of shared equipment and frequently touched surfaces;
- Effective social distancing for employees and consumers/customers;
- Compliance with mandatory or precautionary orders of isolation or quarantine;
- Compliance with applicable engineering controls such as proper air flow and exhaust ventilation;
- Designation of one or more supervisory employees to enforce compliance with airborne infectious disease exposure plans and laws, rules, regulations or guidance;
- Verbal review of infectious diseases standard, employer policies and employee rights under this section; and
- Anti-retaliation requirements.
Employers’ Obligations
Employers are required to establish an airborne infectious disease exposure prevention plan either by adopting the model standard relevant to their industry or by establishing an alternative plan that equals or exceeds the minimum standards set forth by the model standard.[1] Employers must provide their prevention plans to all their employees (broadly defined above) in writing in English and in the language identified by each employee as his or her primary language upon reopening after a period of closure due to airborne infections disease, at the time of hiring, and upon the effective date of the HERO Act if the employer is permitted to operate at that time. Employers must also make their prevention plans available, upon request, to employees, collective bargaining representatives, if any, and the Commissioner of Labor and the Commissioner of Public Health. In addition, employers must post their prevention plans in a visible and prominent location within their work sites and include the prevention plan in their employee handbooks.
Anti-Discrimination and Retaliation
Employers are prohibited from discriminating, retaliating or taking adverse action against any employee for exercising their rights under this section (such as by requesting a copy of their employer’s prevention plan or bringing a civil action against their employer) or under the applicable prevention plan, for reporting violations of the applicable prevention plan, or for refusing to work when such employee reasonably believes, in good faith, that such work exposes workers or the public to an unreasonable risk of exposure to an airborne infectious disease due to the existence of working conditions that are inconsistent with law, including the model prevention standards, provided that the employer was notified of, or had or should have had reason to know about, these inconsistent conditions and the employer failed to cure such conditions.
Penalties
The NYSDOL may, following an investigation, assess a civil penalty upon an employer or person found to have violated any provision of this section. This civil penalty may not be less than $50 per day for failure to adopt an airborne infectious disease exposure prevention plan, and may not be less than $1,000 or more than $10,000 for failure to abide by an adopted prevention plan. These penalties may increase if the NYSDOL finds that the employer had violated this section in the preceding six years. The NYSDOL also may seek a court order to enjoin or restrain the commission or continuation of unlawful acts.
Additionally, any employee is authorized to bring a civil action seeking injunctive relief against an employer alleged to have violated an applicable prevention plan in a manner that creates a substantial probability that death or serious physical harm could result, unless the employer did not, and could not with the exercise of reasonable diligence, know the presence of the violation. Courts are authorized to grant injunctive relief, reasonable attorneys’ fees and costs and liquidated damages to successful claimants. However, an employer will not be liable for this relief where the employer proves it had a good faith basis to believe that its established health and safety measures were in compliance with the applicable prevention standard(s). Note that if an action brought by an employee (or a defense, counterclaim, or cross claim is brought by an employer in response) is found by a court to be “completely without merit in law and undertaken primarily to harass or maliciously injure,” the court may award sanctions.
Section 2: Workplace Safety Committees
Coverage and Effective Date
This section covers all employers that employ at least 10 employees and is effective on Nov. 1, 2021.
Safety Committees’ Makeup
Employers must allow their employees to establish and administer joint labor-management workplace safety committees. Each safety committee shall be composed of employee and employer designees, provided two-thirds of the committee are non-supervisory employees (selected by non-supervisory employees). Where a collective bargaining agreement is in place, the collective bargaining representative is responsible for selecting employees to serve on the committee. Committees shall be co-chaired by a representative of the employer and of non-supervisory employees.
Safety Committees’ Powers
Each safety committee and workplace safety designee will be authorized to perform the following actions, among others:
- Raise health and safety concerns, hazards, complaints and violations to the employer to which the employer must respond;
- Review any policy put in place in the workplace required by any provision of the Labor Law or any provision of the Workers’ Compensation Law;
- Review the adoption of any policy in the workplace in response to any health or safety law, regulation or executive order;
- Participate in any site visit by any governmental entity responsible for enforcing safety and health standards;
- Review any report filed by the employer related to the health and safety of the workplace; and
- Schedule a meeting during work hours at least once a quarter.
Anti-Retaliation and Penalties
Employers are prohibited from retaliating against any employee who participates in the activities or establishment of a safety committee for any actions taken pursuant to their participation. Violations of this section will be subject to civil penalties and injunctive relief ordered by the NYSDOL, and civil actions from affected employees for injunctive relief, reasonable attorneys’ fees and costs and liquidated damages of up to $20,000.
Next Steps
In signing the HERO Act, Governor Cuomo and the New York State Legislature agreed to a still-not-public amendment to make certain technical changes to the bill, including giving the NYSDOL and employers more specific instructions in developing and implementing the workplace standards, including a clear timeline, and providing for an immediate requirement for employers to cure violations in order to better protect the safety of workers, and limit lengthy court litigation to those private rights of action where employers are acting in bad faith and failing to cure deficiencies. This amendment is forthcoming.
Employers should be prepared to adopt the NYSDOL’s airborne infectious disease safety standards and model prevention plans when those are released. In the meantime, employers should continue to review their existing return-to-work guidelines and health and safety plans and protocols for compliance with existing federal, state and local health and safety requirements or guidance. Employers with employees represented by unions may seek to waive either or both sections of the HERO Act in their collective bargaining agreements, provided that such agreements explicitly reference the section(s) of the HERO Act being waived. The joint labor-management committees may have implications under federal labor law, and may be subject to legal challenge.
As always, if you have any specific questions about the HERO Act or how it impacts your organization, you should contact your SRZ attorney.
Authored by Mark E. Brossman, Ronald E. Richman, Scott A. Gold, Donna K. Lazarus and Abdulrahman Alwattar.
[1] Any alternative plan must be developed in tandem with the employees’ collective bargaining representative, if any, or with meaningful participation of employees where there is no such representative. This plan must be tailored and specific to the hazards in the specific industry and work sites of the employer.
This communication is issued by Schulte Roth & Zabel LLP for informational purposes only and does not constitute legal advice or establish an attorney-client relationship. In some jurisdictions, this publication may be considered attorney advertising. ©2021 Schulte Roth & Zabel LLP.
All rights reserved. SCHULTE ROTH & ZABEL is the registered trademark of Schulte Roth & Zabel LLP.






Employers Should Prepare for New York’s Most Stringent Workplace Safety Law
ARTICLE / CLIENT ALERT
Employers Should Prepare for New York’s Most Stringent Workplace Safety Law
May 10, 2021
Read time: 6 min
Update: On September 6, 2021, New York Governor Kathy Hochul designated COVID-19 as a disease to be covered by the NY HERO Act. McDermott has provided updated guidance, available here.
On May 5, 2021, New York Governor Andrew Cuomo signed into law the New York Health and Essential Rights (HERO) Act, which imposes stringent new workplace safety requirements for all employers in New York. The law is expected to take effect on June 4, 2021.
EMPLOYER REQUIREMENTS
The HERO Act requires the New York Commissioners of Labor and Health to create a model airborne infectious disease exposure prevention standard (“Model Plan”) for all employers across the state, differentiated by industry. The Model Plan will include requirements for, among other things:
- Employee health screenings;
- Required personal protective equipment;
- Cleaning and disinfecting requirements;
- Appropriate social distancing measures;
- Compliance with quarantine orders or precautionary orders of isolation;
- Designation of one or more employees to enforce compliance with the Model Plan, and any relevant federal, state or local laws;
- Verbal review, workplace posters and development of a personnel policy regarding the Model Plan; and
- Anti-retaliation requirements.
Employers can adopt their own policy but it (1) must meet the minimum standards of the Model Plan, and (2) must be developed in conjunction with the employees’ collective-bargaining representative; or, if not applicable, then with “meaningful participation” of employees. The HERO Act provides no guidance on what “meaningful participation” requires.
The law includes a laundry list of areas that constitute a “workplace” for purposes of determining whether a safety plan is required. This list includes typical areas, like warehouses and office spaces; but for employees who work in roles such as rideshare drivers, it can include vehicles, and for domestic employees, it can include the employer’s own home.
EMPLOYEE RIGHTS
Employers may not discriminate, threaten, retaliate against or take any adverse action against any employee for:
- Exercising their rights under the HERO Act or under an employer’s workplace safety plan (i.e., by participating in the activities or creation of a workplace safety committee, detailed below);
- Reporting violations of the HERO Act or the applicable workplace safety plan;
- Reporting a concern of exposure to an airborne infectious disease or seeking help or intervention regarding any such concern, whether to their employer or to a governmental authority; or
- Refusing to work where the employee reasonably believes, in good faith, that such work exposes the employee, other workers or the public, to an unreasonable risk of exposure to an airborne infectious disease due to working conditions that are inconsistent with the laws, rules or policies of any government entity or the applicable workplace health and safety plan.
LABOR-MANAGEMENT WORKPLACE SAFETY COMMITTEE
Employers with at least 10 employees must permit employees to establish a joint labor-management workplace safety committee, with at least two-thirds of the committee comprised of non-supervisory employees. Employee members must be selected by non-supervisory employees (or, if a union is in place, the union will select employee representatives).
Committee members must be permitted to regularly schedule meetings during work hours, at least once a quarter, and to attend a training (without loss of pay) on the function of safety committees and an introduction on occupational safety and health.
PENALTIES FOR NON-COMPLIANCE
The HERO Act creates a private right of action for employees alleging violations of the plan “in a manner that creates a substantial probability that death or serious physical harm could result” unless the employer did not know, and could not reasonably have known, about the violation. Employers may proffer a good-faith compliance defense.
If an employer is found to have violated the statute, the penalty is a civil fine of at least $50 per day for failure to adopt a safety plan, or at least $200 per day if the employer has already committed this violation at least once in the last six years. In addition, employers may be fined anywhere from $1,000 to $10,000 for failure to abide by an adopted plan, or up to $20,000 if the employer has already committed this violation at least once in the last six years.
LOOKING AHEAD
Gov. Cuomo’s signing of the HERO Act came with the caveat that it would be amended to give employers a cure period for alleged violations so that penalties will capture only bad-faith employers and will not embroil well-intentioned actors in lengthy litigation. There is no language (yet) for this proposed amendment, but the state legislature is expected to address it in the coming days.
The HERO Act comes at a time when the entire country awaits publication of the much-anticipated workplace safety standards to be published by the Occupational Safety and Health Administration (OSHA), and shortly after OSHA published its guidance for employers considering whether to recommend or require employee vaccinations.
HOW EMPLOYERS SHOULD PREPARE
We anticipate that the Model Plan may follow many of the same requirements that New York State mandated in 2020 for employers’ return-to-work policies during the pandemic. Employers should be prepared to update their New York-compliant return-to-work policies that are already in place.
Employers should also prepare to disseminate their new workplace safety plans once ready and provide supervisors with compliance and anti-retaliation training.
Employers with at least 10 employees should prepare to establish, or permit the establishment of, a labor-management workplace safety committee.
We can help you tailor pre-existing policies to the Model Plan’s requirements once published, in addition to any applicable OSHA requirements and state and local reopening guidelines. We are available to answer any of your questions related to the HERO Act.

Finding John Doe, Part II: IRS Secures Another Victory to “Root Out” Virtual Currency Tax Noncompliance
ARTICLE / CLIENT ALERT
Finding John Doe, Part II: IRS Secures Another Victory to “Root Out” Virtual Currency Tax Noncompliance
May 7, 2021
Read time: 6 min
The Internal Revenue Service (IRS) has scored another significant victory in its rapidly increasing virtual currency tax enforcement efforts. On May 5, 2021, the US District Court for the Northern District of California entered an order authorizing the IRS to serve a John Doe summons on popular cryptocurrency exchange, Payward Ventures Inc. d/b/a Kraken (Kraken). Specifically, the court’s order grants the IRS permission to serve a John Doe summons on Kraken in order to obtain information on US taxpayers who conducted the equivalent of at least $20,000 in total transactions for each year from 2016 to 2020.
If the IRS follows its playbook from the Coinbase summons, its victory here and with the Poloniex summons (upheld by a court in Massachusetts a few weeks ago), will likely result in thousands of US taxpayers receiving a letter from the IRS regarding their virtual currency transactions. As noted in its response to the court, over the past few years the IRS has learned a great deal about analyzing these transactions and is in possession of information from foreign virtual currency exchanges it’s also analyzing. This victory, coupled with the IRS’ increased knowledge of virtual currency transactions, is a big step in its efforts to, as stated in the IRS’ court filing, “root out tax noncompliance.”
As we previously noted in “Finding John Doe: IRS Steps up Enforcement Efforts to Take the Anonymity Out of Virtual Currency,” the court ordered the government to submit a response explaining its need for the information requested in its summons to Kraken. The government’s response indicates that the IRS has made significant progress in its analysis of summoned data from other cryptocurrency exchanges, such as Coinbase, and its ability to follow leads in the cryptocurrency marketplace. The court’s order approving the summons significantly reinforces the strength of the IRS’ crypto pursuit. These efforts are not solely focused on identifying tax noncompliance at a single exchange like Kraken but to identify the conduct for individuals transacting in cryptocurrency with Kraken accounts who may have additional accounts at other exchanges.
In citing its need for additional information to the court, the IRS expressly stated that in its experience from processing the Coinbase summons information, it has learned that taxpayers will use aliases, false addresses, post office boxes, fictitious entity names or other means to disguise their true identity. Taxpayers who create and use false information are more likely to evade their taxes, the IRS argued. The summons approved by the court requires Kraken to produce extensive records and data regarding its accountholders. Among other things, the summons requires Kraken to produce the following for each US-based account with at least $20,000 in annual transactions:
- Account registration records and user profile information, including name, date of birth, taxpayer ID number, physical address, email address and telephone number
- History of any IP addresses used to access the account
- Payment method information, such as linked bank or credit card account numbers
- Account transaction activity, including records reflecting the date, time, amount and value of any cryptocurrency transaction
- Account funding records, including records of any deposits or withdrawals via automated clearing house (ACH) or wire transfer
These records, including historic information, will allow the IRS to determine the true identities of Kraken accountholders, many of whom likely attempted to engage in transactions under the IRS’ radar. Once the IRS has linked a Kraken accountholder to a US taxpayer, the IRS will then be able to use the Kraken data, tax records and data from other cryptocurrency exchanges and offshore accounts to determine whether the taxpayer has complied with the internal revenue laws.
In response to the court’s decision, the IRS reiterated its commitment to pursue cryptocurrency tax violations. “There is no excuse for taxpayers continuing to fail to report the income earned and taxes due from virtual currency transactions,” said Charles Rettig, IRS Commissioner. “This John Doe summons is part of our effort to uncover those who are trying to skirt reporting and avoid paying their fair share.”
For its part, the US Department of Justice (DOJ) also stressed its support for such actions. “Gathering the information in the summons approved today is an important step to ensure cryptocurrency owners are following the tax laws,” said David A. Hubbert, Acting Assistant Attorney General of the DOJ’s Tax Division. “Those who transact with cryptocurrency must meet their tax obligations like any other taxpayer.”
It is no secret that cryptocurrency is in the IRS’ crosshairs. The IRS’ increased use and the courts authorization of the John Doe summons on popular cryptocurrency exchanges continues to demonstrate the growing strength of the IRS’ arsenal of tax collection tools. As the cryptocurrency market continues to grow, so too will enforcement agencies’ interest to make sure it is not being used for nefarious purposes.
Practice Point: As we noted previously in, “Finding John Doe: IRS Steps up Enforcement Efforts to Take the Anonymity Out of Virtual Currency,” taxpayers who have engaged in virtual currency transactions should immediately assess any potential tax and criminal implications, and businesses in this industry should carefully review their policies and processes to ensure that they address potential tax avoidance and anti-money laundering risks associated with their operations. If you have bought, sold, traded or gifted virtual currency, the IRS will expect to see some reporting of that transaction. Additionally, the IRS will be interested if you have received virtual currency in exchange for anything of value, including your services. If you are in the virtual currency industry, the IRS and the DOJ will be scrutinizing your business and your customers and will be asking whether you have addressed the risk of tax evasion or anti-money laundering in your compliance programs. Before the IRS comes knocking with a search warrant or summons, consider being proactive and taking measures to protect yourself, your business and your customers.
Finally, as recently announced, US President Joe Biden plans to give the Tax Man significantly more resources to tackle these noncompliance issues and make sure everyone “pays their fair share.” If the IRS follows its playbook, thousands of letters may be coming soon and multi-million dollar fines for entities, both in the United States and offshore. Now is the time to make sure you don’t get a letter or a visit. Don’t get caught unprepared.


Key Takeaways: Decoding the Future Value of Behind-the-Meter Load for Cryptocurrency and Computing: A Conversation with Compute North Executives
ARTICLE / CLIENT ALERT
Key Takeaways: Decoding the Future Value of Behind-the-Meter Load for Cryptocurrency and Computing: A Conversation with Compute North Executives
May 6, 2021
Read time: 3 min
On May 5, McDermott Will & Emery partners Ed Zaelke and Chris Gladbach hosted P.J. Lee, Dave Perrill and Jeff Jackson of Compute North to discuss the relationship between the rapidly expanding computing and cryptocurrency industries and the power sector.

Below are the key takeaways from the webinar:
- Compute North’s business model focuses on the power of distributed computing in cryptocurrency mining and large-scale data processing for uses with non-essential, flexible demand. By responding to real-time demand response signals and shutting down in less than 10 seconds, these distributed computing facilities can also participate in the demand response market and act as ancillary service resources.
- Modular computing facilities (similar to modular energy storage) allow distributed computing loads to be located nearer to generation, reducing congestion and curtailment risks and providing new customers for merchant facilities and other stranded power producing assets.
- Compute North’s distributed computing facilities are targeted at facilities as low as 20 MW in size, but are considering facilities of up to a full buildout of 1 GW.
- Although Compute North’s distributed computing currently requires higher use factors (and likely imports from the grid or separate generation assets), one of its long-term goals is to match the generation of a particular power producing facility.
- Successful cryptocurrency mining and other flexible distributed computing needs require computing facilities to be the lowest marginal cost producer. By providing services at 1/15th the cost of hypercomputing technologies, new data processing work cases are likely further increasing the demand for and power of distributed computing.
Visit the Navigating The New Energy Landscape Resource Center to access past webinars in this series and to begin receiving Energy updates, including invitations to the webinar series.

IRS Releases Guidance on Cryptocurrency Hard Forks
ARTICLE / CLIENT ALERT
IRS Releases Guidance on Cryptocurrency Hard Forks
May 6, 2021
Read time: 8 min
On April 9, 2021, the Internal Revenue Service (IRS) released Chief Counsel Advice memo 202114020 (Hard Fork CCA), which details the potential tax consequences for taxpayers who held Bitcoin prior to the August 1, 2017, Bitcoin hard fork. While the Hard Fork CCA concerns the taxation of a particular cryptocurrency transaction, it has additional significance because it adds to the limited guidance available regarding the proper taxation of cryptocurrency more generally.
A cryptocurrency hard fork occurs when the blockchain on which cryptocurrency transactions are recorded permanently splits. The holder of the cryptocurrency generally has no control or notice that the hard fork is about to occur. The result is two separate blockchains with two separate sets of rules for recording transactions.
Bitcoin underwent a hard fork on August 1, 2017, and resulted in two separate sets of protocols for Bitcoin, as well as a new cryptocurrency called Bitcoin Cash. The result of this hard fork was that individuals holding Bitcoin in a distributed ledger now held a unit of Bitcoin Cash for each unit of Bitcoin previously held.
The Hard Fork CCA reached two conclusions concerning the Bitcoin hard fork. First, it determined that a taxpayer who received Bitcoin Cash because of the hard fork has gross income pursuant to Internal Revenue Code (IRC) section 61. Second, it determined that the date of receipt and fair market value of the income depends on when the taxpayer obtains dominion and control over the Bitcoin Cash. The Hard Fork CCA relies on the statutory language of IRC Section 61(a)(3) and the well-established case law of Commissioner v. Glenshaw Glass Company (348 U.S. 426, 431 (1955) in reaching this result. Those sources define gross income as “all income from whatever source derived,” and provide that all gains or undeniable accessions to wealth, clearly realized, over which a taxpayer has complete dominion are included in gross income. The Hard Fork CCA also concludes that an impacted taxpayer gains dominion over Bitcoin Cash when they have the ability to sell, transfer or exchange the Bitcoin Cash.
Despite the fact that the Hard Fork CCA deals specifically with the consequences of the Bitcoin hard fork, the dearth of IRS guidance on the taxation of cryptocurrencies means the Hard Fork CCA will likely have broad importance to taxpayers who invest in other cryptocurrencies and similar digital assets. Most taxpayers hold cryptocurrencies through a cryptocurrency exchange platform. Coinbase, for example, which recently underwent a highly publicized initial public offering (IPO) and IRS summons for information concerning its participants, is one of the most popular cryptocurrency exchanges. (Additional detail regarding the Coinbase summons is available on our Tax Controversy 360 blog.) After a hard fork, some exchanges immediately adopt the new cryptocurrency and permit its use on the exchange; however, others only do so after a period of evaluation, if ever. The Hard Fork CCA takes the position that a taxpayer who privately holds their Bitcoin using a private key to a distributed ledger or holds their Bitcoin on an exchange which adopts Bitcoin Cash immediately recognizes income upon the occurrence of the hard fork. In contrast, a taxpayer who held their Bitcoin on an exchange that did not immediately adopt Bitcoin Cash did not recognize income until transactions in Bitcoin Cash were permitted on that exchange. The Hard Fork CCA further provides that taxpayers can determine the value of Bitcoin Cash using any reasonable method and endorsed adopting the publicly published price value at a cryptocurrency exchange or cryptocurrency data aggregator as an example of a reasonable method.
Since at least 2014 when IRS Notice 2014-21 was published, the IRS has taken the position that cryptocurrency, or virtual currency, is treated as property for federal income tax purposes and that longstanding principles applicable to transactions involving property apply to cryptocurrencies. (See: Notice 2014-21, 2014-16 IRB 938.) Additional guidance since that time has been largely limited to FAQs concerning Notice 2014-21, Revenue Ruling 2019-24 (2019-44 IRB 1004) and Chief Counsel Advice 202035011. Revenue Ruling 2019-24 is directly related to the Hard Fork CCA and concludes that taxpayers recognize gross income where a cryptocurrency hard fork is followed by an “air drop” of the asset into their account. Chief Counsel Advice 202035011 concerns the receipt of convertible cryptocurrencies for performing tasks on crowdsourcing platforms and concludes the receipt of such convertible cryptocurrency is taxable as ordinary income.
THE HARD FORK CCA CONFLICTS WITH EXISTING IRS GUIDANCE
The lack of guidance regarding the tax treatment of cryptocurrency has led to questions and debate over which type of property cryptocurrency is most analogous to and what principles should be used in evaluating particular types of cryptocurrency transactions. The Hard Fork CCA appears to view cryptocurrency value primarily in its use as a medium of exchange. The evaluation of the Bitcoin hard fork contrasts to some degree with a prior line of IRS guidance concerning unsolicited merchandise (specifically books). This line of guidance is typified by GCM 36639 (GCM), concerning copies of the Congressional Record provided to members of Congress free of charge. The GCM concludes that “it is clearly the position of the Service that the mere receipt of books does not constitute income. Rather, the inclusion of the value of the books in income is dependent on the taxpayer accepting them as his own.” The GCM and related authority concerning receipt of free books provides that taxpayers manifest acceptance of books, and thus recognize income not upon receipt, but only when they contribute the books to charity and claim a deduction, place the books in their personal library or sell them. Under this line of authority, taxpayers do not recognize income if they return or discard the books. The GCM is consistent with Revenue Ruling 70-498 (1970-2 CB 6), which determined a book reviewer recognized gross income for the value of unsolicited books when they donated the books to charity and claimed a charitable deduction. Revenue Ruling 70-498 superseded Revenue Ruling 70-330 (1970-1 CB 14), which determined that the retention of unsolicited books alone caused a taxpayer to recognize income.
The distinctions between books and cryptocurrencies are numerous, however, the apparently distinct tax treatment underscores the need for additional guidance in the developing area of cryptocurrency taxation. This guidance will require a clear and consistent articulation of the nature of cryptocurrency. The IRS has not consistently held that the ability to exchange property, even investment property, demonstrates sufficient control to trigger income recognition. A taxpayer can sell a book, and that book may increase in value dramatically from the date it is received. Where the taxpayer stores that book, whether boxed in their basement or proudly displayed in their library, does not significantly alter their ability to sell it. However, the IRS appears to assert that storage of cryptocurrency in a form where it is accessible for sale leads to income recognition. Depending on what type of property one thinks cryptocurrency is most analogous to, IRS positions in the Hard Fork CCA may be subject to future challenge in several respects, including with regard to the taxable event itself and its timing. If the IRS continues to assert these positions, future guidance should provide a clear articulation of why cryptocurrency is distinct from other forms of property and why these distinctions require different tax results. Guidance is particularly critical in light of the growing variety, value and popularity of digital assets evidenced by the recent boom in non-fungible tokens commonly referred to as NFTs.
Practice Point: Despite its increasing popularity and constant attention in the media, guidance on the taxation of cryptocurrencies is developing very slowly. If you are investing or thinking about investing in cryptocurrencies, you should consider and prepare for their tax consequences. For example, if your cryptocurrency experiences a hard fork, the IRS appears to believe that you have a taxable event (and owe federal income tax) on the value of the new cryptocurrency created from the hard fork. Failure to report the income could subject you to penalties and interest. If the IRS can prove you failed to report the income purposely, you might be facing criminal penalties. With careful and deliberate planning and advice, you can avoid some of the pitfalls that have befallen thousands of cryptocurrency investors. For additional information on the taxation of cryptocurrencies, please see our analysis of virtual currency staking activities, virtual currency mining activities and analysis on our Tax Controversy 360 blog.